Do You Have to Pay a Deceased Parent’s Debts in Florida?

Adult child reviewing paperwork about a deceased parent's debts in Florida.

Do You Have to Pay a Deceased Parent’s Debts in Florida?

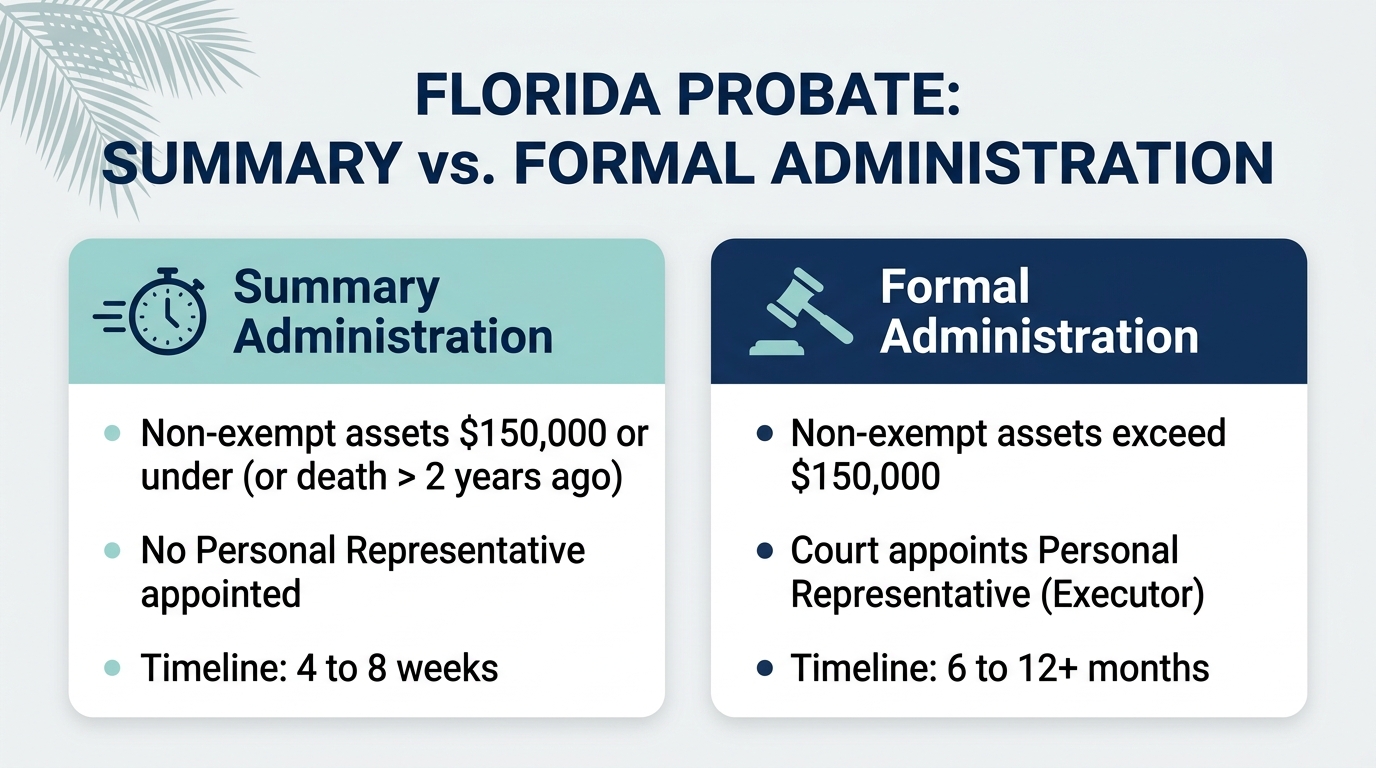
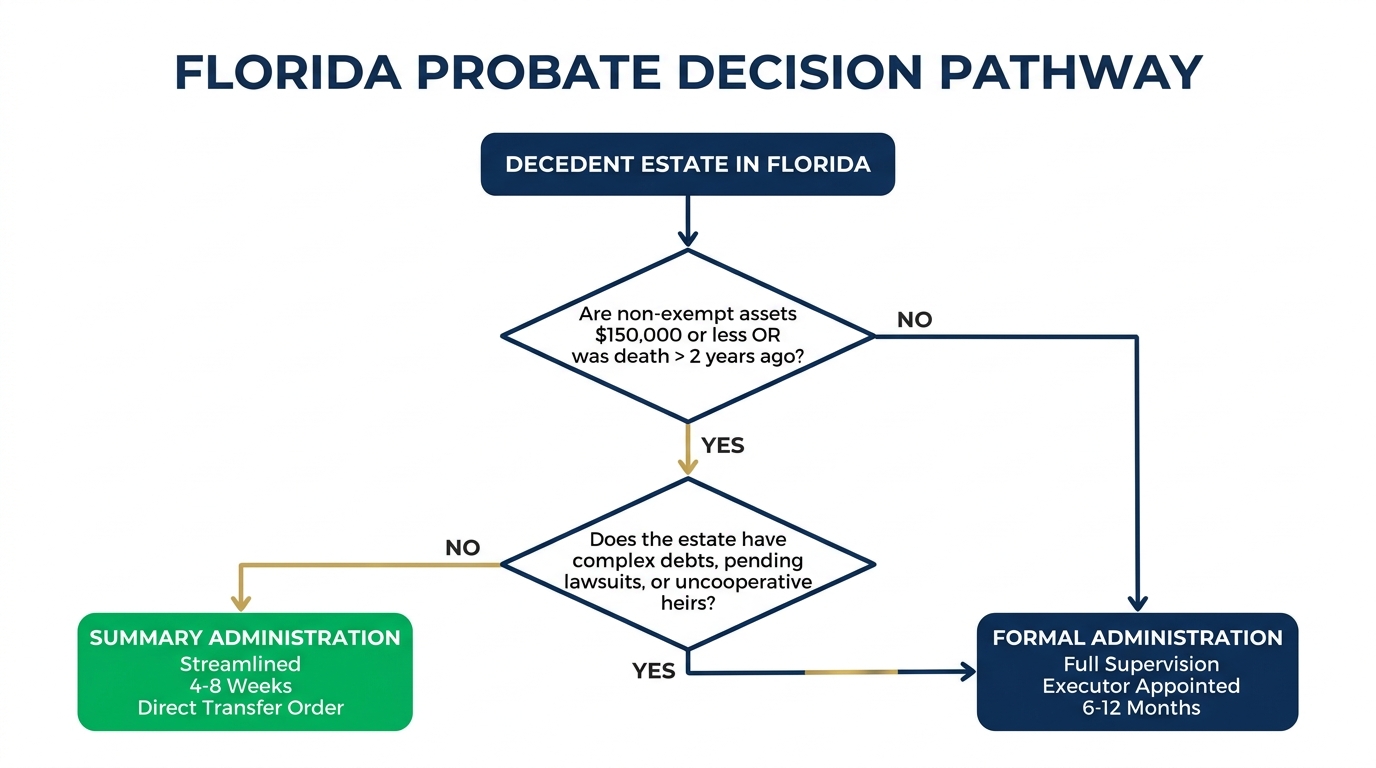
No. In Florida, children generally do not have to pay a deceased parent’s debts from their own money simply because they are family members. Valid debts are usually paid from the deceased parent’s estate during probate. If the estate lacks sufficient assets, unpaid debts do not automatically become the children’s personal responsibility.

  • The estate: Generally pays valid debts from available estate assets.
  • The personal representative: Handles creditor claims and pays debts according to Florida probate law.
  • The children or other heirs: Generally are not personally liable unless a separate legal obligation applies.
  • Secured creditors: May retain rights against property securing a debt, such as a mortgaged home.

When must you pay a deceased parent’s debt?

You may be personally responsible if you:

  • Co-signed a loan or other credit agreement.
  • Are legally liable for a joint credit account.
  • Separately agreed to assume the debt.
  • Received an improper estate distribution that you may be legally required to return.

Inheriting property does not automatically make you personally responsible for every debt your parent owed. However, a mortgage or another valid lien may remain attached to inherited property.

If a credit card company, hospital, or debt collector contacts you after your parent’s death, determine whether the claim is against the estate or against you personally. A demand for payment does not, by itself, establish that you owe the debt.


Who Pays a Parent’s Debts After Death?


In most cases, the deceased person’s estate is responsible for valid debts. The estate consists of assets and property available to settle the deceased person’s affairs under the applicable law.

When a Florida probate case is opened, the personal representative is responsible for administering the estate. This includes identifying assets, reviewing creditor claims, paying obligations in the legally required order, and distributing any remaining property to beneficiaries.

The personal representative does not automatically become personally liable for the deceased person’s debts. Their role is to handle the estate according to Florida law.

Consider a parent who dies with $25,000 in credit card debt and leaves $10,000 in available estate assets. The credit card company may seek payment from the estate, but the deceased person’s child does not automatically owe the remaining $15,000. If the estate cannot cover all its valid debts, some creditors may receive partial payment or nothing at all.

This is the general rule described by the Federal Trade Commission. The important exceptions arise when a relative has an independent legal obligation or when estate property has been handled improperly.


When Can You Be Personally Responsible for a Parent’s Debt?

Your relationship with the deceased does not ordinarily make you responsible for their debts. Certain financial arrangements, however, can create personal liability.

You co-signed a loan

If you co-signed your parent’s car loan or personal loan, you may remain responsible for the balance after their death. Your obligation comes from the agreement you signed, not from being their child.

Review the contract before assuming you owe the balance. If a creditor claims you co-signed an account and you dispute that assertion, ask for documentation supporting its position.

You were a joint account holder

A person who is legally responsible for a joint credit account may remain liable after the other account holder dies. That situation differs from being an authorized user on someone else’s credit card. An authorized user generally does not become responsible for the debt solely by having permission to use the account.

If a collector says you owe the balance, ask which agreement or account status creates that obligation.

You agreed to assume the debt

You may have a separate obligation if you signed a contract or made an enforceable agreement to pay the debt. Helping a parent manage their finances, handling paperwork after their death, or being named in their will does not by itself establish personal liability.

This distinction matters when a family member has been helping with a parent’s care or finances for years. Managing someone else’s bills is not the same as agreeing to become the borrower.

You mishandled estate assets

A separate issue arises if you receive money from an estate before the applicable debts and expenses have been addressed.

Florida Statutes § 733.812 allows recovery of certain improper distributions. Depending on the circumstances, a beneficiary may have to return property or funds distributed improperly. A personal representative may also face liability for failing to perform their legal duties.

That does not mean every mistake makes a child responsible for all a parent’s debts. It does mean that anyone distributing estate property should understand which claims must be addressed first.

Adult child receiving a debt collection call about a deceased parent's bills in Florida.

What Happens If the Estate Cannot Pay All Its Debts?

When an estate has insufficient assets to pay every valid claim, Florida law determines which obligations receive payment first.

Under Florida Statutes § 733.707, estate expenses and obligations are divided into statutory priority classes. Administration expenses come first, followed by specified funeral and interment expenses. Other categories include certain preferred debts and taxes, qualifying medical expenses from the final illness, and other claims.

Ordinary unsecured debts generally fall behind claims with higher statutory priority. If the estate cannot pay all claims within a class, the available funds may have to be distributed proportionately among those claims.

For example, suppose a parent leaves a small bank account but owes substantially more than the account contains. The personal representative cannot necessarily pay whichever creditor calls first. They must evaluate the claims and follow the applicable payment priorities.

An estate with insufficient funds does not automatically pass the shortfall to the children. The result depends on the assets available, the claims filed, and any separate legal obligations held by family members.

For families in Broward County, this is one reason to be cautious about paying a creditor immediately just because it demands payment. The estate’s financial position and the applicable priorities need to be reviewed first.


How Long Do Creditors Have to Claim a Debt in Florida?

Florida law establishes deadlines for claims against a deceased person’s estate. Missing the applicable deadline can prevent a creditor from enforcing its claim against the estate.

Under Florida Statutes § 733.702, the usual deadline is three months after the first publication of the notice to creditors. For a creditor required to receive individual service, the deadline is generally 30 days after service if that date falls later.

A separate provision, § 733.710, generally bars claims against the estate, personal representative, and beneficiaries two years after the person’s death, subject to the statute’s exceptions. It also preserves certain recorded mortgages and security interests.

These deadlines should not be treated as interchangeable. The relevant dates, the creditor’s status, and the type of claim can affect the result. A creditor who was known or reasonably ascertainable but did not receive required notice may raise a different legal issue from one that had proper notice.

If you are administering an estate, keep records of creditor communications and obtain legal advice before deciding that a claim is too late to matter.


Can a Debt Collector Make You Pay Your Parent’s Bills?

A debt collector cannot make you personally responsible for a parent’s debt simply by demanding payment. If you did not co-sign the obligation, become legally responsible for the account, or otherwise incur liability, being the deceased person’s child is generally not enough.

Federal law also restricts how debt collectors communicate about deceased consumers’ debts. Collectors may contact certain people to locate the person authorized to administer an estate. That does not give them permission to misrepresent who owes the money.

If a collector insists that you must pay, ask for the legal basis of that claim. Keep copies of letters and messages, and make a record of calls where appropriate. If the collector threatens to sue you personally, or continues to demand payment despite a clear dispute about your liability, consider seeking legal advice.

The Consumer Financial Protection Bureau explains the rules for debt collectors dealing with deceased relatives’ debts.


Do You Have to Use Your Inheritance to Pay a Parent’s Debts?

Not necessarily. The answer depends on how the property passes to you, whether it is available to satisfy estate claims, and whether a lien or another legal obligation applies.

Some assets pass directly to a named beneficiary rather than through the ordinary probate process. Life insurance with a valid beneficiary designation is a common example. Other assets may be part of the probate estate and subject to its administration.

The distinction is important, but it does not mean that every asset passing outside probate is automatically protected from every creditor. Florida law includes specific rules governing creditor claims, trusts, and exempt property. The result can depend on the ownership arrangement and the type of asset involved.

If you expect to receive money or property from a parent’s estate, establish how the asset passes before assuming that it must be used to pay a debt—or that creditors have no possible claim against it.


What If You Inherit a House With a Mortgage?

Inheriting a home does not necessarily eliminate the mortgage or another valid lien attached to the property. A lender may retain enforcement rights even after the borrower dies.

Florida’s two-year limitation on certain estate claims expressly preserves specified recorded mortgages and security interests. A deadline that bars an ordinary claim does not automatically remove a mortgage lien.

The property’s status under Florida homestead law can also affect the probate process and the rights of surviving family members. Protected homestead property is treated differently from other estate assets. Whether a particular home qualifies depends on the facts and applicable legal requirements.

Before selling, transferring, or making major financial decisions about an inherited home, determine whether a mortgage or another lien remains in place. It is also important to establish how ownership passes and whether any homestead protections apply.

Siblings discussing an inherited family home with a mortgage in Florida.

Can Creditors Take Money From a Living Trust?

A living trust does not automatically make every asset unavailable to creditors after the person who created it dies.

Florida Statutes § 736.0505 addresses creditor claims against a trust settlor. The law generally makes property in a revocable trust subject to the settlor’s creditors during the settlor’s lifetime to the extent the property would not otherwise be exempt if owned directly. Florida probate law also contains provisions addressing certain trust assets when the probate estate is insufficient to pay expenses and obligations.

The outcome depends on the trust’s terms, the assets it holds, applicable exemptions, and the circumstances of the estate. A trust can affect how property is transferred and administered, but its existence alone does not establish that creditors have no rights.

If your parent used a revocable living trust, review the trust documents and determine whether any statutory obligations apply before assuming the assets are beyond the reach of valid claims.


Are There Special Rules for Medicaid and Medical Debts?

Medical bills are generally handled as claims against the deceased person’s estate. A child does not automatically become responsible for a parent’s medical expenses simply because they are related.

Florida also has a Medicaid Estate Recovery Act. Under Florida Statutes § 409.9101, the state may pursue recovery for qualifying Medicaid assistance provided after the recipient reached age 55, subject to applicable federal and state requirements.

The law contains exceptions and protections. The type of property involved can also affect whether recovery is available. If the estate received Medicaid benefits, or if a substantial medical claim appears after a parent’s death, it is worth determining exactly what kind of claim has been made.

A private medical bill and a Medicaid estate recovery claim are not the same thing. Each must be assessed under the rules that apply to it.


What Should You Do Before Paying a Parent’s Debt?

If a creditor contacts you after a parent’s death, take a moment to establish what is being requested and why.

  • Find out who owes the money. Ask whether the creditor is making a claim against the estate or alleging that you are personally liable.
  • Review any agreement you signed. A co-signed loan or joint credit obligation may create liability that a family relationship alone would not.
  • Keep estate money separate from your own. If you are the personal representative, do not distribute estate assets or pay selected creditors before understanding the applicable probate rules.
  • Do not ignore formal notices. A demand letter is different from a court document. If you receive legal papers, pay attention to the stated deadlines.

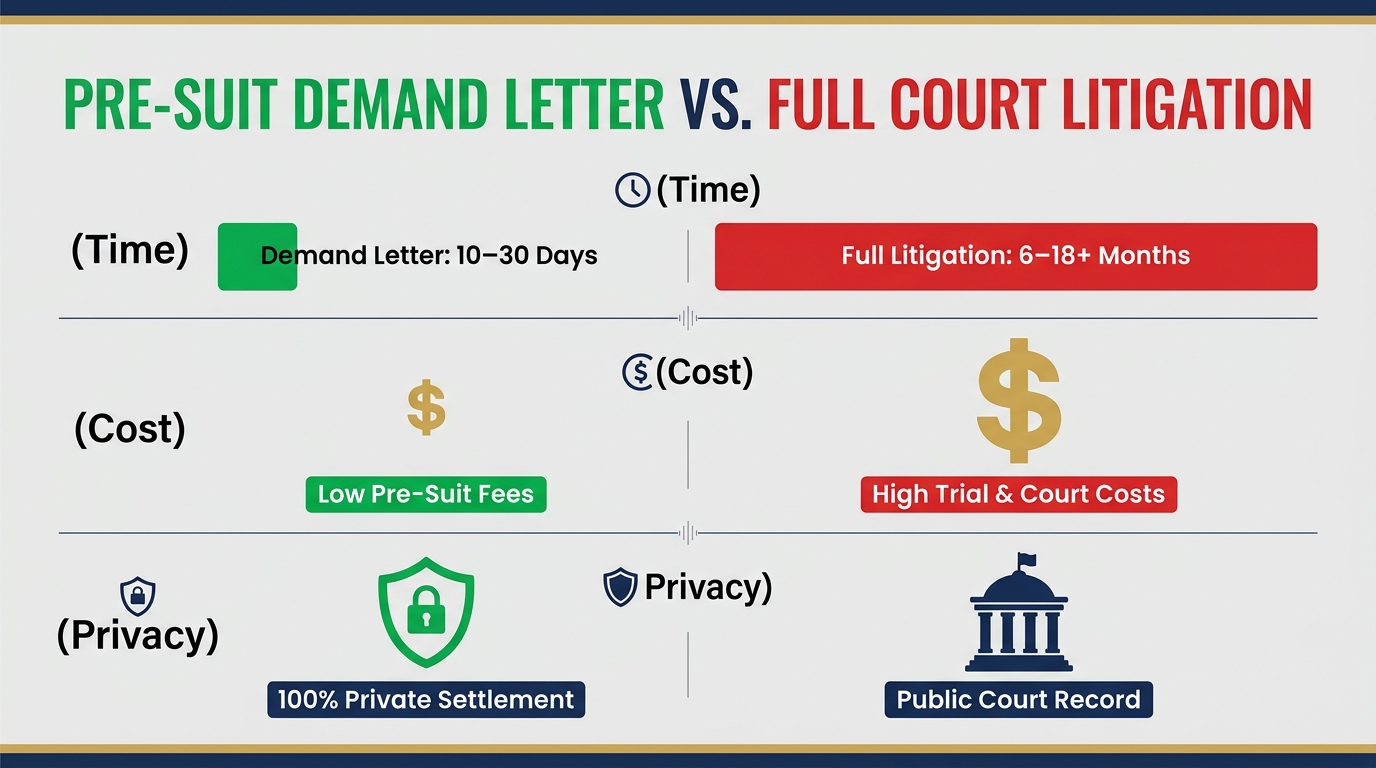
If the claim is disputed, the estate has limited assets, or an inherited home is involved, get advice before committing your own money. A payment made under pressure can complicate an already difficult situation.

Probate attorney discussing creditor claims with a personal representative in Coral Springs

When Should You Speak With a Probate Attorney?

Legal guidance can be especially useful when the estate has insufficient assets, a creditor disputes the handling of its claim, or family members disagree about whether property should be sold or distributed.

An attorney can review the estate’s assets and liabilities, determine which creditor deadlines apply, and help the personal representative follow Florida’s payment priorities. Advice may also be necessary when a family home is involved or a trust holds substantial property.

Families in Coral Springs and elsewhere in Broward County may need to determine which assets are available to pay creditors, whether a claim was filed on time, and whether an heir has any personal responsibility for the balance. A probate attorney can review those questions under Florida law before the family pays a disputed debt or distributes estate property.


If you are settling a parent’s estate or have been contacted about a debt you believe you do not owe, a Florida probate attorney can help you understand your obligations before you make a payment or distribute inherited property.


Frequently Asked Questions


Do children inherit debt in Florida?

  • Children generally do not become personally responsible for a parent’s debts simply because the parent dies. Valid debts are usually handled through the estate, although a child may be liable under a separate agreement, such as a co-signed loan.

Can a credit card company make me pay my deceased parent’s credit card debt?

  • Generally, no, unless you have an independent legal obligation, such as liability as a joint account holder or under a separate agreement. The company may still submit a valid claim against the parent’s estate through the applicable probate process.

What happens if my parent dies with more debt than assets?

  • The estate’s assets are used to pay valid claims according to Florida’s statutory priorities. If the estate cannot pay every claim, lower-priority creditors may receive partial payment or nothing. A child does not automatically have to cover the shortfall with personal funds.

Do I have to use my inheritance to pay my parent’s debts?

  • Not automatically. The answer depends on whether the asset is part of the probate estate, how it passes to you, and whether any lien or other legal obligation applies. Some assets pass directly to beneficiaries, but that does not guarantee protection from every creditor claim.

Can I keep my parent’s house if they still owe a mortgage?

  • Possibly, but inheriting the house does not automatically remove the mortgage. The lender may retain rights against the property. The outcome depends on the loan, the property’s ownership and homestead status, and the circumstances of the inheritance.

How long do creditors have to claim a debt after someone dies in Florida?

  • The usual probate claim deadline is three months after the first publication of the notice to creditors. For a creditor entitled to individual service, the deadline is generally 30 days after service if that date falls later. Florida also has a separate two-year limitation measured from death, subject to statutory exceptions. The correct deadline depends on the claim and the circumstances.

Can I be sued for distributing my parent’s money before paying creditors?

  • Potentially. If you receive an improper distribution from an estate, Florida law may permit recovery of the property or funds. A personal representative may also face consequences for failing to follow their legal duties. The outcome depends on the facts and the applicable statutes.

Does a living trust protect my parent’s assets from creditors?

  • Not automatically. Florida law allows certain creditor claims involving revocable trusts, and some trust assets may be subject to estate obligations when probate assets are insufficient. The trust documents and applicable law must be reviewed to determine what protections exist.

Can Florida Medicaid recover money after a parent dies?

  • In some cases. Florida’s Medicaid Estate Recovery Act allows recovery for qualifying Medicaid assistance provided after the recipient reached age 55, subject to legal requirements and exceptions. Whether recovery can be made from particular property depends on the facts and applicable protections.

This article provides general information about Florida law and is not legal advice for a specific estate or debt. Deadlines, exemptions, and personal liability depend on the facts of the case.
Types of Probate Agreements in Florida: Contracts and Key Legal Documents Explained

Vector infographic of probate contracts and legal instruments under Chapter 733 of Florida law in Broward County.

Executive Summary

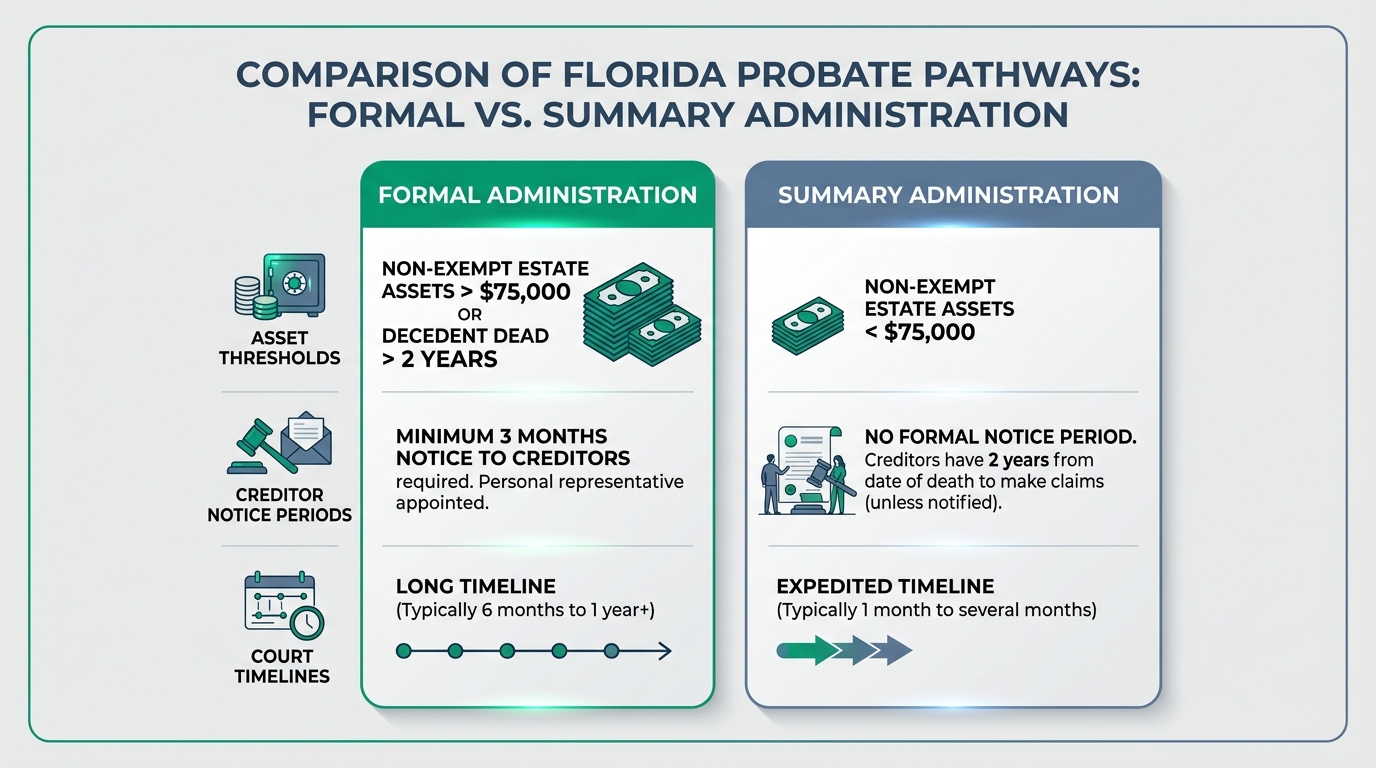
Under Chapter 733 of the Florida Statutes, probate administration involves private bilateral contracts like beneficiary redistribution agreements, settlement compromises, or real estate purchase contracts, alongside essential court instruments like Letters of Administration, Orders Determining Homestead, and Petitions for Exempt Property.

While contracts allow heirs, personal representatives, and creditors to voluntarily restructure rights or resolve disputes, court orders and statutory filings are strictly required to clear title, transfer legal ownership, and protect protected assets in Florida probate proceedings.


Table Of Contents
  1. Executive Summary
  2. PART 1: Private Contracts and Bilateral Agreements in Florida Probate
  3. 1. Private Agreements Among Interested Persons (Fla. Stat. § 733.815)
  4. 2. Family Settlement Agreements and Compromises (Fla. Stat. § 733.708)
  5. 3. Personal Representative Service and Vendor Contracts (Fla. Stat. §§ 733.612 and 733.619)
  6. 4. Real Estate Purchase and Sale Agreements in Probate (Fla. Stat. § 733.613)
  7. 5. Creditor Debt Settlement and Compromise Agreements (Fla. Stat. § 733.708)
  8. 6. Attorney and Professional Engagement Agreements (Fla. Stat. §§ 733.6171 and 733.6175)
  9. 7. Contracts Concerning Succession and Agreements to Make a Will (Fla. Stat. § 732.701)
  10. 8. Premarital and Postmarital Elective Share or Property Waivers (Fla. Stat. § 732.702)
  11. PART II: Critical Non-Contractual Probate Documents
  12. Summary Matrix: Contracts vs. Non-Contractual Probate Instruments
  13. Frequently Asked Questions (FAQs)
  14. Let Us Take the Stress Off Your Shoulders

Let us be completely honest with each other for a second. Nobody wakes up on a sunny Tuesday morning in South Florida thinking, I really hope I get to read a fifty page legal breakdown of Florida probate contracts today!

If you found your way to this page, someone you cared about likely passed away, or a lawyer handed you a stack of paperwork thick enough to act as a doorstop. Now you have to make sense of it all.

When an estate enters probate under Chapter 733 of the Florida Statutes, families quickly discover that the legal world runs almost entirely on paperwork. Some of these papers are genuine, two-sided contracts where living people negotiate terms. Others are formal court orders that require a judge to stamp a seal before anyone can touch a single dollar in a bank account.

Here is an honest, straightforward guide to every contract and document you might encounter in South Florida, written in plain language without the dense legalese that usually makes people fall asleep at their desks.


PART 1: Private Contracts and Bilateral Agreements in Florida Probate

In ordinary life, a contract requires a mutual agreement, an offer, and something of value changing hands. In the probate realm, contracts serve as the legal tools that let living people fix messy situations, buy out family members, or hire experts to clean out a dusty attic.


1. Private Agreements Among Interested Persons (Fla. Stat. § 733.815)

What It Is and How It Looks

A Private Agreement Among Interested Persons looks like a standard legal contract. It starts with a caption identifying the estate, followed by a long list of “Whereas” clauses that explain the background.

The main text outlines who gets what, releases everyone from liability, and includes signature lines that require proper legal validation. It must state clearly that all parties are competent adults and that no creditor is getting cheated out of money.

Detailed Scenario

Mateo and Sofia are adult siblings who inherited their late father’s estate in Coral Springs. The father’s will leaves everything split equally between them. The estate consists of a house worth $400,000 and an investment account worth $400,000.

Mateo wants to live in the house. Sofia prefers cash so she can buy a condo in Miami.

Instead of forcing a quick sale of the home that neither of them actually wants, their lawyer drafts an agreement under Section 733.815. Mateo gets full ownership of the house, Sofia gets the investment account, and Mateo pays her an extra $25,000 to cover minor valuation differences.

Legal Mechanics

Under Florida Statutes Section 733.815, heirs can agree to trade or reallocate assets however they like. The personal representative must confirm that all estate debts, final taxes, and administrative fees are covered before handing over the keys.


2. Family Settlement Agreements and Compromises (Fla. Stat. § 733.708)

What It Is and How It Looks

A Family Settlement Agreement looks like a high stakes corporate treaty. It includes agreed facts, complete releases of liability, and a clause submitting the deal to the 17th Judicial Circuit Court in Broward County.

Crucially, it includes a paragraph requiring the executor to present the contract to the probate judge for official sign off.

Detailed Scenario

A resident of Fort Lauderdale passes away and leaves behind a brand new will that disinherits his child from a first marriage, leaving everything to a second spouse. The child hires a lawyer and claims the new spouse used undue influence when the father was sick.

Both sides realize that fighting in court for three years will only make the litigation lawyers rich.

During mediation, they draft a Family Settlement Agreement. The surviving spouse agrees to pay the child a flat cash settlement and hand over a few family heirlooms. In exchange, the child drops the lawsuit and agrees never to sue the estate again.

Legal Mechanics

Florida law loves family settlements because they keep relatives from screaming at each other in courtroom hallways. Submitting the contract under Section 733.708 turns a private agreement into a binding court order. This step is mandatory if any beneficiaries are minors, since kids cannot legally sign away their rights without a judge checking the math first.


Vector diagram explaining private agreements among heirs for asset distribution under Florida Statute 733.815.

3. Personal Representative Service and Vendor Contracts (Fla. Stat. §§ 733.612 and 733.619)

What It Is and How It Looks

A Fiduciary Service Contract looks like a typical vendor agreement for home repairs or estate sales. The key difference is tucked away in the very first paragraph and the signature block.

It must state that the person signing is acting only as the representative of the estate, not as an individual paying out of their own pocket.

Detailed Scenario

The executor of an estate in Coral Springs needs to fix a damaged roof, paint the living room, and clear out forty years of accumulated furniture before putting a home on the market. The executor hires a licensed roofing company and a professional estate sale team.

This executor signs the contracts. Because they are managing someone else’s property, they must ensure the contract text protects their personal savings account if something goes wrong on the job site.

Legal Mechanics

Florida Statutes Section 733.612 gives an executor the authority to hire workers to preserve estate property. Under Section 733.619, an executor becomes personally liable for the bill if they forget to specify their official title on the signature line. If you sign your name without adding “as Personal Representative of the Estate,” the contractor can legally demand payment directly from your personal checking account.


4. Real Estate Purchase and Sale Agreements in Probate (Fla. Stat. § 733.613)

What It Is and How It Looks

A Probate Real Estate Purchase Agreement uses standard residential contract forms alongside specific probate clauses.

The seller line must list the seller in their official representative capacity. The agreement always includes a clause making the sale contingent on court approval or proper probate filings.

Detailed Scenario

A decedent owned a house in Coral Springs, and a buyer puts in a great cash offer.

The real estate agent writes up the contract, but the closing attorney notices that the deceased person died without a valid will. That means there is no written clause granting a power of sale.

Legal Mechanics

Under Florida Statutes Section 733.613, if a will does not explicitly give the executor the power to sell real estate, the executor cannot transfer title on their own. The contract sits in limbo while the probate lawyer files a formal petition with the Broward County court. All heirs receive formal notice, and the judge must sign an order approving the sale before the closing can happen.


Residential real estate purchase contract for a probate property sale in Coral Springs and Broward County.

5. Creditor Debt Settlement and Compromise Agreements (Fla. Stat. § 733.708)

What It Is and How It Looks

A Creditor Compromise Agreement is a short contract between the executor and a creditor like a credit card company or hospital.

It states the original debt amount, acknowledges that the estate has limited funds, sets a lower lump sum payment, and confirms that the debt is fully canceled once the check clears.

Detailed Scenario

A decedent leaves behind $30,000 in credit card bills, but the estate only holds $12,000 in a checking account along with a protected primary home.

Credit card companies cannot touch a protected Florida homestead. That $12,000 in the bank is the only cash available to pay off every bill. The executor calls the credit card companies and offers each one a fraction of what they are owed to settle the accounts completely.

Legal Mechanics

Section 733.708 allows an executor to negotiate and settle debts for lower amounts. However, Florida law enforces a strict priority list for paying bills under Section 733.707.

Funeral costs, court administrative fees, and final hospital bills take priority over credit cards. Paying off a low priority credit card before settling the funeral bill can make the executor personally responsible for paying the funeral home out of their own pocket.


6. Attorney and Professional Engagement Agreements (Fla. Stat. §§ 733.6171 and 733.6175)

What It Is and How It Looks

A Probate Retainer Agreement is a formal contract between the executor and the law firm. It explains the legal scope of work, hourly rates or percentage fee schedules, upfront costs, and court filing expectations.

Florida law requires specific written disclosures explaining how probate attorney fees are calculated.

Detailed Scenario

A newly appointed executor in Broward County feels completely overwhelmed by the legal paperwork and hires a local probate law firm to manage the estate.

The law firm provides an engagement agreement detailing whether they will charge an hourly rate or use the standard state fee percentage based on the total value of the estate assets.

Legal Mechanics

Florida Statutes Section 733.6171 sets statutory fee guidelines that courts consider reasonable for probate lawyers. Under Section 733.6175, any heir who thinks the lawyer is charging too much can ask the probate judge to review the bill and cut the fee down to a fair amount.


7. Contracts Concerning Succession and Agreements to Make a Will (Fla. Stat. § 732.701)

What It Is and How It Looks

A Contract to Make a Will is an agreement created while the person is still alive. It looks like a hybrid between a commercial contract and a will, explicitly stating that one person agrees to leave specific property to another in exchange for a clear action or service.

Detailed Scenario

An elderly parent tells their adult child that if the child moves to Coral Springs, quits their job, and acts as a full time caregiver, the parent will leave them the family home in their will. The child moves in and takes care of the parent for five years.

When the parent passes away, a surprise will surfaces that leaves the entire house to a local pet shelter.

The child files a claim against the estate using their written caregiver contract.

Legal Mechanics

Under Florida Statutes Section 732.701, an agreement to make a will or leave an inheritance is completely useless unless it is written down and signed in front of two attesting witnesses. Casual verbal promises made over dinner carry zero weight in a Florida courtroom, no matter how unfair the situation seems.


8. Premarital and Postmarital Elective Share or Property Waivers (Fla. Stat. § 732.702)

What It Is and How It Looks

A Waiver of Spousal Probate Rights is a specialized contract, usually included inside a prenuptial or postnuptial agreement. It contains clear clauses where a spouse gives up their rights to the elective share, homestead property, exempt assets, and family allowances.

Detailed Scenario

Two people get married later in life. Both own homes in South Florida and have adult children from previous marriages. They want their homes to pass directly to their biological kids without any surviving spouse claims getting in the way.

They sign a prenuptial agreement waiving all probate inheritance rights. When the husband passes away, the wife steps aside so the kids can inherit the house cleanly.

Legal Mechanics

Under Florida Statutes Section 732.702, a spouse can sign away their inheritance rights. The document must be in writing and signed in front of two attesting witnesses. Signing this document after the wedding requires a full, honest written disclosure of all personal assets and bank accounts.


PART II: Critical Non-Contractual Probate Documents

Contracts are voluntary agreements between people. The rest of the probate world runs on court orders, official petitions, and statutory filings. You need to know these documents just as well as any contract.


1. Letters of Administration

  • What It Is: The official document issued by a probate judge that appoints the executor and grants them the legal authority to handle the estate.
  • How It Looks: A single page court document featuring the raised seal of the Broward County Clerk of Courts, the case number, and the judge’s signature.
  • When It Comes Into Play: You cannot move money, close accounts, or sell property without this document. Bank managers will refuse to speak with you until you hand them a certified copy of these Letters.

2. Petition and Order Determining Homestead Property (Fla. Const. Art. X, § 4 and Fla. Stat. § 732.401)

  • What It Is: A formal court request and judge’s order declaring that a house was the deceased person’s primary Florida residence.
  • How It Looks: A legal order containing the property address, legal parcel details, and an official ruling that the house passes directly to protected family members.
  • When It Comes Into Play: A primary residence in Florida receives massive legal protection under the state constitution. Protected homestead property passes to heirs completely free from most creditor claims, and it sits outside the standard probate estate process.

3. Petition to Determine Exempt Property (Fla. Stat. § 732.402)

  • What It Is: A formal court filing asking the judge to set aside specific personal belongings for the surviving spouse or minor children.
  • How It Looks: A court filing listing household furniture up to $20,000, college savings accounts, and up to two personal cars.
  • When It Comes Into Play: When creditors come knocking, the surviving spouse files this petition to protect the family cars and living room furniture from being seized to pay off old bills.

4. Statement of Claim (Fla. Stat. § 733.703)

  • What It Is: The official form a creditor files with the court to demand payment for an unpaid debt.
  • How It Looks: A short court form detailing the amount owed, the reason for the debt, and attached proof like credit card statements or medical bills.
  • When It Comes Into Play: Creditors must file this form within three months of the public probate notice, or within thirty days of receiving direct notice. If a creditor misses the deadline, their claim gets wiped out forever.

5. Disclaimer of Interest (Fla. Stat. § 739.104)

  • What It Is: An official written statement where an heir says, No thank you, I do not want this inheritance.
  • How It Looks: A notarized statement filed directly with the court, detailing the exact asset or inheritance share being refused.
  • When It Comes Into Play: People use this document when accepting an inheritance would trigger a massive tax bill, or when they want the asset to pass directly to their own children instead.

Summary Matrix: Contracts vs. Non-Contractual Probate Instruments

Document or Instrument TypeLegal NatureGoverned ByPrimary Purpose in Probate
Private Agreement (§ 733.815)Bilateral ContractFla. Stat. § 733.815Lets heirs change how assets are divided among themselves.
Family Settlement AgreementMultilateral ContractFla. Stat. § 733.708Resolves serious family disputes and stops active lawsuits.
Vendor ContractCommercial ContractFla. Stat. §§ 733.612, 733.619Hires workers while protecting the executor’s personal money.
Real Estate Purchase AgreementCommercial ContractFla. Stat. § 733.613Handles the sale of estate owned houses or land.
Creditor Compromise AgreementBilateral ContractFla. Stat. § 733.708Settles unpaid debts for lower cash payouts.
Letters of AdministrationCourt OrderFla. Stat. Chapter 733Gives the executor official authority to manage the estate.
Order Determining HomesteadJudicial OrderFla. Const. Art. X, § 4Protects the family home from general debt collectors.

Vector representation of Letters of Administration issued by the 17th Judicial Circuit Court of Broward County.

Frequently Asked Questions (FAQs)


1. Can siblings legally change how an inheritance is divided in Florida?

  • Yes. Under Florida Statutes Section 733.815, competent adult heirs can sign a private contract to divide property however they want. The deal cannot cheat creditors or leave out non signing family members.

2. What happens if an executor signs a contract without using their official title?

  • Under Section 733.619, an executor who signs a contract without adding “as Personal Representative of the Estate” can be held personally responsible for paying the bill out of their personal savings.

3. Can you sell a house during probate in Broward County?

  • Yes, but the process depends on the will. If the will explicitly grants a power of sale, the executor can complete the deal. If there is no will, the contract must state that the sale depends on getting an approval order from a Broward County judge under Section 733.613.

4. Is an oral promise to leave property to someone in a Florida will valid?

  • No. Section 732.701 states that any agreement to leave an inheritance is completely invalid unless it is written down and signed in front of two witnesses.

5. What is the difference between a probate contract and a court order?

  • A probate contract is a voluntary agreement between living people. A court order is an official decision signed by a judge that carries the full force of the law.

6. Can heirs sign a contract to skip probate court entirely?

  • No. Private contracts cannot transfer legal ownership of assets that require court orders, like sole name real estate or locked bank accounts. Contracts only control how assets are shared within or after the court process.

7. How long do creditors have to file a claim against a Florida estate?

  • Under Section 733.702, creditors must file a formal Statement of Claim within three months of the published notice, or within thirty days of receiving direct notice. Late claims are permanently barred.

Let Us Take the Stress Off Your Shoulders

Trying to make sense of probate contracts, court orders, and inheritance rules while grieving a loved one is exhausting. You do not have to figure this out by yourself late at night.

If you need to settle a family dispute, protect a primary residence, or complete a property sale in Coral Springs or Broward County, reach out to our team at Reinfeld & Cabrera. Call us directly at (954) 866-8600 or send us a message online to set up a time to talk. We will handle the heavy legal lifting so you can focus on taking care of your family.

What Happens to Your Business If You Die or Become Incapacitated?

Business succession planning attorney meeting with a business owner in Coral Springs, Florida

Fast Answer: If a Florida business owner dies or becomes incapacitated, what happens to the business depends on the business structure, governing documents, estate plan, and applicable Florida law. Ownership may pass to heirs or other beneficiaries, while management authority may remain with other owners or designated decision makers. A business succession plan can establish what happens to the owner’s interest and who can manage the company when the owner can no longer do so.

Business owners spend years building companies that depend on their judgment, relationships, skills, and decisions.

Then life does what life does.

An owner dies. An illness leaves someone unable to work. A business partner suddenly has to deal with an estate. Family members inherit an ownership interest without knowing how the company operates. Employees are left wondering who can sign contracts, access accounts, or make decisions.

These situations raise two separate questions:

Who owns the business interest, and who has authority to run the business?

Those answers do not always point to the same person.

A Florida business succession plan addresses what happens to ownership and management when an owner dies, becomes incapacitated, retires, or otherwise can no longer participate in the company. Depending on the business, that plan may involve an operating agreement, shareholder agreement, buy-sell agreement, trust, power of attorney, estate plan, or several of these documents working together.


What Happens to a Business When the Owner Dies?

The answer depends heavily on the type of business and its governing documents.

If a person owns an interest in a Florida LLC, the ownership interest does not necessarily give the person’s heirs an automatic right to step into the owner’s management role.

Florida’s LLC statute distinguishes between a transferable interest and the rights of a member. A transferee generally receives the economic rights associated with the transferred interest but does not automatically acquire the right to participate in management or access company records.

Death can also cause an individual to cease being a member under Florida’s LLC statute, while the consequences of that dissociation depend on the governing law and the company’s operating agreement.

That can create a surprisingly awkward situation.

Imagine a company owned by two siblings. One dies and leaves everything to a spouse who has never worked in the business. The spouse may inherit an economic interest, while the surviving sibling continues operating the company.

Now everyone has a legitimate interest in what happens next.

The spouse wants to know what the inherited interest is worth. The surviving sibling wants to know who has authority to make business decisions. The company needs to continue operating.

An operating agreement or buy-sell arrangement can address those questions before anyone has to improvise.


What Happens If a Business Owner Becomes Incapacitated?

Death and incapacity create different legal problems.

When an owner dies, the estate and succession process becomes relevant. When an owner becomes incapacitated, the business may need someone with legal authority to act while the owner is still alive.

Florida’s Power of Attorney Act defines incapacity in part as the inability to take actions necessary to obtain, administer, and dispose of property, including business property.

A properly drafted durable power of attorney can allow an agent to continue exercising specified authority despite the principal’s later incapacity.

The document needs to grant the authority actually required. Florida law provides that an agent may exercise authority specifically granted in the power of attorney, and certain powers require specific enumeration.

That makes the details important for a business owner.

A document authorizing someone to handle personal banking does not necessarily answer every question involving ownership interests, company management, securities, contracts, or other business decisions.

A succession plan should therefore consider incapacity separately from death.


Does a Will Control My Business After I Die?

A will can determine who receives assets that pass through the estate, including an ownership interest in a business.

But the will does not automatically rewrite the company’s governing documents.

An LLC’s operating agreement governs important aspects of the company’s internal affairs. Florida law expressly provides that an LLC is bound by its operating agreement and that a person who becomes a member is generally bound by it as well.

Corporations have their own governing documents and statutory rules concerning shareholders, shares, directors, officers, and shareholder agreements. Florida’s Business Corporation Act separately addresses restrictions on share transfers and shareholder agreements.

This creates an important planning issue:


Your estate plan and your business documents need to work together.

Suppose a business owner leaves the company to three children in equal shares. The will may produce three equal ownership interests.

But what happens if one child wants to run the company, another wants to sell, and the third wants cash rather than an operating role?

The will alone may not provide a practical answer.


Can a Trust Own a Business Interest?

Yes. A trust can hold certain business interests, and trusts can be part of a broader estate and succession plan.

That does not mean putting an LLC interest into a trust automatically solves the succession problem.

The trust document has to address who controls the trust, who benefits from it, and what the trustee can do with the property. Florida law gives trustees significant powers, including powers to acquire and sell trust property, subject to the terms of the trust and the trustee’s fiduciary duties.

The business documents also have to be considered.

For example, an LLC operating agreement may contain restrictions or requirements concerning transfers, membership, voting, management, or the admission of new members.

A trust can therefore be one component of a succession plan rather than a substitute for the entire plan.


What Is a Buy-Sell Agreement?

A buy-sell agreement establishes rules for what happens to an owner’s business interest when a specified event occurs.

Depending on how it is drafted, the triggering event might include death, disability, retirement, divorce, termination of employment, or another circumstance affecting ownership.

A typical arrangement might give the company or the remaining owners the right, or sometimes the obligation, to purchase the departing owner’s interest.

The agreement can also address valuation and payment terms.

Consider the three-sibling example again.

If one sibling dies, the agreement might provide a mechanism for the surviving owners to purchase that sibling’s interest at a defined valuation methodology. The estate receives value, while the remaining owners retain control of the company.

That is a very different outcome from leaving three people to negotiate ownership after the death.

The details matter. Valuation formulas that seemed reasonable five years ago may produce strange results after the business has grown substantially. Funding also needs consideration. A purchase obligation is useful only if the parties have a realistic way to pay for it.


What Happens to a Family Business When the Owner Dies?

Family businesses create another succession problem: inheritance and management can point in different directions.

A child may inherit an ownership interest without having any experience running the company. Another child may have spent twenty years working in the business and expect to continue operating it.

Those interests can coexist, but the documents need to account for them.

A useful succession plan can address:

  • Who can own the business
  • Who can manage the business
  • Whether family members can transfer their interests
  • Whether existing owners have purchase rights
  • How an owner’s interest will be valued
  • How a purchase will be funded
  • What happens if an heir does not want to participate in the company
  • What happens if the owners disagree
  • What happens if an owner becomes incapacitated

As Alan Reinfeld puts it:

“A 50/50 split sounds wonderfully democratic until two people have a 50/50 disagreement.”

That problem becomes considerably harder when one of the two owners has died and the surviving owner is now dealing with the deceased owner’s estate.

Attorney discussing business continuity and incapacity planning with a Broward County business owner

Who Runs the Business While the Estate Is Being Settled?

This is one of the practical questions business owners often overlook.

A business does not necessarily stop operating because its owner has died. Employees still need to be paid. Customers still expect service. Contracts still need attention. Taxes and other obligations continue.

But the legal authority to make decisions can become complicated depending on the company’s structure and the owner’s role.

An LLC may be member-managed or manager-managed. Florida law provides different management structures, with management generally vested in the members of a member-managed LLC and in the managers of a manager-managed LLC.

That means the succession plan should account for management authority, not merely inheritance.

The same principle applies to corporations, partnerships, and other business structures.

The person who inherits the business and the person who runs the business do not necessarily have to be the same person.


What Documents Should a Business Owner Have in Place?

There is no universal package that works for every business.

Depending on the circumstances, a Florida business owner may need to coordinate several documents:

Operating agreement

For an LLC, the operating agreement can establish rules concerning ownership, management, voting, transfers, and other internal matters. Florida law gives operating agreements an important role in governing the company’s affairs.

Shareholder agreement

Corporations may use shareholder agreements to establish rules concerning ownership and the relationship among shareholders.

Buy-sell agreement

This can establish what happens when an owner dies, becomes disabled, retires, or experiences another specified triggering event.

Will

A will can address assets that pass through the estate, including business interests that are part of the probate estate.

Trust

A trust may hold business interests and establish rules for their administration and eventual distribution.

Durable power of attorney

A properly drafted durable power of attorney can address authority during incapacity, subject to the powers actually granted in the document.

These documents should be coordinated.

A business succession plan can become surprisingly fragile when the operating agreement says one thing, the buy-sell agreement says another, and the estate plan was drafted years earlier without considering the company.


What If the Business Has Multiple Owners?

Multiple-owner businesses need succession planning even when everyone is getting along.

Especially when everyone is getting along.

The difficult provisions are often the ones people are least interested in discussing when the company is doing well.

  • What happens if one owner dies?
  • What if an owner’s spouse inherits the interest?
  • What if one owner wants out?
  • What if an owner becomes unable to work?
  • What if two owners disagree about selling the company?
  • What if the business becomes significantly more valuable?

These are business questions, but they also become estate-planning questions when ownership changes because of death or incapacity.


Stuart Reinfeld puts it this way:

“Most business partnerships start with optimism. The operating agreement is where you discuss what happens when optimism takes a day off.”

That conversation can be uncomfortable. It is also considerably easier to have while everyone is alive, healthy, and still speaking to one another.


How Do You Plan for Business Succession in Florida?

Start by identifying the business interest itself.

Is the company an LLC, corporation, partnership, or another structure? Who owns it? Who manages it? What does the governing agreement say about transfers and management?

Then consider the two events that tend to create the biggest disruption: death and incapacity.

For death, determine how ownership should transfer and whether the remaining owners should have a purchase right or obligation.

For incapacity, determine who can exercise the necessary authority while the owner is alive.

Then coordinate those decisions with the owner’s estate plan.

The goal is not necessarily to create a complicated stack of documents. It is to make sure the documents already governing the business and the documents governing the owner’s estate do not contradict one another.

South Florida business attorney discussing ownership and management succession with business partners

Business Succession Planning in Coral Springs and Broward County

For business owners in Coral Springs, succession planning can involve both business law and estate planning.

A company may have an operating agreement, shareholder agreement, employment arrangements, commercial contracts, and financial obligations. The owner may separately have a will, trust, power of attorney, and other estate-planning documents.

Those pieces should be reviewed together when ownership of the business represents a significant part of the owner’s estate.

The same considerations apply throughout Broward County and South Florida.

A succession plan drafted when a company has two owners and $200,000 in annual revenue may need substantial revision after the company has ten employees, several million dollars in revenue, and three generations of family members involved.


Frequently Asked Questions

What happens to my LLC if I die in Florida?

  • The result depends on the LLC’s operating agreement, ownership structure, and applicable Florida law. Death can cause an individual member to dissociate, while the economic interest and management rights associated with the business interest can be treated differently.

Can my children inherit my business?

  • They may inherit a business interest depending on the business structure, estate plan, governing agreements, and applicable law. Inheriting an ownership interest does not necessarily mean inheriting the right to manage the company.

Does a will determine who runs my business?

  • Not necessarily. A will can address ownership passing through the estate, but management may be governed by the company’s operating agreement, corporate documents, or other applicable rules.

Can a trust own my LLC interest?

  • A trust can hold certain business interests, but the trust terms and the company’s governing documents need to be considered together.

What happens to my business if I become incapacitated?

  • The answer depends on the business structure and the authority available to someone else to act for you. A properly drafted durable power of attorney can provide authority that continues despite later incapacity, subject to its terms and Florida law.

Do I need a buy-sell agreement if I have business partners?

  • It can be useful when the owners need predetermined rules for what happens after death, disability, retirement, or another triggering event. Whether one is appropriate depends on the business and the owners’ objectives.

Planning for the Future of a Florida Business

A business succession plan answers a very practical question:

What happens to the company when the person who currently controls it cannot continue doing so?

For some owners, the answer may involve an operating agreement. For others, it may require a buy-sell agreement, trust, durable power of attorney, revised estate plan, or several documents working together.

The important part is making those decisions while the owner can still make them.

Reinfeld & Cabrera P.A. assists business owners in Coral Springs, Broward County, and throughout South Florida with business planning, estate planning, and legal matters involving ownership and succession. Contact the firm to discuss how your business interests fit into your broader estate and succession plan.

This article provides general information about Florida law and is not a substitute for legal advice concerning a particular business or estate.

Avoiding Probate in Florida: Estate Planning Mistakes to Watch For

Estate planning attorney reviewing probate avoidance options with a client in Coral Springs, Florida

Can avoiding probate create problems?

Yes. An estate plan can keep an asset out of probate while creating a different problem involving ownership, inheritance, control, or family disputes.

Joint accounts, beneficiary designations, trusts, and survivorship ownership can all be useful estate-planning tools. Problems arise when one of those arrangements is created without considering how it fits with the rest of the estate plan.

A person may add a child to a bank account because the child will receive it automatically at death. Someone else may name a beneficiary on a retirement account and never update it. A homeowner may add a child to a deed to make a future transfer easier.

Each decision can accomplish its immediate purpose. It can also produce an unintended result elsewhere.


When Probate Avoidance Changes the Intended Inheritance

The central problem is coordination.

Suppose a parent wants three children to inherit equally. The will reflects that intention, but one child is the beneficiary of a bank account, another is the beneficiary of a life insurance policy, and the house is jointly owned with the third.

The probate estate may then tell only part of the story.

Florida recognizes numerous arrangements that allow assets to pass outside probate. Some nonprobate assets can nevertheless remain relevant for other estate-planning purposes. For example, Florida’s elective-share statute includes certain payable-on-death, transfer-on-death, in-trust-for, and survivorship accounts when calculating a surviving spouse’s elective estate.

Avoiding probate and determining who should ultimately receive an estate are therefore separate questions.


Can Adding Someone to a Bank Account Cause an Inheritance Problem?

It can.

Adding a child or other person to an account may be intended to provide convenience during the owner’s lifetime or allow the account to pass automatically at death.

But joint ownership can affect both control and inheritance.

The Florida Bar warns that joint ownership can produce unintended consequences involving creditor exposure, unequal treatment of heirs, estate expenses, and other issues.

For example, a parent might add one child to an account because that child helps manage the parent’s finances. If the account carries survivorship rights, the arrangement may also determine who receives the money when the parent dies.

That result may be completely different from an intention to divide the estate equally among several children.


Can a Beneficiary Designation Conflict With a Will?

Yes.

A beneficiary designation can determine who receives certain assets without the asset passing through probate.

That can be useful until an old designation conflicts with a later estate plan.

Suppose someone signs a new will leaving the estate equally to two children. A retirement account still names one child as the sole beneficiary.

The new will does not necessarily change that beneficiary designation.

Beneficiary designations should therefore be reviewed whenever the overall estate plan changes and after major life events such as marriage, divorce, or the death of a beneficiary.


What If I Create a Trust but Forget to Transfer an Asset?

A trust document does not automatically place every asset into the trust.

If someone creates a revocable trust intending for it to hold an investment account, but the account remains solely in that person’s individual name, the trust may not control the account simply because the trust document says it should.

The same issue can arise with real estate, business interests, and other significant property.

The planning documents and ownership records need to match.


Can Putting a Child on Your House Cause Problems?

It can.

Adding a child to real estate can affect ownership and control during the parent’s lifetime as well as what happens after death.

The parent may have intended to make the eventual transfer easier. Instead, the arrangement can create a co-ownership relationship that affects decisions about selling, refinancing, or managing the property.

Florida homestead adds another layer of rules. Florida law places restrictions on the devise of homestead when a surviving spouse or minor child is involved, and separate provisions address certain lifetime transfers.

An ownership change intended to avoid probate therefore needs to be considered under the homestead rules as well.

Broward County estate planning attorney reviewing conflicting beneficiary and ownership arrangements

What Happens When Estate Documents Disagree?

Consider a simple example:

  • The will divides the estate equally among three children.
  • A bank account names Child A as beneficiary.
  • A life insurance policy names Child B.
  • The house is jointly owned with Child C.
  • A trust was created to hold the house, but the deed was never transferred to the trust.

There is no single document explaining the entire estate.

Each asset may have its own transfer mechanism. The family may then have to determine which arrangement controls each asset and whether any of them create additional legal rights.

The underlying problem is coordination.


Should Every Asset Be Arranged to Avoid Probate?

No.

Some assets may appropriately pass through probate. Others may be better handled through a trust, beneficiary designation, survivorship arrangement, or another structure.

The useful planning exercise is to identify the major assets, determine how each is currently owned, and ask how each will pass at death.

Then compare that result with the intended distribution.

That review can reveal inconsistencies before they become disputes.


Avoiding Probate in Coral Springs and Broward County

For families in Coral Springs and Broward County, these issues can arise when an estate includes a Florida homestead, investment accounts, business interests, jointly owned property, or multiple beneficiaries.

They can also arise when someone moves to Florida with estate documents and account arrangements created years earlier in another state.

A will, trust, beneficiary designation, deed, and account title can each serve a legitimate purpose. Problems arise when they produce different results.


Frequently Asked Questions

Can avoiding probate cause problems?

  • Yes. Probate avoidance can create unintended ownership, inheritance, control, or family issues if the arrangement is inconsistent with the rest of the estate plan.

Can adding someone to my bank account change who inherits the money?

  • Yes. Depending on the account’s ownership and survivorship terms, adding another person can affect who receives the account at death.

Could a beneficiary designation conflict with my will?

  • Yes. Certain beneficiary designations control the transfer of assets outside probate and may produce a different result from a later will.

Can I create a trust but still have assets go through probate?

  • Yes. An asset that remains outside the trust and is otherwise a probate asset may still require probate administration.

Can putting my child on my house cause problems?

  • Yes. Adding a child as an owner can affect control and ownership during life, while Florida homestead law imposes additional rules on certain transfers and inheritance.

Should every asset be arranged to avoid probate?

  • No. The appropriate treatment depends on the asset, the owner’s objectives, family circumstances, and applicable Florida law.

When Probate Avoidance Becomes an Estate-Planning Problem

Keeping an asset out of probate can be useful. It can also change who owns it, who controls it, and who receives it.

The important question is whether the way an asset avoids probate produces the result the owner actually intended.

Reinfeld & Cabrera P.A. assists clients in Coral Springs, Broward County, and throughout South Florida with estate planning, trusts, probate, and related matters. If you are considering changing ownership, adding beneficiaries, creating a trust, or restructuring your estate to avoid probate, the firm can review the arrangement alongside the rest of your estate plan.

This article provides general information about Florida law and is not a substitute for legal advice concerning a particular estate.

When Does a Landlord Have to Return a Security Deposit in Florida?


How Long Does a Landlord Have to Return a Security Deposit?

Florida Statute §83.49 creates two different timelines.

If the landlord is not making a claim against the security deposit, the deposit must be returned within 15 days after the tenancy ends.

If the landlord intends to keep some or all the deposit, the landlord has 30 days to notify the tenant. He provides a copy in writing of the intention to impose a claim and the reason for it. The notice must be sent as required by the statute. This by certified mail to the tenant’s last known mailing address or, when the parties have properly agreed to electronic notices, by email.

That difference is important. The 15-day rule is about returning a deposit when there is no claim. The 30-day rule gives the landlord time to notify the former tenant about a claim against the deposit.


What If the Landlord Wants to Keep Part of the Deposit?

A landlord cannot simply decide that the security deposit has become a convenient repair fund.

When a landlord intends to impose a claim, the required notice must state the amount claimed. It should also state the reason for the claim. The tenant then has 15 days after receiving the notice to object in writing.

If the tenant does not object within that period, things change. The landlord may deduct the claim and must send the remaining balance within the time required by the statute.

A late objection does not necessarily eliminate every possible legal claim by the tenant. Florida law says that failing to object within the 15-day period doesn’t waive the right to seek damages.


What Can a Landlord Deduct From a Security Deposit in Florida?

A security deposit exists to secure the tenant’s obligations under the rental agreement. A dispute can arise over unpaid rent, damage to the property, or other amounts the landlord claims are owed under the lease.

The recurring fight, however, is usually about damage versus ordinary wear and tear.

A tenant who has lived in an apartment for several years shouldn’t expect it to look as it did on move-in day. Normal deterioration is different from a broken fixture, a damaged door, or other physical damage caused during the tenancy.

The lease, the property’s condition, and the evidence surrounding the claimed damage all matter.

For that reason, both sides should preserve useful records:

  • The lease and any amendments
  • Move-in and move-out photographs
  • Inspection reports
  • Messages about repairs
  • Photographs of claimed damage
  • Repair invoices or estimates
  • Proof of rent payments
  • The tenant’s forwarding address
  • The landlord’s deposit correspondence

A photograph taken on moving day can be considerably more useful than an argument six months later about what the carpet looked like.


What Happens If the Landlord Misses the 30-Day Deadline?

This is one of the most important Florida security deposit rules.

If a landlord fails to give the required notice within the 30-day period, the landlord forfeits the right to impose a claim against the security deposit. The statute still allows the landlord to bring an action for damages after returning the deposit.

That does not mean every late notice automatically ends every dispute between the parties. It means the landlord cannot use the security deposit itself as a setoff after missing the statutory notice deadline.

For a tenant who has been waiting for a deposit, the date the tenancy ended and the date the landlord sent the notice can therefore become important evidence.


What If the Tenant Disagrees With the Deduction?

A tenant who receives a claim against the deposit has 15 days after receiving the notice to object in writing.

The objection should address the actual dispute. If the landlord claims $2,000 for repairs and the tenant believes the property suffered ordinary wear and tear, thing vary. The tenant can explain that disagreement and preserve the relevant evidence.

Photographs, inspection records, repair communications, and the condition of the property at move-in can all become useful.

If the dispute cannot be resolved, either party can bring an action to determine who is entitled to the security deposit. Florida law provides that the prevailing party is entitled to court costs and a reasonable attorney fee in an action concerning the deposit.

That can make the size and strength of the claim relevant when deciding how to proceed.


Does a Florida Security Deposit Earn Interest?

It can.

Florida law allows a landlord to hold a security deposit in a separate non-interest-bearing account, a separate interest-bearing account, or under certain circumstances through a surety bond.

When the deposit is held in an interest-bearing account, the tenant must receive interest calculated under the formula in §83.49. The statute also provides a 5% simple-interest requirement when the landlord uses the specified surety-bond option.

The landlord must also give the tenant written information about how the deposit is being held and whether the tenant is entitled to interest, subject to the statutory exceptions.


What If I Paid a Fee Instead of a Security Deposit?

Florida law now recognizes a separate arrangement in which a landlord may offer a tenant the option to pay a fee in lieu of a security deposit.

That fee is legally different from a traditional security deposit. The arrangement has its own disclosure requirements and rules concerning claims for unpaid rent, fees, and property damage. The statute applies to rental agreements entered into or renewed on or after July 1, 2023.

So if the money paid at the beginning of the tenancy was called a “deposit waiver fee,” “deposit alternative,” or something similar, the first step is to determine what agreement the tenant actually signed.

The ordinary security-deposit rules should not automatically be applied to a different arrangement.


What If the Tenant Never Gave a Forwarding Address?

Give the landlord one.

Florida’s statutory security-deposit notice specifically tells tenants to provide a new address after moving out so the landlord can send notices concerning the deposit. Section 83.49 also contains separate rules concerning a tenant who vacates or abandons a property without giving the required notice.

A forwarding address also removes one very unnecessary source of confusion.

If there is a dispute over the deposit, keep proof that the new address was provided and keep copies of the communication.


Security Deposit Disputes in Coral Springs and Broward County

A security deposit dispute in Coral Springs is governed primarily by Florida’s statewide landlord-tenant law. Florida expressly preempts local regulation of matters covered by Part II of Chapter 83, including security deposits and landlord-tenant notice requirements.

The same statutory framework applies across Broward County and South Florida, whether the rental property is in Coral Springs, Tamarac, Fort Lauderdale, Parkland, or another community.

The facts of the dispute will still be local: the rental property, the lease, the inspection records, the communications between the parties, and the evidence supporting the claimed deduction.


Landlord or tenant? Get the deposit dispute reviewed before it gets bigger.

If you are a tenant and your security deposit was withheld, bring the lease, the landlord’s notice, photographs, and your move-out records to an attorney who can evaluate whether the deduction and notice complied with Florida law.

If you are a landlord, have the lease, deposit records, photographs, invoices, and notice reviewed before assuming a deduction is enforceable. A mistake in the notice or timing can affect your ability to claim against the deposit.

Reinfeld & Cabrera, P.A. represents both landlords and tenants in South Florida landlord-tenant disputes, including security deposit claims. Contact the firm in Coral Springs to discuss the circumstances, review the relevant documents, and determine what legal options may be available.


Frequently Asked Questions

How long does a landlord have to return a security deposit in Florida?

  • Generally, 15 days after the tenancy ends if the landlord does not intend to make a claim against the deposit. If the landlord intends to make a claim, the landlord generally has 30 days to provide the required notice.

Can a landlord keep a security deposit for damages in Florida?

  • A landlord may have a claim against a security deposit for amounts the tenant owes under the rental agreement, including qualifying damage. The landlord must follow Florida’s statutory notice procedure when making a claim.

What is the 30-day rule for security deposits in Florida?

  • If a landlord intends to impose a claim against the security deposit, the landlord generally must give the tenant written notice of the claim and its reason within 30 days after the tenancy ends.

How long does a tenant have to dispute a security deposit deduction in Florida?

  • A tenant generally has 15 days after receiving the landlord’s claim notice to object in writing.

What happens if a landlord does not return a security deposit in Florida?

  • The answer depends on whether the landlord made a claim and whether the required statutory notices were provided on time. A landlord who misses the 30-day claim-notice deadline forfeits the right to impose a claim against the deposit itself, although the statute allows a later action for damages after the deposit is returned.

This article provides general information about Florida landlord-tenant law and security deposits. It is not legal advice for a particular landlord or tenant, and the outcome of a dispute depends on the lease, the facts, and the applicable law.

Florida Property Deeds & Titling: Choosing the Right Ownership Structure to Avoid Probate

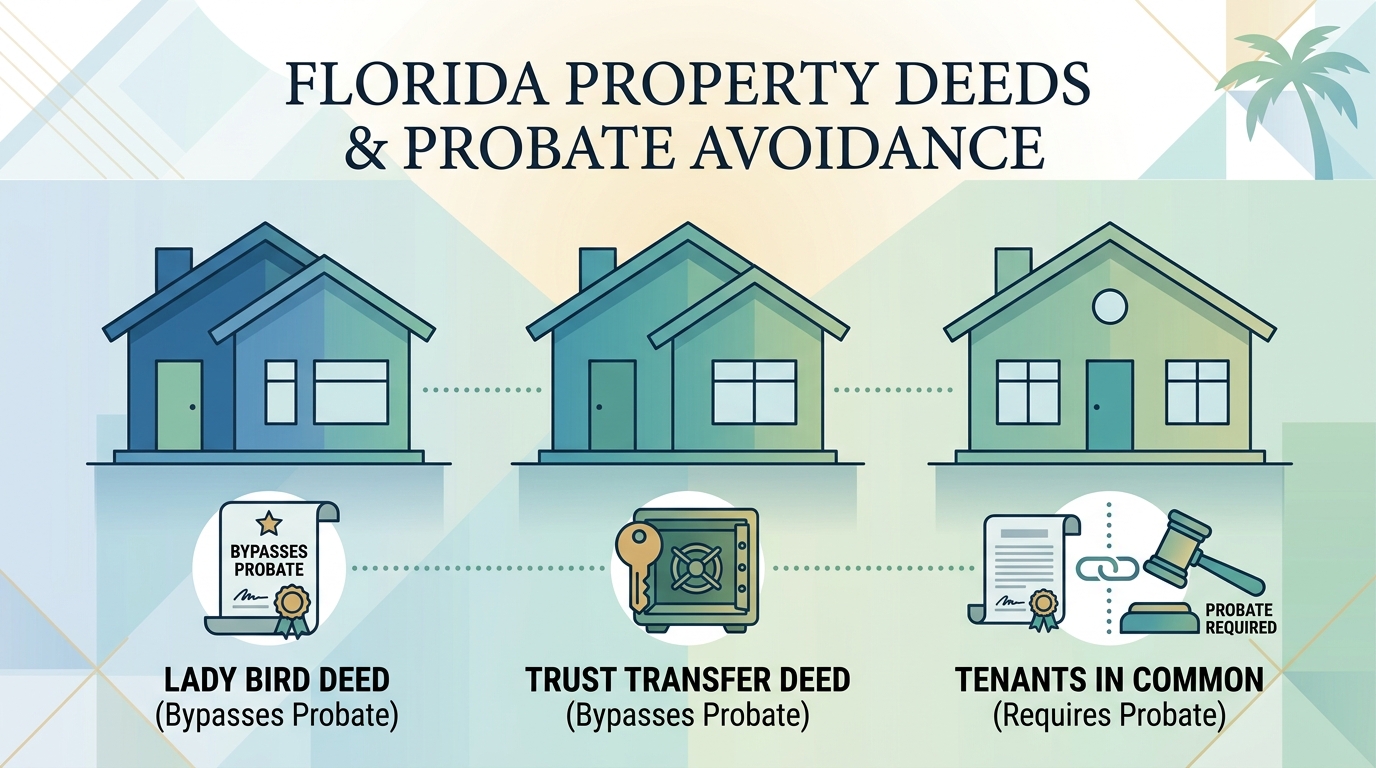
An illustrative visual guide comparing Florida property deeds including Lady Bird Deeds, Quitclaim Deeds, and Trust Transfer Deeds for probate avoidance.

The primary property deeds used in Florida estate planning are Warranty Deeds, Quitclaim Deeds, and Enhanced Life Estate Deeds (commonly called Lady Bird Deeds).

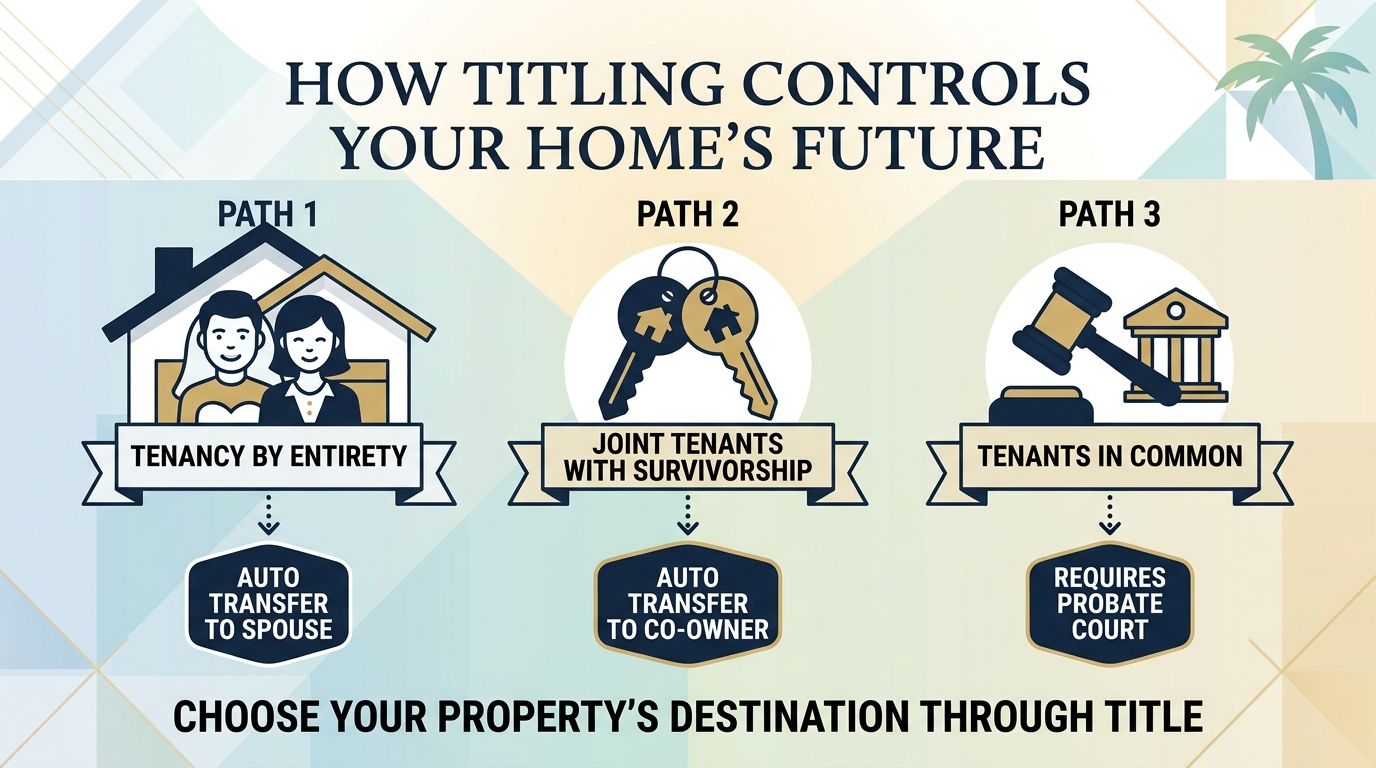
While a deed physically transfers legal title to real estate, the way ownership is titled determines a lot. For example – whether your home must pass through Broward County probate court or transfer automatically to your loved ones upon your death. Understanding the distinction between legal deeds and property titling structures is one of the most effective ways to protect real estate assets, minimize tax exposure, and prevent costly judicial delays for Florida families.


Deeds vs. Titling: Understanding the Fundamental Difference

To build an effective estate plan, it is critical to separate the transfer instrument from the form of ownership:

  • The Deed (The Vehicle): The legal document signed, executed, and recorded in the county public records to transfer real estate ownership from a grantor to a grantee.
  • The Titling / Ownership Form (The Rules): The specific statutory language. Written directly into the deed that dictates who holds ownership rights today. For example how liabilities are shared, and what happens to the property when an owner passes away.

Even a perfectly drafted Warranty Deed will fail to keep your home out of probate court if the underlying titling structure is misconfigured under Florida real estate law.


Comprehensive Comparison: Florida Property Deeds & Estate Planning Tools

Different real estate deeds serve distinct legal purposes during property transfers and estate planning:

Deed / Structure TypeProbate Avoidance?Owner Retains Lifetime Control?Primary Estate Planning & Legal Use Case
Lady Bird Deed (Enhanced Life Estate)YesYes (Can sell, mortgage, or revoke without consent)Passing a Florida primary homestead directly to named beneficiaries outside probate without sacrificing Medicaid eligibility or lifetime control.
Traditional Life Estate DeedYesNo (Requires remainder beneficiary consent to sell or refinance)Transferring property with irrevocable remainder rights. Rarely used in modern estate planning due to loss of owner flexibility.
Trust Transfer DeedYesYes (Managed seamlessly via Trustee)Conveying real estate into a Revocable Living Trust to coordinate complex, multi-property, or multi-state real estate holdings.
Quitclaim DeedNo (Unless combined with joint titling)YesTransferring property without title warranties, commonly between family members, during divorce settlements, or to clear title defects.
General / Special Warranty DeedNo (Unless combined with joint titling)YesStandard commercial or residential real estate purchases where the grantor guarantees clear title free of encumbrances.

The Power of the Florida Lady Bird Deed (Enhanced Life Estate)

In South Florida, the Enhanced Life Estate Deed—popularly known as a Lady Bird Deed—is one of the most powerful probate-avoidance tools available to homeowners.

Unlike a traditional life estate deed, which restricts the primary owner from selling or mortgaging the home without written permission from the named beneficiaries, a Lady Bird Deed allows you to maintain total lifetime control over the property:

  • Full Unilateral Control: You reserve the right to sell, gift, lease, or mortgage the property during your lifetime. You do not need to notify or obtain consent from the named remainder beneficiaries.
  • Automatic Post-Death Transfer: Upon your passing, full legal ownership automatically transfers to your named beneficiaries. This is done by recording a certified death certificate in the Broward County public records, completely bypassing probate court.
  • Preservation of Homestead Protections: A Lady Bird Deed maintains your Florida Constitutional Homestead tax exemptions (including the Save Our Homes cap). And it also keeps the property protected from general judgment creditors.
  • Medicaid Eligibility Protection: Because reserving an enhanced life estate is not considered an immediate gift or transfer of asset value under current Florida Medicaid rules, it generally does not trigger Medicaid penalty periods.

How Property Titling Controls Probate Under Florida Law

When two or more individuals hold title to Florida real estate, the specific legal language on the recorded deed dictates how ownership passes upon death:

                                 FLORIDA PROPERTY TITLING
                                            │
               ┌────────────────────────────┼────────────────────────────┐
               ▼                            ▼                            ▼
      Tenants in Common         Joint Tenants w/ Survivorship    Tenancy by the Entirety
   (Default for Unmarried)           (Unmarried Co-Owners)             (Married Couples)
               │                            │                            │
               ▼                            ▼                            ▼
       Requires Probate            Bypasses Probate             Bypasses Probate
  (Passes to Deceased's Estate)    (Passes to Surviving Owner)  (Passes to Surviving Spouse)

1. Tenancy by the Entirety (Married Couples)

Under Florida law (F.S. § 689.115), real property jointly acquired by a married couple is legally presumed to be held as Tenancy by the Entirety. Each spouse owns an undivided 100% interest in the entire property. Upon the death of one spouse, full title automatically vests in the surviving spouse outside of probate. Additionally, this form of titling provides strong creditor protection against debt obligations incurred by only one spouse.

2. Joint Tenants with Right of Survivorship (JTWROS)

Frequently used by unmarried co-owners, adult siblings, or parents and children, Joint Tenants with Right of Survivorship explicitly mandates that when one joint owner dies, their ownership share automatically absorbs into the surviving owner’s share. This transfer occurs outside of probate court. However, adding non-spouse co-owners exposes the property to the joint owner’s personal financial liabilities, tax liens, or lawsuits.

3. Tenants in Common (TIC)

Tenants in Common is the default legal ownership structure for unmarried co-owners in Florida unless the deed explicitly specifies otherwise. Each co-owner holds a distinct, separate fractional percentage of the property. When a Tenant in Common dies, their ownership percentage does NOT pass to the surviving co-owner—it becomes part of the deceased person’s probate estate and must be distributed through court according to their Will or Florida’s intestate laws.


Pitfalls of DIY Deed Transfers & Co-Ownership

While deeding real estate directly to family members may seem like a quick alternative to formal estate planning, self-drafted quitclaim deeds frequently cause severe financial and legal consequences:

  1. Title Defects & Clouded Titles: Missing marital status disclosures, incorrect legal descriptions, or improper witness attestations can cloud the title, preventing future sales or requiring costly quiet title lawsuits.
  2. Unintended Tax Consequences: Gifting real estate during your lifetime through a standard quitclaim deed causes the beneficiary to inherit your original tax cost basis. Conversely, inheriting property upon death via a Lady Bird Deed or Trust provides a step-up in cost basis, drastically reducing capital gains taxes when sold.
  3. Creditor & Divorce Exposure: Adding an adult child to your deed gives their creditors, judgment holders, or divorcing spouse a legal claim against your home.
An infographic diagram explaining how property titling structures like Joint Tenants with Right of Survivorship and Tenancy by the Entirety impact probate under Florida law.

Don’t Let an Outdated Deed Dictate Your Family’s Future

A single unreviewed property deed can trigger months of unexpected probate court proceedings, cloud your title, or expose your home to unnecessary tax liabilities. Whether you need to draft an Enhanced Life Estate (Lady Bird) Deed, transfer real estate into a Revocable Living Trust, or audit an existing deed after marriage or divorce, taking action now prevents costly legal disputes later.

Schedule a Property Deed & Titling Audit

Ensure your real estate title is structured to pass seamlessly outside of probate court. Contact Reinfeld Cabrera PA today to review your property deeds with our South Florida legal team.

  • Coral Springs Office: 9625 W. Sample Rd, Coral Springs, FL 33065
  • Direct Line: (954) 866-4878 | Toll-Free: 954-866-HURT
  • Local Practice Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and Broward County

Frequently Asked Questions

What is a Florida Lady Bird Deed, and why is it popular in estate planning?

  • An Enhanced Life Estate Deed (Lady Bird Deed) allows a property owner to retain full lifetime control over their property—including the right to sell, mortgage, or revoke the deed—while naming a beneficiary who automatically inherits the real estate upon the owner’s death without probate court involvement.

Does adding my adult child to my deed avoid probate in Florida?

  • Adding an adult child as a Joint Tenant with Right of Survivorship can avoid probate, but it carries significant risk. It subjects your primary residence to your child’s creditors, financial judgments, bankruptcy proceedings, or marital disputes during your lifetime. Utilizing a Revocable Living Trust or Lady Bird Deed is generally a far safer legal alternative.

Do I need to update my deed after getting married or divorced?

  • Yes. Under Florida law, a final decree of divorce automatically converts property held as Tenancy by the Entirety into a Tenants in Common arrangement. Without an updated deed or property settlement agreement, your ex-spouse’s share will no longer pass automatically to you upon death, requiring court probate to settle.

Can I transfer Florida homestead property into a Revocable Living Trust?

  • Yes. Florida homestead real estate can be transferred into a properly drafted Revocable Living Trust without losing homestead tax exemptions or Save Our Homes caps, provided the trust agreement preserves your legal right to reside on the property during your lifetime.

What is the difference between a Quitclaim Deed and a Warranty Deed in Florida?

  • A Warranty Deed provides formal legal guarantees that the grantor holds clear, marketable title free of undisclosed liens or encumbrances. A Quitclaim Deed simply transfers whatever ownership interest the grantor currently holds without any guarantees regarding title quality.

Florida Probate: Summary Administration vs. Formal Administration Explained

An infographic comparing Florida Summary Administration and Formal Administration eligibility rules, $150,000 asset limits, and court timelines under Florida probate law.

In Florida, court-supervised probate is divided into two primary procedures: Summary Administration (an expedited process for smaller or older estates) and Formal Administration (the traditional, fully supervised court process).

Whether an estate qualifies for Summary Administration depends on the total net value of non-exempt probate assets, whether the decedent has been deceased for over two years, and the complexity of outstanding creditor claims under Florida probate law (Fla. Stat. § 735.201). Understanding how these two probate paths function ensures that South Florida beneficiaries receive their inheritance as quickly and cost-effectively as possible.


Summary vs. Formal Administration at a Glance

Qualification & Process FeatureSummary Administration (Fla. Stat. § 735.201)Formal Administration (Florida Probate Rules)
Estate Value ThresholdNon-exempt probate assets are $150,000 or less (for deaths on/after July 1, 2026), OR the decedent has been deceased for over 2 years.Required for estates exceeding $150,000 in non-exempt probate assets (if death occurred within 2 years).
Personal RepresentativeNot appointed. No Letters of Administration are issued by the court.Required. Court officially appoints a Personal Representative (Executor) with fiduciary authority.
Average Timeline4 to 8 weeks (subject to Broward County court docket schedules).6 to 12+ months (includes mandatory 90-day newspaper creditor notice period).
Creditor Claims ProcessCreditors must be resolved or served prior to distribution; or barred if death occurred over 2 years ago.Formal 3-month Notice to Creditors published in local media to legally bar future claims.
Primary Judicial OrderOrder Summary Administration directly transfers legal title of assets to beneficiaries.Letters of Administration issued at inception; Order of Discharge issued at estate closing.

When Does Summary Administration Apply in Florida?

Summary Administration is an expedited judicial procedure designed to transfer title to beneficiaries without opening a full probate estate. However – to qualify under Florida law, the estate must satisfy one of two statutory criteria:

  1. The $150,000 Net Asset Test: Effective July 1, 2026, Florida increased the summary administration statutory limit. The total value of all assets subject to probate—excluding protected Florida Constitutional Homestead real estate and statutory exempt personal property—does not exceed $150,000 (for deaths on or after July 1, 2026; $75,000 for deaths prior to July 1, 2026).
  2. The Two-Year Rule: The decedent has been deceased for more than two years, regardless of the overall financial value of the estate. Under Fla. Stat. § 733.710, two years establishes a non-claim statute of repose that automatically bars unfiled creditor claims.

Key Distinction: No Personal Representative Appointed

In Summary Administration, the court does not appoint a Personal Representative and does not issue Letters of Administration. Instead, a petition is submitted asking the judge to issue a direct order transferring specific assets (such as a bank account or vehicle) directly to named beneficiaries.

If an estate requires active ongoing legal authority—such as accessing restricted medical records, pursuing a wrongful death lawsuit, or negotiating complex business debts—Formal Administration must be opened regardless of total asset value.


When Is Formal Administration Mandatory?

Formal Administration is the comprehensive, fully supervised probate process in Florida. It is mandatory when:

  • Non-exempt probate assets exceed $150,000 and the decedent passed away within the last two years.
  • The decedent’s Last Will and Testament explicitly mandates formal probate administration.
  • The estate involves disputed creditor claims, contested wills, or missing heirs.
  • Real estate must be actively listed, marketed, and sold during probate, requiring an appointed Personal Representative to sign legal contracts and closing documents.

                           FLORIDA PROBATE DECISION PATH
                                         │
                    Is the non-exempt probate value under $150k
                    OR has the decedent been deceased > 2 years?
                                         │
                   ┌─────────────────────┴─────────────────────┐
                   ▼                                           ▼
                 YES                                           NO
                   │                                           │
         Are there complex debts,                              │
        disputes, or land sales                                │
         requiring an Executor?                                │
           ┌───────┴───────┐                                   │
           ▼               ▼                                   ▼
          YES              NO                        FORMAL ADMINISTRATION
           │               │                        (Full Court Process,
           │               ▼                        Personal Rep Appointed,
           │     SUMMARY ADMINISTRATION             6-12 Month Duration)
           │    (Expedited, 4-8 Weeks,
           │    Order Directly Transfers)
           └───────────────────────────────────────────────────┘

What About Very Small Estates? (Disposition Without Administration)

For extremely modest estates where the decedent left no real estate, Florida offers an informal non-probate process under Fla. Stat. § 735.301 known as Disposition of Personal Property Without Administration.

This simplified filing is available only when remaining non-exempt personal property does not exceed the total sum of preferred funeral expenses and necessary medical bills incurred during the last 60 days of the decedent’s final illness.


Strategic Risk Factors: Creditor Exposure & Multi-State Assets

Selecting between Summary and Formal Administration involves critical legal trade-offs beyond estate size:

1. The Post-Probate Creditor Exposure Risk

Under Fla. Stat. § 735.206, Summary Administration directly distributes assets to beneficiaries without opening a mandatory 90-day newspaper creditor publication window.

If a petition is filed before the two-year non-claim period expires (Fla. Stat. § 733.710), beneficiaries remain personally liable to valid estate creditors up to the full value of the property received. If unknown debts emerge post-distribution, Formal Administration is often safer because publishing a statutory Notice to Creditors permanently cuts off future claims after 90 days.


┌─────────────────────────────────────────────────────────────────────────┐
│                    CREDITOR PROTECTION COMPARISON                       │
├───────────────────────────────────┬─────────────────────────────────────┤
│      SUMMARY ADMINISTRATION       │        FORMAL ADMINISTRATION        │
├───────────────────────────────────┼─────────────────────────────────────┤
│ • No mandatory newspaper notice   │ • Formal 90-day Notice published    │
│ • Beneficiaries personally liable │ • Unfiled claims permanently barred │
│   to creditors (up to asset value)│ • Clean liability shield for heirs  │
│ • Exposure lasts up to 2 years    │ • Full judicial closure of claims   │
└───────────────────────────────────┴─────────────────────────────────────┘
A flowchart diagram illustrating how to determine whether a Florida estate qualifies for Summary Administration or requires Formal Administration.

2. Ancillary Administration for Out-of-State Residents

When a non-Florida resident dies owning real estate in Broward County or anywhere in South Florida, the home cannot be transferred by an out-of-state court order. An Ancillary Probate proceeding (Fla. Stat. § 734.102) must be opened in Florida. Depending on the non-exempt Florida land value, Ancillary proceedings can be conducted as either Summary or Formal Administration.


Frequently Asked Questions

Does Florida Homestead Property count toward the $150,000 Summary Administration limit?

  • No. Protected Florida Constitutional Homestead property passes outside the general claims of creditors and is excluded when calculating the $150,000 threshold for Summary Administration, provided a formal Petition to Determine Homestead Status is filed alongside the summary petition.

What is the 10-day Will Deposit Rule in Florida?

  • Under Fla. Stat. § 732.901, whoever holds the decedent’s original Last Will and Testament must deposit it with the Clerk of the Circuit Court in the county where the decedent resided within 10 days of receiving notice of death, regardless of whether formal probate will be opened.

What is the current Florida Summary Administration asset threshold?

  • Effective July 1, 2026 (Fla. Stat. § 735.201), the Florida Legislature increased the non-exempt probate asset threshold for Summary Administration from $75,000 to $150,000 for deaths occurring on or after July 1, 2026 (or where the decedent has been deceased for more than 2 years). Protected homestead property continues to be excluded from this calculation.

How long does Formal Administration take in Broward County?

  • A routine, uncontested Formal Administration in Broward County typically takes between 6 and 12 months. This timeframe accommodates publishing the mandatory Notice to Creditors, observing the 90-day statutory creditor claim window, marshaling asset inventories, preparing tax accountings, and securing final court discharge.

Can a summary administration be converted to a formal administration if a dispute arises?

  • Yes. If unexpected creditor claims emerge, beneficiaries dispute asset distribution, or unknown assets are uncovered that push the estate over $150,000, any interested party or petitioner can motion the court to convert the summary proceeding into a Formal Administration.

Do I need a probate attorney for Summary Administration in Broward County?

  • While Florida law technically permits self-representation in Summary Administration when no Personal Representative is appointed, court clerk offices cannot provide legal advice. Drafting accurate petitions, verifying homestead status, and coordinating creditor searches require specialized legal guidance to avoid judicial rejection.

Don’t Let an Outdated Deed Dictate Your Family’s Future

Choosing the correct probate pathway prevents costly administrative delays, court rejections, and personal liability for estate debts. Whether your family qualifies for an expedited Summary Administration or requires full Formal Administration in South Florida, taking action with experienced legal counsel guarantees that every asset is protected.

Schedule a Property Deed & Titling Audit

Ensure your real estate title and probate strategy are structured to pass seamlessly outside of or through probate court. Contact the attorneys at Reinfeld & Cabrera, P.A. today to review your estate and property deeds with our South Florida legal team.

  • Office Locations: Coral Springs | Fort Lauderdale | Plantation
  • Direct Telephone: (954) 334-1520
  • Email: Info@lawrct.com
  • Website: mypersonalattorneys.com
  • Local Practice Coverage: Coral Springs, Fort Lauderdale, Tamarac, Plantation, and Broward County

When Does a Florida HOA or Condo Association Need a Lawyer?

Community association attorney reviewing HOA governing documents with board members in Coral Springs, Florida

A Florida homeowners association (HOA) or condominium association should consult a community association attorney when a legal question could affect its governing documents, board decisions, enforcement actions, or financial obligations. Early legal guidance can help the board understand its authority and avoid mistakes that lead to disputes or litigation.

A Florida community association should consider hiring an attorney when it needs to:

  • Interpret governing documents: Determine whether the declaration, bylaws, or community rules authorize a proposed action.
  • Enforce restrictions: Address violations consistently and assess the legal risks of disputes with residents.
  • Review contracts: Evaluate vendor agreements, construction contracts, or potential conflicts of interest.
  • Handle financial disputes: Address unpaid assessments, collection proceedings, or disagreements over association funds.
  • Respond to legal claims: Manage threatened lawsuits, formal demands, or allegations of improper board conduct.
  • Protect board decisions: Confirm that proposed actions comply with applicable Florida law and the association’s governing documents.

Florida law distinguishes between homeowners associations, generally governed by Chapter 720, and condominium associations, generally governed by Chapter 718. The rules applicable to a particular association depend on its legal structure and the issue involved.

For associations in Coral Springs and across Broward County, a community association attorney can assess the relevant documents, explain the board’s legal options, and help determine the appropriate response before a disagreement escalates.


What Does a Community Association Attorney Actually Do?

A community association attorney advises homeowners associations and condominium associations on their legal rights and responsibilities. The work may involve reviewing governing documents, assessing enforcement decisions, advising on proposed amendments, or representing the association in a dispute.

Florida law distinguishes between homeowners associations governed primarily by Chapter 720 of the Florida Statutes and condominium associations governed by Chapter 718. Although these organizations share some concerns, their legal obligations are not identical. The correct advice depends on the type of association and the documents that govern the particular community.

An attorney may help an association with:

  • Governing documents: Interpreting declarations, bylaws, and rules to determine whether a proposed board action is authorized.
  • Rule enforcement: Assessing whether an enforcement decision complies with applicable law and the association’s governing documents.
  • Contracts: Reviewing construction agreements or management contracts before the association commits substantial funds.
  • Assessments and collections: Advising on legally compliant procedures for collecting unpaid assessments.
  • Disputes: Representing the association in mediation, litigation, or other proceedings when appropriate.

These services are related, but they do not all require the same response. A routine maintenance question may be resolved through the management process. A proposed amendment that changes property rights presents a different legal problem.


When Should a Florida HOA Hire an Attorney?

There is no universal rule requiring an HOA to consult a lawyer before every board decision. The need for legal advice depends on the decision’s consequences and the applicable law. Several situations deserve particular attention.


1. When the board is unsure whether it has the authority to act

An association’s authority comes from applicable statutes and its governing documents. A board cannot necessarily create a new restriction simply because its members believe the restriction would benefit the community.

Consider an HOA in Coral Springs that wants to prohibit a particular type of exterior modification. The declaration contains architectural standards, but it does not clearly authorize the proposed prohibition. The board could adopt the rule and begin issuing violation notices, only to discover that its authority to impose the restriction is disputed.

An attorney can examine the declaration, applicable statutes, and relevant court decisions before the board commits to a potentially unenforceable policy.

This review is especially important when a proposed decision could affect owners’ property rights or require an amendment to recorded documents.


2. When an association plans to amend its governing documents

Amending an HOA declaration or condominium declaration is not simply a matter of changing a few sentences. The association may need to comply with specific voting requirements, notice procedures, approval thresholds, and recording requirements.

The Florida Supreme Court’s guidance on community association managers addresses this distinction. In The Florida Bar Re: Advisory Opinion—Activities of Community Association Managers, 681 So. 2d 1119 (Fla. 1996), as clarified in a 2015 opinion, the Court explained that certain tasks requiring legal interpretation or the preparation of documents affecting legal rights constitute the practice of law.

The Court-approved guidance states:

“Although CAMs may be able to draft the documents, they cannot advise the association as to the legal consequences of taking a certain course of action.”

Read the Florida Supreme Court’s 2015 opinion.

The distinction is practical. A community association manager may handle many administrative tasks, but deciding how a statute applies to a proposed amendment is a different responsibility.

An attorney can help determine which approvals are necessary before the association circulates a proposal or schedules a vote. That can prevent a costly do-over if the amendment process is defective.


3. When the board needs to enforce a community rule

Enforcement disputes can arise over architectural modifications, property maintenance, parking restrictions, or other community rules. Before taking action against an owner, the association should confirm that the restriction is legally valid and that its enforcement process is consistent with applicable requirements.

A rule that appears straightforward on paper can become complicated when the declaration is ambiguous or the association has treated similar violations differently.

In White Egret Condominium, Inc. v. Franklin, 379 So. 2d 346 (Fla. 1979), the Florida Supreme Court considered a condominium’s restriction on children under twelve. The Court concluded that the restriction could be enforceable if reasonably related to a lawful objective and applied reasonably. However, the association had applied the restriction arbitrarily and selectively in the circumstances before the Court.

Read the White Egret decision.

The lesson is not that every inconsistent enforcement decision invalidates a rule. Rather, the association’s authority and its actual enforcement practices can both matter.

Imagine that a board has permitted several homeowners to maintain similar exterior structures for years. It then threatens one owner with legal action over a comparable structure. The owner challenges the decision, arguing that the association has singled out the property.

The outcome would depend on the governing documents and the evidence. Legal advice can help the board determine whether it has a defensible basis for enforcement before the dispute escalates.


4. When an owner challenges assessments or requests association records

Disagreements over assessments and access to records can create legal problems if an association responds incorrectly. Florida statutes establish rules governing association records and the obligations of owners.

For homeowners associations, Section 720.303 addresses association powers, official records, meetings, and financial reporting. Condominium associations have separate requirements under Chapter 718, including Section 718.111.

An owner who questions an assessment does not automatically have the right to withhold payment. In Ocean Trail Unit Owners Association v. Mead, 650 So. 2d 4 (Fla. 1994), the Florida Supreme Court addressed the distinction between challenging association conduct and refusing to pay assessments to protect against a judgment lawfully entered against the association.

Read the Ocean Trail decision.

The same need for care applies to records requests. An association should identify which documents must be made available under the applicable statute and respond within the required time. If a request involves disputed records or potentially privileged communications, the board should obtain appropriate guidance rather than assume that every document is either public or confidential.


5. When a contract or potential conflict of interest raises concerns

An HOA or condominium association may enter contracts for maintenance, construction, management, and other services. The board should understand the association’s obligations before approving an agreement that could affect its finances for years.

Suppose a director recommends a contractor who is a close relative. The proposed price appears reasonable, and the board wants to approve the contract quickly.

The association should determine whether disclosure or other conflict-of-interest procedures apply. Florida’s condominium statute, Section 718.3027, addresses certain transactions involving conflicts of interest. The applicable requirements depend on the type of association and the circumstances.

An attorney can help the board assess the proposed transaction before it commits association funds. This is not an accusation of wrongdoing whenever a director knows a contractor. It is a way to identify the applicable rules and protect the integrity of the decision.


HOA governing documents, meeting minutes, and contracts prepared for an attorney review in Broward County, Florida.

Who Does an HOA Attorney Represent?

An HOA attorney generally represents the association as a legal entity. The attorney’s client is not automatically every homeowner, every member of the board, or the property manager.

This distinction becomes particularly important when an individual director’s interests diverge from those of the association.

For example, an owner may accuse a director of misconduct and demand that the association investigate. The association’s attorney may need to advise the association about its obligations and response. If the director faces personal allegations, that director may need independent legal representation.

The same principle applies when homeowners disagree with a board decision. The association’s attorney is not automatically their personal attorney, even though the decision affects their homes.

An owner who believes the board has violated the governing documents may need independent legal advice about the owner’s own rights and available remedies.


Can an HOA Manager Provide Legal Advice?

Community association managers perform valuable administrative and operational work. They may coordinate maintenance, prepare budgets, assist with meetings, and help the board carry out its responsibilities. Florida law nevertheless draws a boundary between management functions and activities that constitute the practice of law.

The Florida Supreme Court’s advisory opinion identifies legal tasks that may require an attorney, including certain interpretations of statutes and governing documents. It also distinguishes those tasks from routine administrative work that does not require legal analysis.

Read the Florida Bar’s explanation of the Court’s guidance.

This distinction protects the association as well as the manager. A manager may know the community’s operations extremely well but still need an attorney to determine whether a proposed action is legally authorized.

The practical approach is to let the manager handle operational matters within the manager’s role and involve counsel when the decision requires legal judgment.


What Can Happen When an Association Handles a Dispute Incorrectly?

The consequences of a poorly handled association dispute depend on the facts. Some disagreements can be resolved through discussion or mediation. Others result in litigation, court orders, or awards of attorney fees and costs.

A recent example illustrates why covenant enforcement deserves careful attention.

In Mooney v. Color Le Palais of Boynton Beach Homeowners Association, Inc., decided by Florida’s Fourth District Court of Appeal on August 27, 2025, the court considered whether an HOA seeking an injunction to enforce a restrictive covenant had to plead and prove irreparable harm and the absence of an adequate remedy at law. The court held that those requirements did not apply under the Florida law governing that dispute.

The homeowners had brought their property into compliance during the litigation, yet the case continued to involve a judgment and an award of prevailing-party attorney fees and costs.

Read the 2025 appellate opinion.

The decision does not mean that an association automatically wins every covenant-enforcement case. It does show why a dispute over a seemingly minor property condition can have financial consequences beyond the original correction.

An attorney can help the board evaluate the legal basis for enforcement and the potential consequences before proceeding.


Does Attorney-Client Privilege Protect an HOA’s Legal Communications?

Attorney-client privilege can protect confidential communications made for the purpose of obtaining or providing legal services. However, not every email involving a lawyer is automatically privileged.

In Las Olas River House Condominium Association, Inc. v. Lorh, LLC, No. 4D15-2289 (Fla. 4th DCA Dec. 9, 2015), a dispute arose over communications involving a condominium association, its management company, and association representatives. The trial court had ordered the production of documents over a claim of privilege without first conducting an in-camera inspection. The appellate court granted relief.

Read the Las Olas River House decision.

The case illustrates a subtle but important point. A manager’s involvement in communications with counsel does not automatically destroy privilege, nor does it guarantee that every communication is protected. The purpose of the communication and the manager’s role in the legal consultation matter.

Boards should establish sensible procedures for communicating with counsel and distributing legal advice. Forwarding sensitive legal analysis to a broad group of residents can create unnecessary complications.


Community association attorney discussing an HOA dispute with a homeowner and board representative in Coral Springs, Florida.

How Can Legal Counsel Help Prevent Conflicts Within an Association?

Disagreements between homeowners and boards are not always caused by bad faith. Sometimes the parties interpret the same governing document differently. In other cases, an owner believes a rule has been applied unfairly, while the board believes it is carrying out its responsibilities.

An attorney can help the association distinguish a legal disagreement from a routine management issue. Counsel may identify a defensible interpretation of the governing documents or recommend a procedure for addressing the dispute before litigation becomes necessary.

Legal advice can also help boards recognize when a decision requires additional review. A director who has a personal interest in a transaction may need to follow specific disclosure procedures. A board considering a new restriction may need to confirm that it has the authority to adopt it.

In Cinco v. Coquina Palms Homeowners Association, Inc., 325 So. 3d 137 (Fla. 5th DCA 2020), the appellate court addressed claims arising from a board member’s breach of fiduciary duty and a conspiracy to defraud the association. The court also ruled that a particular award of attorney fees as damages could not stand because the required special damage had not been pleaded.

Read the Cinco decision.

The case demonstrates that association disputes can involve both substantive wrongdoing and procedural requirements. Even when an association establishes misconduct, the legal basis for each requested remedy matters.


When Is Hiring a Community Association Attorney Worth the Cost?

Legal counsel is an expense, and associations have a responsibility to manage their funds carefully. The question is not whether a lawyer should review every routine decision. It is whether the potential cost of proceeding without legal advice justifies obtaining it before acting.

Consider an association preparing to sign a substantial construction contract. A legal review may identify unclear payment terms or inadequate protections before the agreement is signed. Correcting those provisions at the outset may be easier than disputing them after work has begun.

The same reasoning applies to a proposed amendment. If the association invests time and money in an invalid voting process, it may need to repeat the process or defend a challenge.

Legal counsel also provides continuity when board membership changes. Governing documents and contractual obligations can remain in force long after the directors who approved them leave office. Clear records and sound legal guidance help a new board understand existing obligations.

No attorney can guarantee that litigation will be avoided. The value lies in making informed decisions and identifying legal problems while the association still has options.


What Should a Coral Springs HOA Look for When Choosing an Association Attorney?

A homeowners association in Coral Springs should look for an attorney who understands Florida community association law and has experience interpreting governing documents, advising boards, and resolving disputes involving homeowners. Local familiarity can also help when a matter involves Broward County courts or established procedures for handling property-related litigation.

Before retaining counsel, an association should consider the nature of its legal needs. A community facing a disputed covenant amendment may require different expertise from one negotiating a major construction contract or defending an enforcement action.

The board should also clarify how the attorney will communicate with directors, what work falls within the engagement, and how fees will be handled. For recurring legal needs, a clear arrangement can help the association obtain advice before a decision becomes urgent.

Associations should not choose counsel solely on the basis of price. The least expensive initial consultation may not provide the most useful guidance if the attorney lacks experience with the legal issue at hand. Conversely, not every routine management question requires a lengthy legal opinion.

For HOAs and condominium associations in Coral Springs, Broward County, and South Florida, the objective is to find counsel who can explain the applicable law in practical terms and help the board make informed decisions.


What Documents Should an HOA Board Gather Before Consulting an Attorney?

Preparing the relevant records before a legal consultation can help an association obtain more focused advice and avoid spending time reconstructing the history of a dispute.

The documents needed will depend on the issue, but an HOA or condominium board should consider gathering the following:

  • Governing documents: The declaration, bylaws, current rules, and any amendments relevant to the dispute.
  • Board records: Meeting minutes, resolutions, notices, and records showing how the decision was approved.
  • Correspondence: Relevant communications with the homeowner, contractor, property manager, or other parties.
  • Contracts and financial records: The agreement at issue, invoices, payment records, or assessment statements, where applicable.
  • Enforcement history: Previous violation notices and records of how comparable situations were handled.
  • Deadlines and pending proceedings: Any demand letters, court filings, hearing notices, or statutory response deadlines.

The association should preserve relevant records and avoid altering documents once a dispute is anticipated. It should also identify any approaching deadlines when contacting counsel. Waiting until a hearing or response date is imminent may limit the available options.

Providing complete, organized records helps an attorney assess the association’s position more efficiently. It does not guarantee a particular outcome, but it gives counsel a clearer basis for explaining the available options and potential risks.


Florida attorney reviewing community association legal materials in a Coral Springs law office.

Frequently Asked Questions About Florida HOA and Condo Association Lawyers


Does a Florida HOA have to hire an attorney?

  • Not every HOA decision requires an attorney, and the need for counsel depends on the issue and applicable law. An association should seek legal advice when a proposed action requires legal interpretation or presents a significant risk of a dispute. Specific statutory requirements may apply to particular matters.

Can an HOA manager interpret Florida law for the board?

  • A manager can handle many administrative tasks, but certain activities involving legal interpretation constitute the practice of law under Florida Supreme Court guidance. The distinction depends on the task and whether it requires legal analysis rather than routine administration.

Does an HOA attorney represent individual homeowners?

  • Generally, no. The association’s attorney represents the association as the client. A homeowner involved in an individual dispute with the board may need independent counsel to assess personal rights and remedies.

Can an HOA enforce a rule without consulting an attorney?

  • An association may handle routine enforcement under established procedures. Legal review becomes particularly useful when the rule’s validity is uncertain, the governing documents are ambiguous, or the owner challenges the association’s authority.

Can an HOA board member be personally liable for a decision?

  • Potential liability depends on the applicable law, the governing documents, and the director’s conduct. Florida law imposes duties on association directors and officers, but it does not make every mistaken decision a basis for personal liability. Conflicts of interest or conduct that violates applicable duties may raise different concerns.

Are HOA attorney communications confidential?

  • Some communications may be protected by attorney-client privilege when they meet the applicable legal requirements. The presence of an attorney does not automatically make every email or document privileged. The purpose of the communication and the circumstances of disclosure matter.

When should a condominium association consult a lawyer?

  • A condominium association should consider legal advice when it proposes changes to governing documents, faces a significant enforcement dispute, negotiates a substantial contract, or needs to interpret its statutory obligations. The appropriate response depends on the particular issue.

Community Association Legal Guidance in Broward County

Community associations must make decisions that affect shared property, community finances, and individual owners’ rights. Understanding the association’s legal authority can help its board act responsibly and address disputes before they become more difficult to resolve.

For an HOA or condominium association in Coral Springs, Broward County, or elsewhere in South Florida, legal counsel can help clarify governing-document requirements and assess proposed actions under Florida law.

Reinfeld, Cabrera & Tison can advise on community association legal matters and related property-law issues. If your association is facing a dispute over rule enforcement, a proposed amendment, or a significant contract, obtaining legal guidance early can help the board understand its options before deciding how to proceed.

Contact the firm to discuss your association’s circumstances and determine what legal assistance may be appropriate.


This article provides general information about Florida community association law. It is not legal advice for a particular association or dispute.

How a Demand Letter Can Resolve Business Disputes Without Going to Court

When a commercial contract breaks down, an invoice goes unpaid, or a business partner fails to deliver, rushing straight into a lawsuit is rarely the smartest first move. Litigation in South Florida courts can easily take 12 to 18 months, cost tens of thousands of dollars in legal fees, and permanently destroy valuable commercial relationships.

In many cases, a strategically drafted commercial demand letter from an experienced business attorney is all it takes to enforce your rights, recover owed funds, and force a resolution—saving your business time, capital, and unnecessary stress.


What Is a Commercial Demand Letter?

Quick Answer: A commercial demand letter is a formal legal instrument sent by an attorney outlining a breach of contract or unpaid debt, detailing the exact financial or performance remedy required under Florida law, and setting a firm deadline to comply. It transitions an informal dispute into an active legal matter, establishes an official evidentiary record, and provides maximum settlement leverage before initiating formal court proceedings.


Why Demand Letters Resolve Disputes Effectively

Informal emails, text messages, and phone calls are easy for a non-paying client or defaulting vendor to ignore. However, receiving a formal legal letter on law firm letterhead fundamentally shifts the dynamics of a dispute. It signals that your business has engaged counsel and is fully prepared to take legal action if necessary.

Specifically, a well-crafted demand letter accomplishes four critical objectives:

  1. Establishes an Unassailable Evidentiary Record: It clearly documents the timeline of the deal, the precise contractual terms, the exact nature of the breach, and the total financial damages incurred.
  2. Imposes a Firm Compliance Deadline: Giving the opposing party a strict window (typically 10 to 30 days) forces them to pause, consult with their own legal counsel, and evaluate their potential exposure in court.
  3. Triggers Florida Pre-Suit Statutory Prerequisites: Certain causes of action under Florida law require written pre-suit notice. Sending a formal demand satisfies these prerequisites while preserving your right to claim statutory default interest under Fla. Stat. § 55.03.
  4. Protects Confidentiality: Unlike court pleadings filed in public records, settlement negotiations prompted by a demand letter remain completely private between the parties.

Strategic Tone Selection: Tough vs. Tactful

Before your attorney drafts the letter, you must evaluate one essential question: Do you want to preserve a commercial relationship with this party after the dispute is resolved?

Your business objectives determine the tone and posture of the letter.


┌──────────────────────────────────────────────────────────────────────────┐
│              COMMERCIAL DEMAND LETTER STRATEGIC MATRIX                   │
├────────────────────────────────────┬─────────────────────────────────────┤
│      COLLABORATIVE SETTLEMENT      │        AGGRESSIVE ENFORCEMENT       │
├────────────────────────────────────┼─────────────────────────────────────┤
│ • Objective: Preserve an ongoing   │ • Objective: Rapid financial or     │
│   vendor, client, or partner deal  │   injunctive recovery               │
│ • Focus: Mutual contract terms     │ • Focus: Strict pre-suit notice,    │
│   and structured cure options      │   damages, and statutory remedies   │
│ • Ideal For: Minor delays or       │ • Ideal For: Severe breach, fraud,  │
│   good-faith misunderstandings     │   or persistent non-payment         │
└────────────────────────────────────┴─────────────────────────────────────┘

1. The Collaborative Settlement Approach

If the dispute stems from a temporary cash flow hiccup, operational delay, or honest miscommunication with a long-term partner, an overly aggressive letter can backfire. In such cases, the demand letter adopts a firm yet professional tone. It emphasizes the underlying agreement, specifies the performance gap, and offers workable solutions—such as a structured payment plan—without burning bridges.

2. The Direct Enforcement Approach

Conversely, if you are dealing with intentional contract evasion, fraud, or a debtor refusing to communicate, soft language will yield no results. Consequently, the letter adopts an uncompromising legal stance. It explicitly details statutory causes of action, calculates interest and penalties, attaches supporting exhibits, and gives clear notice that failure to comply will result in an immediate lawsuit filed in local courts like the 17th Judicial Circuit in Broward County.


4 Essential Elements of an Enforceable Florida Demand Letter

To ensure your demand letter commands authority and holds up if the case proceeds to trial, your attorney will structure it with four core components:

1.1. Contractual & Factual Recital: Establishing the factual timeline.

A clear, detailed chronological background outlining the original agreement, purchase orders, or scope of work executed between the parties, alongside specific evidence showing full performance on your part.

2.2. Specific Allegation of Breach: Identifying the exact legal failure.

An explicit accounting of how the opposing party failed to perform, citing specific clauses of the contract, delivery deadlines missed, or unpaid invoices.

3.3. Itemized Statement of Damages: Calculating financial exposure.

A precise breakdown of direct financial losses, incidental expenses, and accrued statutory interest under Fla. Stat. § 55.03, demonstrating exactly what the non-compliance is costing your company.

4.4. Demand for Cure & Litigation Warning: Setting the litigation threshold.

A specific date by which full payment or cure action must occur, accompanied by explicit notice that non-compliance will trigger a civil complaint seeking full damages, court costs, and attorney fees where applicable.


Comparing Dispute Resolution Options

Understanding how a pre-suit demand letter compares to traditional litigation highlights why it should almost always be your first line of defense:

FeatureLegal Demand LetterFull Court Litigation
Time to Resolution10 to 30 Days6 to 18+ Months
Legal CostsLow, Fixed & PredictableHigh (Discovery, Depositions, Trial)
Privacy & Publicity100% PrivatePublic Court Record
Business RelationshipPotential to PreserveAlmost Always Destroyed
Enforcement LeverageHigh (Pre-suit notice & pressure)Binding Court Judgment

Protect Your Business Interests with South Florida Counsel

Allowing unpaid invoices, breach of contract, or vendor default to linger threatens your company’s cash flow and growth. The commercial litigation team at Reinfeld & Cabrera P.A. helps business owners across South Florida resolve complex disputes swiftly through strategic demand letters and aggressive trial representation when required.

Schedule a Commercial Consultation

If your company is facing a contract dispute, unpaid account, or partnership conflict, speak directly with an attorney to evaluate your legal remedies:

  • Direct Line: (954) 866-4878 | Toll-Free: 954-866-HURT
  • Coral Springs Office: 9625 W. Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W. Cypress Creek Rd, Suite 201, Ft. Lauderdale, FL 33309
  • Website: mypersonalattorneys.com
  • Serving: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all of Broward, Miami-Dade, and Palm Beach Counties.

Frequently Asked Questions: Florida Commercial Demand Letters

What happens if the other party completely ignores a demand letter?

  • If the receiving party fails to respond or cure the default within the designated deadline (typically 10 to 30 days), your attorney will move forward with filing a formal civil complaint in the appropriate court—such as the 17th Judicial Circuit Court in Broward County or the 11th Judicial Circuit Court in Miami-Dade County. Furthermore, the demand letter serves as key evidence demonstrating that you made a good-faith pre-suit effort to resolve the dispute, which can influence court decisions regarding legal costs and interest.

Can I write and send a demand letter myself without an attorney?

  • While a business owner can technically write their own letter, DIY demand letters rarely carry the legal weight needed to force a settlement. Specifically, letters drafted without counsel often omit necessary statutory citations, fail to properly preserve rights to pre-judgment interest under Fla. Stat. § 55.03, or reveal strategic weaknesses that the opposing party’s legal team can exploit. A formal letter on law firm letterhead demonstrates immediate litigation readiness.

Can a demand letter include a claim for statutory attorney fees in Florida?

  • Yes. Under Florida law, attorney fees are recoverable if explicitly authorized by the underlying contract or by specific Florida statutes, such as Fla. Stat. § 57.105 (sanctions for unsupported claims/defenses) or statutory civil theft claims under Fla. Stat. § 772.11. Consequently, including a specific statutory fee warning in the demand letter significantly increases your settlement leverage.

How much does it cost to have a South Florida lawyer send a demand letter?

  • Drafting and serving a commercial demand letter is typically billed as a predictable flat fee or a few hours of attorney time, making it significantly more cost-effective than initiating full-scale civil litigation. As a result, most South Florida businesses recover their investment many times over through early pre-suit settlements or full debt recovery.

Broward County Probate Attorney Guide: Formal Administration and Estate Planning

Florida probate attorney reviewing estate planning documents and living trusts in a South Florida law office.

When you sit down at the kitchen table to sort through a parent’s papers after they pass away, the last thing you want is a fresh wave of bureaucratic dread.

What happens to the house now? How do we pay the lingering bills? And why does everyone make probate sound like a multi year hostage negotiation with the state of Florida?


Quick Answer:

Under Florida probate law, administering an estate through the 17th Judicial Circuit in Broward County involves formal or summary court proceedings to settle debts and transfer property. Formal administration typically takes between six months and over a year due to mandatory creditor notice windows, whereas summary administration offers an expedited process for estates valued under $75,000 or where the decedent passed away more than two years ago.


If you search online for estate guidance, you will drown in dry textbook definitions. Most treat probate like an unavoidable trap or a magical cure all. Neither description captures reality. Probate is simply the legal mechanism the state uses to clear title to property. It’s how to pay legitimate creditors, and transition assets when someone passes away without proper advance planning.

So what do Florida families and property owners actually need to know about navigating the Broward County court system. What do they need to get to manage a estate, and keep your hard earned assets out of unnecessary courtrooms? Let us pull back the curtain and talk about how estate administration really works in South Florida without any legal mumbo jumbo.


Why the Internet Gets Probate Wrong (And Why Wills Do Not Avoid Court)

There is a stubborn myth floating around the internet that having a last will and testament means your family completely bypasses the probate court. People assume a will acts like a VIP backstage pass that lets your heirs walk right past the judges and walk away with your property.

Nothing could be further from the truth.

Ask yourself: If I spend my entire life building equity in a home and saving for my children, why would I hand them a legal document that explicitly instructs a judge to oversee how those assets get handed out?

A will does not avoid probate. A will is instructions for the probate court. It tells the judge who you want to inherit your belongings. But the court still has to supervise the process, validate the signature, notify creditors, and formally authorize your personal representative to act. If you want to spare your family from court supervision, you have to look beyond a basic will. You should utilize tools like revocable living trusts, payable on death designations, and properly structured joint ownership.


What Actually Goes Through Probate in Florida?

Not every asset a person owns gets sucked into the probate vortex upon death. Understanding the dividing line between probate and non probate property is the first step toward building a sensible estate plan.

  • Probate Assets: Solely owned real estate, bank accounts held in a single name without payable on death instructions, and personal belongings like vehicles or jewelry without designated beneficiaries must go through court administration to change legal ownership.
  • Non Probate Assets: Assets governed by contract or operation of law pass directly to beneficiaries without court interference. This includes living trusts, life insurance policies with named beneficiaries, retirement accounts. It also includes real estate held as tenants by the entirety or joint tenants with rights of survivorship.

If your estate consists entirely of beneficiary designated accounts and trust owned property, things change. Your family might never set foot inside a courtroom. But if a single deed or bank account was left in your individual name, the probate doors swing wide open.


Formal Administration Versus Summary Administration in Broward County

When a probate estate is opened in the 17th Judicial Circuit in Broward County, the administration generally follows one of two statutory paths. Both depend on the size of the estate and how long the decedent has been gone:

  1. Formal Administration: This is the standard, comprehensive court process required for larger estates or complex matters involving multiple creditors and disputed claims. The court appoints a personal representative, issues letters of administration, requires formal publication of notice to creditors, and mandates a multi month inventory and accounting process.
  2. Summary Administration: A streamlined, expedited court procedure available in Florida if the value of the entire estate subject to probate does not exceed $75,000, or if the decedent has been dead for more than two years. Summary administration bypasses the appointment of a personal representative and moves much faster, though it still requires a formal petition filed by an attorney.
Infographic comparing formal probate administration and summary administration pathways under Florida law.

Avoiding Dual Tracking and Creditor Traps During Estate Administration

When a personal representative steps up to manage an estate in South Florida, they quickly realize that administering assets is a minefield of strict statutory deadlines and creditor notification rules under Florida Probate Code.

How do you handle aggressive credit card companies or mortgage lenders demanding payment while the estate is still frozen in court?

  • The Creditor Notice Period: Florida law requires a diligent search for known creditors and publication of a formal notice in a local legal periodical. Creditors have a strict window (typically three months from the first publication of notice) to file formal claims against the estate.
  • The Priority of Claims: You cannot simply pay out inheritance money to family members while valid estate debts remain unpaid. Florida law establishes a rigid priority structure for paying funeral expenses, administrative costs, taxes, and medical bills before beneficiaries see a dime. Failing to follow this order can expose the personal representative to personal financial liability.

Real World Case Example: Untangling an Estate in Broward County

To see how these rules play out in local practice, consider a scenario our firm frequently handles across Coral Springs and Fort Lauderdale.

A client came to our office after losing a parent who owned a residential home in Broward County without a living trust. The parent had left a simple will naming our client as personal representative, but because the deed was in the parent’s individual name, the property was completely frozen. To make matters worse, a home equity line of credit was past due, and the lender was threatening default proceedings while the family was still grieving.


How Our Legal Team Resolved the Crisis

  • Opening Formal Administration: We immediately filed a petition for formal administration in the 17th Judicial Circuit, securing letters of administration so our client had the legal authority to deal with the bank.
  • Publishing Creditor Notice: We managed the statutory creditor notice period. We shield the personal representative from harassing collection calls and ensuring claims were evaluated through proper legal channels.
  • Resolving the Debt and Transferring Title: By coordinating with the mortgage lender and liquidating a small non probate account to cover arrears, we stabilized the property, avoided foreclosure, and ultimately transferred clear title of the home to the rightful heirs.
The Broward County judicial complex in Fort Lauderdale where 17th Judicial Circuit probate proceedings take place.

Frequently Asked Questions About Florida Probate

How long does the probate process take in Broward County?

  • An uncontested formal administration in Florida typically spans 6 to 12 months. This timeline is largely dictated by mandatory statutory creditor notice periods and court review schedules in the 17th Judicial Circuit. Complex estates involving will contests or contested creditor claims can take significantly longer.

Can I avoid probate simply by writing a last will and testament?

  • No. A common misconception is that having a will avoids probate. In reality, a will provides instructions for the probate court on how you want your assets distributed. To avoid probate entirely, assets must pass outside the will via living trusts, beneficiary designations, or survivorship titles.

What happens if someone dies intestate without a will in Florida?

  • If a person dies without a valid will, Florida intestacy statutes dictate how assets are distributed among surviving spouses, children, or extended relatives. This rigid statutory formula rarely matches what the decedent would have actually wanted. And it often forces court sales of family property to divide proceeds among heirs.

Do I need a probate attorney if I am appointed as a personal representative?

  • Yes. Under Florida probate rules, a personal representative representing an estate with multiple beneficiaries or outstanding creditors is generally required by law to be represented by a licensed attorney admitted to practice in Florida.

Protect Your Estate and Your Family Legacy

Planning for the future or handling the aftermath of a loved one’s passing is not something you should do alone. Whether you want to bulletproof your own estate with a comprehensive living trust or you need experienced local counsel to guide you through a Broward County probate administration, having the right advocate changes everything.

The estate planning and probate attorneys at Reinfeld Cabrera Tison help families across South Florida secure their assets. We establish durable trusts, and resolve complex court proceedings with absolute confidence.

Schedule a Confidential Consultation

Do not wait until a crisis forces your family into court. Speak directly with an experienced attorney today to review your options:

  • Direct Telephone: (954) 866 4878 | Toll Free: (954) 866 HURT
  • Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Website: mypersonalattorneys.com
  • Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate. All surrounding communities across Broward, Miami Dade, and Palm Beach Counties.