A concerned couple at a South Florida mailbox reads an insurance non-renewal notice stating their 12-year-old roof is an uninsurable liability. They are holding a 2026 survival guide and a summary of new Florida roof laws protection.

The South Florida Homeowner’s 2026 Roof Insurance Survival Guide

Opening your mailbox in Broward, Miami-Dade, or Palm Beach County often feels like an unpredictable gamble. One afternoon you are enjoying South Florida weather, and the next you are holding a notice from your insurance carrier stating that your 12-year-old roof is suddenly an uninsurable liability—demanding a $25,000 full replacement under threat of immediate non-renewal.

Before panicking or signing a contract with a door-to-door roofer, understand the ground rules. Florida property insurance regulations give homeowners explicit statutory protections that many carriers conveniently omit in their automated non-renewal letters.


Executive Legal Summary: Florida’s Roof Age Laws at a Glance

  • Roofs Under 15 Years Old: Under Florida Statute § 627.7011(5), property insurance carriers cannot deny coverage or refuse to renew a policy solely based on the age of your roof.
  • Roofs 15 Years or Older: Insurers can require a roof inspection, but they cannot deny coverage or force a replacement if an authorized inspector certifies that the roof has at least 5 years of remaining useful life.
  • Authorized Inspector Qualifications: Inspections must be completed by a licensed general contractor, building contractor, residential contractor, professional engineer, professional architect, or certified building code inspector.
  • Citizens Property Insurance Thresholds: Citizens requires roofs over 25 years old (for shingle) or 50 years old (for tile/metal) to submit a 4-Point or Roof Inspection Form proving 5+ years of useful life.
A distressed South Florida homeowner holds up an insurance non-renewal notice demanding $25,000 for a 12-year-old roof.

1. The Legal Reality: Florida’s 15-Year Roof Rule (Fla. Stat. § 627.7011)

Many homeowners mistakenly believe that reaching the 10- or 12-year mark on an asphalt shingle roof gives an insurer automatic legal authorization to cancel their policy. That is false.


                    FLORIDA ROOF AGE STATUTORY TIMELINE

 [0 to 14 Years Old]  ================================> CANNOT NON-RENEW SOLELY ON AGE

                                                       (Fla. Stat. § 627.7011(5))

 [15+ Years Old]      ================================> INSPECTION REQUIRED

                                                         │

                                                         ├─> 5+ Years Useful Life = COVERAGE MANDATED

                                                         └─> <5 Years Useful Life = Replacement/Repair


Protection for Roofs Under 15 Years

Florida Statute § 627.7011(5) explicitly states that an insurance company issuing or renewing a homeowners policy cannot refuse coverage solely because of roof age if the roof surface is less than 15 years old. If your carrier sends a non-renewal notice citing only a 12-year or 14-year roof age, they are violating state insurance guidelines.

The “5-Year Useful Life” Rule for Older Roofs

Once your roof hits or exceeds 15 years of age, the insurer gains the right to demand a professional roof inspection prior to policy renewal. However, the law still protects you: if the inspection proves your roof has at least 5 years of remaining useful life, the insurance company cannot reject your renewal application or force a complete replacement based on age alone.


2. Insurance Company Scare Tactics vs. Florida Statutory Law

Claim Made by Insurance CarrierActual Florida Legal & Statutory StandardImpact on Property Owner
“Your shingle roof is 12 years old, so you must replace it within 30 days to keep your policy.”Violates Fla. Stat. § 627.7011(5). Insurers cannot drop policies solely for roof age under 15 years.You do not have to replace a functional 12-year-old roof just because the carrier requests it.
“Your 16-year-old roof failed our satellite image review, so we are non-renewing.”Insurers must allow you to hire an authorized inspector to perform an in-person evaluation.Aerial satellite photos cannot override a physical inspection certifying 5+ years of useful life.
“Only our internal adjusters can determine if your roof is acceptable.”Inspections can be completed by any licensed Florida contractor, engineer, or home inspector.You have the right to hire your own independent inspector to document your roof’s actual condition.
“You must switch to an Actual Cash Value (ACV) endorsement or face immediate cancellation.”Policy changes must comply with OIR filings, and insurers must give advance written notice of endorsement alterations.ACV reduces payouts by factoring in heavy depreciation; understand what rights you give up before signing.

3. RCV vs. ACV: The Hidden Policy Trap

Understanding how your insurance carrier calculates roof damage payouts is essential when navigating renewals and storm damage claims.

  • Replacement Cost Value (RCV): The insurer covers the actual cost to repair or replace the damaged roof with similar materials at current market prices, without deducting money for age or wear and tear.
  • Actual Cash Value (ACV): The insurer deducts depreciation based on the age and condition of the roof before issuing a payment.

If a 15-year-old roof with a 20-year lifespan suffers severe storm damage under an ACV policy, the insurer may only pay 25% of the replacement cost, leaving the homeowner responsible for the remaining 75% out-of-pocket. Pay close attention to policy renewal documents—carriers frequently attempt to slip ACV roof endorsements onto older homes during annual renewals.
A proactive South Florida homeowner examines a roof with a licensed inspector who holds a 'ROOF CONDITION VERIFICATION FORM' certifying '5+ YEARS REMAINING USEFUL LIFE'

4. Roof Materials & Expected Insurable Lifespans

The material covering your home dramatically influences underwriting guidelines across private carriers and state-backed insurers like Citizens Property Insurance Corporation.


┌─────────────────────────┬─────────────────────────┬─────────────────────────┐

│ Roof Material Type      │ Typical Industry Life   │ Citizens Inspection Limit│

├─────────────────────────┼─────────────────────────┼─────────────────────────┤

│ Architectural Shingle   │ 15 to 25 Years          │ Inspection at 25 Years  │

│ Concrete / Clay Tile    │ 25 to 50 Years          │ Inspection at 50 Years  │

│ Standing Seam Metal     │ 30 to 50+ Years         │ Inspection at 50 Years  │

│ Flat / Low-Slope Membrane│ 10 to 15 Years          │ Inspection at 15 Years  │

└─────────────────────────┴─────────────────────────┴─────────────────────────┘


  • Asphalt Shingle Roofs: Private carriers scrutinize shingle roofs most heavily starting at year 15. However, high-grade architectural shingles often maintain structural integrity well beyond 15 years if properly maintained.
  • Tile & Metal Roofs: Concrete tiles, clay tiles, and standing-seam metal roofs regularly handle South Florida wind loads for decades. Citizens Property Insurance allows tile and metal roofs to reach up to 50 years before mandatory age-based useful life documentation is triggered.

5. Step-by-Step Defense Action Plan: Responding to a Non-Renewal Notice

If an insurance company delivers a notice demanding roof replacement or threatening non-renewal in Broward, Miami-Dade, or Palm Beach County, follow this structured response plan:


[Step 1: Audit Notice] ──> [Step 2: Hire Inspector] ──> [Step 3: Submit Form] ──> [Step 4: Legal Review]

  Check stated reasons       Independent 4-Point        Provide 5-year cert       Enforce statutory

  and roof age dates.        Roof Inspection.           to insurance carrier.     rights if denied.


  1. Audit the Non-Renewal Letter: Check the exact reason cited by the carrier. If the only reason listed is that your roof is between 1 and 14 years old, the notice violates Fla. Stat. § 627.7011(5).
  2. Order an Independent Roof Inspection: Contact a licensed Florida general contractor, building inspector, or engineer. Ask specifically for a Florida 4-Point Inspection or Roof Condition Verification Form.
  3. Secure the 5-Year Useful Life Certification: Ensure the inspector documents that the roof has at least 5 years of remaining useful life. This written verification serves as your primary protection under state law.
  4. Submit Formal Documentation via Certified Mail: Send the completed inspection report directly to your insurance agent and carrier. Request formal written confirmation that the non-renewal notice has been rescinded.
  5. Consult Legal Counsel if the Carrier Refuses: If an insurer ignores state statute and refuses to accept a valid 5-year useful life certification, legal intervention may be required to protect your property rights and coverage.

6. Frequently Asked Questions


Can my insurance company drop me if my shingle roof is only 12 years old?

No. Under Florida Statute § 627.7011(5), insurance companies cannot refuse to issue or renew a homeowners insurance policy solely because of roof age if the roof is less than 15 years old.

Who qualifies as an “authorized inspector” in Florida?

Under state law, authorized inspectors include licensed general contractors, building contractors, residential contractors, professional engineers, professional architects, and certified building code inspectors.

What happens if my roof is over 15 years old but in great condition?

If an authorized inspector certifies that your 15+ year old roof has at least 5 years of remaining useful life, Florida law prevents the insurer from denying or non-renewing your coverage solely based on roof age.

Does Citizens Property Insurance follow the same roof rules?

Yes, Citizens Property Insurance must comply with Florida statutory requirements. Citizens requires documentation verifying at least 5 years of remaining useful life for shingle roofs older than 25 years and tile/metal roofs older than 50 years.


Protecting Your Property Rights Across South Florida

When insurance carriers issue arbitrary non-renewal demands, knowing the statutory rules keeps you in control. If your insurance company is threatening improper non-renewal, forcing unnecessary roof replacements, or mishandling a property damage claim, our team can help you enforce your statutory protections.

Reinfeld Cabrera

Property Law & Real Estate Legal Services

Serving Broward County, Miami-Dade County, and Palm Beach County

Contact Our Office:

Disclaimer: The information provided in this guide is for general informational and educational purposes only and does not constitute formal legal advice. Property insurance laws and underwriting rules change frequently. Consult a qualified Florida legal professional regarding your specific situation.
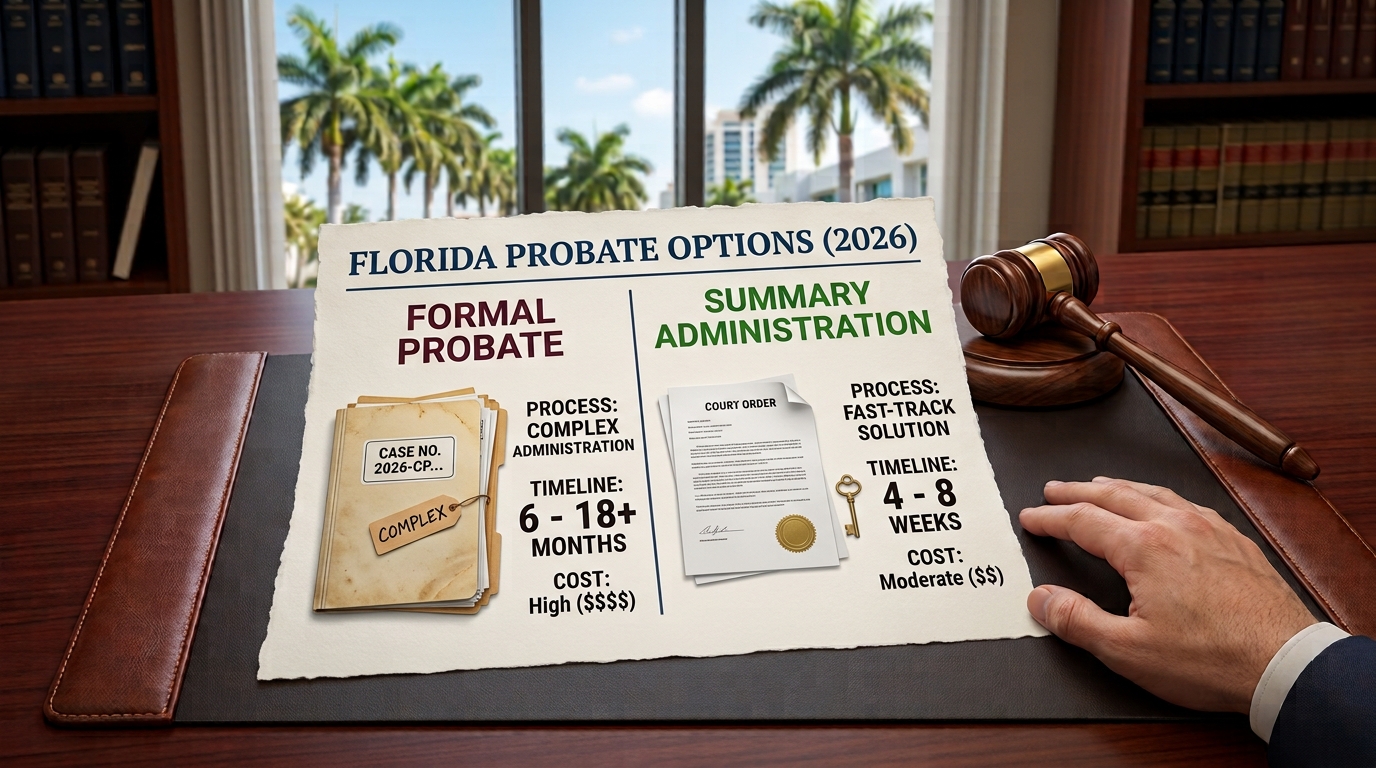
A detailed comparison chart of Formal Probate and Summary Administration on a legal desk with a gavel and hand, detailing process types, timelines (6-18+ months vs. 4-8 weeks), and relative costs for 2026 Florida probate cases.

Florida Summary Administration Requirements: How to Avoid Formal Probate in 2026


When a loved one passes away in Florida, families often assume they are facing a year-long legal battle filled with court dates, stacks of paperwork, and exorbitant administrative costs. However, under Chapter 735 of the Florida Probate Code, many families qualify for a fast-track judicial process known as Summary Administration.

Effective July 1, 2026, Florida doubled the statutory limit for small estate probate under Fla. Stat. § 735.201 from $75,000 to $150,000. This critical update allows significantly more families to distribute estate assets in a matter of weeks rather than months.


Direct Answer

What are the requirements for Summary Administration in Florida?

To qualify for Summary Administration in Florida under Fla. Stat. § 735.201, an estate must satisfy either of the following two criteria:

  1. The $150,000 Asset Cap: The total value of non-exempt Florida probate assets is $150,000 or less (for deaths on or after July 1, 2026).
  2. The 2-Year Rule: The decedent has been deceased for more than two years, regardless of total estate value.

Additionally, the decedent’s Last Will and Testament must not explicitly mandate Formal Estate Administration.


The Two Pathways to Qualifying for Summary Probate

Unlike Formal Administration—which requires the court to appoint a Personal Representative (Executor) and oversee a lengthy administration period—Summary Administration acts as a direct judicial order transferring assets straight to beneficiaries.

┌─────────────────────────────────────────────────────────┐

│           Summary Administration Qualification           │

└────────────────────────────┬────────────────────────────┘

                             │

              Does the Estate meet EITHER rule?

                             │

         ┌───────────────────┴───────────────────┐

         ▼                                       ▼

┌─────────────────────────┐             ┌─────────────────┐

│     The $150,000 Cap    │             │   2-Year Rule   │

│ Non-Exempt Assets ≤150k │     OR      │ Deceased >2 Yrs │

│  (Deaths Post-July 2026)│             │ (No Limit Cap)  │

└─────────────────────────┘             └─────────────────┘

Clients meeting with their Florida summary administration probate lawyer in Coral Springs to finalize court petitions and avoid formal probate.

1. The $150,000 Asset Limit (Non-Exempt Property)

For decedents passing on or after July 1, 2026, the estate’s total non-exempt probate assets must not exceed $150,000. (For deaths occurring prior to July 1, 2026, the statutory limit remains $75,000).

2. The Two-Year Statute of Repose Rule

If the decedent passed away more than two years ago, the estate automatically qualifies for Summary Administration, regardless of how millions of dollars the estate is worth. Under Fla. Stat. § 733.710, Florida enforces a strict two-year statute of repose that permanently bars unfiled creditor claims, removing the necessity for a formal personal representative to manage debts.


Why “On-Paper” Net Worth Misleads Most Heirs

One of the most frequent misconceptions beneficiaries encounter is assuming that if a relative owned a high-value home in South Florida, they are automatically forced into Formal Probate.

Florida law only evaluates probate assets subject to court distribution. The following major asset categories are entirely excluded from the $150,000 threshold calculation:

  • Florida Protected Homestead Real Estate: Under Article X, Section 4 of the Florida Constitution, a primary residence passing to a surviving spouse or lineal heirs is constitutionally protected from general creditors. Because homestead rights vest immediately upon death, the home’s value (whether $400,000 or $2,000,000) does not count toward the $150,000 limit when petitions are properly structured.
  • Statutory Exempt Personal Property: Under Fla. Stat. § 732.402, up to $20,000 in household furniture/furnishings and two personal motor vehicles used by the decedent are exempt from creditor claims and excluded from the asset tally.
  • Non-Probate Financial Transfers: Bank accounts with Payable-on-Death (POD) or Transfer-on-Death (TOD) designations, life insurance policies with named beneficiaries, jointly owned property with rights of survivorship, and assets held inside a Revocable Living Trust bypass probate entirely.
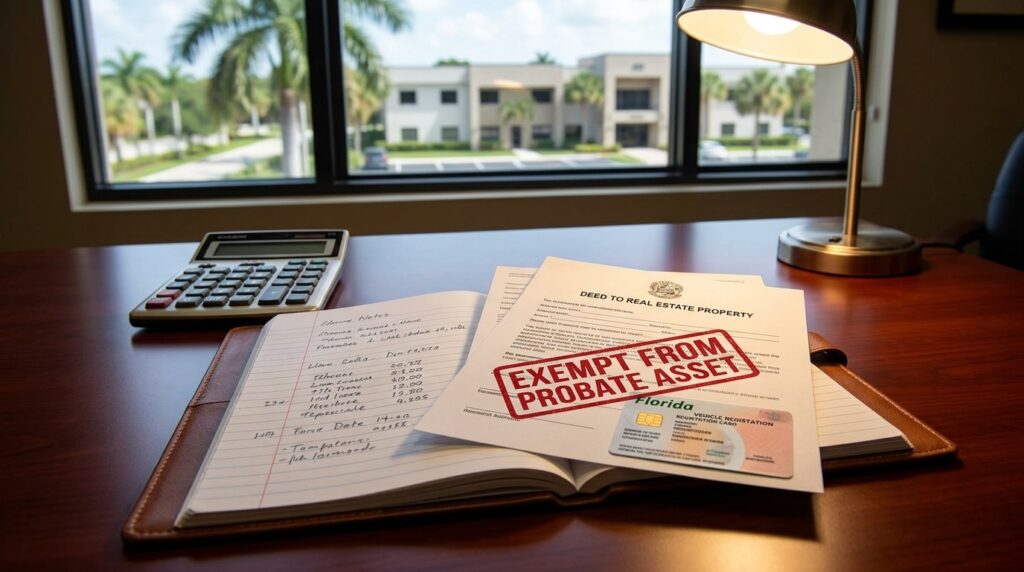
Calculating non-exempt probate assets in Florida: Real estate deed and vehicle documents marked exempt from probate to qualify for summary administration.

“Many families walk into our office believing they owe thousands in court fees because their parent owned a $700,000 house in Coral Springs. Once we isolate the constitutional homestead and exempt vehicles, the actual probate asset is just a $40,000 checking account—qualifying them for fast-track Summary Administration instantly.”

Devin P. Tison, Esq., Lead Partner at Reinfeld Cabrera Tison


Real-World Case Studies: How Summary Administration Works in Practice

Case Study 1: Bypassing Formal Probate for a Broward County Home & Bank Account

  • Scenario: A widow in Fort Lauderdale passed away, leaving a home valued at $550,000 and a sole-name savings account containing $65,000. Her two adult children were named as equal beneficiaries in her Will.
  • The Legal Challenge: A traditional law firm informed the siblings they needed Formal Administration due to the $615,000 gross estate value, quoting an estimated 9-month process and thousands in hourly fees.
  • The RCT Solution: Our probate team filed a Petition for Determination of Homestead Property alongside a Petition for Summary Administration. Because the $550,000 home was protected homestead, its value dropped to $0 for qualification purposes. The only remaining asset was the $65,000 account—well under the statutory limit.
  • Outcome: The Broward County Probate Court issued an Order of Summary Administration in 5 weeks. The bank released the funds directly to the siblings, and the homestead order cleared title for them to sell the home without appointing a Personal Representative.

Case Study 2: Settling an Estate Decades Later for Out-of-State Heirs

  • Scenario: A father passed away in Miami-Dade County in 2018 owning an unlinked parcel of land. His heirs, living in New York, never probated the estate because they believed the process was too complex from out-of-state.
  • The Legal Challenge: The land grew in value to $220,000. The heirs wanted to sell the land but could not clear title without court authorization.
  • The RCT Solution: Because the decedent had been deceased for over two years, the estate qualified under the 2-Year Rule regardless of the $220,000 property value. We managed the entire filing remotely via Florida’s electronic court portal without requiring the heirs to travel to Florida.
  • Outcome: The court signed the distribution order within 4 weeks, enabling the title company to execute a seamless sale.

Detailed Comparison: Summary vs. Formal Administration


Key FeatureSummary Administration (Fla. Stat. § 735.201)Formal Administration (Fla. Stat. Ch. 733)
Statutory EligibilityNon-exempt assets $\le \$150,000$ OR death > 2 years agoEstates over $\$150,000$ or complex litigation cases
Average Timeline4 to 8 weeks6 to 12+ months
Personal RepresentativeNone appointed by the courtCourt appoints an Executor/PR
Letters of AdministrationNot issuedIssued (gives PR power to act for estate)
Primary Court OrderOrder of Summary AdministrationOrder of Discharge
Legal CostsSignificantly lower; often structured as a Flat FeeHigher court fees, inventory costs, and hourly rates

Frequently Asked Questions (FAQ)


Does Florida have a Small Estate Affidavit to avoid probate?

No. Florida does not recognize a standalone “Small Estate Affidavit” for transferring real estate or bank accounts like some other states do. Florida’s equivalent for small estates is Summary Administration or, for extremely small asset values under funeral costs, Disposition Without Administration (Fla. Stat. § 735.301).

What happens to outstanding creditor debts in Summary Administration?

Because no Personal Representative is appointed to manage estate claims, beneficiaries who receive assets through Summary Administration remain personally liable for valid debts of the decedent up to the dollar value of what they inherited. To eliminate this risk, a probate attorney can publish an optional Notice to Creditors in a local South Florida newspaper, initiating a 30-day window that permanently bars unfiled claims.

Can an out-of-state beneficiary file for Summary Administration in Florida?

Yes. Florida probate courts utilize 100% digital filing systems. Out-of-state heirs in New York, New Jersey, or anywhere across the country can hire a local Florida probate lawyer to execute the entire proceeding remotely without ever stepping foot inside a courtroom.

How long does it take to get an Order of Summary Administration?

In South Florida courts (Broward, Miami-Dade, and Palm Beach counties), an uncontested Petition for Summary Administration typically takes 4 to 8 weeks from initial filing to final judge signature, depending on judicial caseloads.


Why Choose Reinfeld & Cabrera, P.A. for South Florida Probate?

Navigating court petitions while grieving a family member can feel overwhelming. At Reinfeld & Cabrera, P.A. (mypersonalattorneys.com), we simplify the Florida probate process with transparency and local courtroom experience:

  • Transparent Flat-Fee Pricing: We eliminate financial anxiety by offering predictable flat legal fees for uncontested Summary Administration—no hidden hourly bills.
  • Bilingual Legal Representation: Our attorneys and staff speak fluent English and Spanish, ensuring clear communication for non-English speaking beneficiaries.
  • Full-Service Local Filings: We handle all court communication across Broward (17th Judicial Circuit), Miami-Dade (11th Judicial Circuit), and Palm Beach (15th Judicial Circuit) counties.

Take Action: Streamline Your Florida Probate Today

If you need to transfer real estate, recover frozen bank accounts, or resolve an estate in South Florida, contact Reinfeld & Cabrera, P.A. today for a free case evaluation.

  • Direct Phone: (954) 334-1520 / (855) 529-7123
  • Coral Springs Office: 9625 W. Sample Rd, Coral Springs, FL 33065
  • Online Consultation: Request a review at mypersonalattorneys.com

What is Probate Litigation?

What is Probate Litigation?

Basically, in a nutshell, someone is challenging a Will, Trust or Intestate estate. For example, our law firm was recently hired by a family member because they believe their family member’s Will was Invalid.

If you believe that a Will/Trust was invalid contact us immediately. With office locations in Coral Springs and Fort Lauderdale, we will be happy to sit down with you and discuss your case. 954-334-1520.

What is a Ladybird Deed? Can I avoid Probate?

As an Probate Attorney in Coral Springs, my firm deals with all types of deeds.

Life Estate Deeds:

With a “regular” life estate deed, the owner of the real estate makes a gift of the property to beneficiaries, called remaindermen. The owner retains a life estate in the property as long as he is alive. He is responsible for all maintenance and taxes on the property. The life tenant cannot mortgage or sell the property during his/her lifetime without the permission and “joinder” of the remaindermen. The life tenant effectively gives the property away—and unilateral control of the property—during his/her lifetime, unless the remainderman join into the transaction.

Ladybird Deed

With an “enhanced” life estate or Lady Bird Deed, the owner of the part of real estate, the “life tenant and Grantor” retains complete control over the property during his/her lifetime. He/She has the right to mortgage or sell the real estate without the consent of his/her remaindermen named in the deed because they have not actually given the property to them yet. The property doesn’t transfer until the death of the life tenant. Once the life tenant passes away, the property is automatically transferred to the beneficiaries avoiding Probate.

If you would like to know more about Ladybird Deeds and how to avoid Probate, call our office today 954-334-1520. Our main office is located in Coral Springs, Florida. We offer free initial consultation, by phone or in person.

5 Probate Myths

Probate-attorneys-in-Coral-Springs

As experienced probate attorneys in Coral Springs we at Reinfeld & Cabrera, P.A. have often come across 5 probate myths that people are convinced are true. As all good probate attorneys in Coral Springs will tell you estate planning is a serious business and essential if you are concerned about what will happen should you become incapacitated or pass away. However it seems that thanks to these 5 probate myths, proper estate planning is often overlooked as costly and unnecessary. That is why we at Reinfeld & Cabrera feel compelled, as trusted probate attorneys in Coral Springs, to make sure you are not falling victim to these top 5 probate myths.

#5. I already have an estate plan and don’t need to think about it again.
This is a constant source of frustration for probate attorneys in Coral Springs. Your estate plan needs to be monitored and updated every time you have a major life change such as divorce, marriage, birth etc. Ideally you should consult with your attorney every four or five years to discuss changes in your circumstances that could affect your estate plan.

#4. There is no need to make my spouse a beneficiary.
Couples tend to assume that if one spouse dies, the other will simply continue living with all the assets in their estate, and that all the assets of the deceased spouse will automatically go to the living spouse. There are so many factors that influence how this works, such as how your assets are titled; and whom you have named as the beneficiaries of your life insurance and retirement accounts. Furthermore if you die without a will, what is left of your estate will be divided between your spouse and your children. This could create issues especially for spouses who are financially dependent on each other or have children from other marriages.

#3. Death Taxes.
As probate attorneys in Coral Springs we have often heard estate tax referred to as unfair “death tax”. When it comes to federal estate tax did you know that there is a $5 million+ federal estate tax exemption? Thanks to this exemption it is estimated that less than 0.10% of estates will be subject to federal estate taxes. When it comes to state estate taxes most states actually impose their own estate tax, which is significantly less then the Federal Government exemption. However, in the state of Florida, the estate tax is not assessed and no portion of what is bequeathed in a will or a trust to an individual will go to the state.

#2. Probate – no problem!
If you live in Florida, this is simply not true! Without the help of a probate attorney your family and loved ones will be left to navigate a gauntlet of complicated probate procedures and be at the mercy of a probate judge who does not know you or your family.

#1. Estate planning is for the rich.
Unless you live in a cave with not a penny or asset to your name you will need an estate plan. An estate plan does not have to be expensive. By speaking with a knowledgeable probate attorney, such as Reinfeld & Cabrera, P.A. you will be able to structure an estate plan that will best suit you and you family’s needs.

How To Avoid Probate

Probate-Attorney

Having discussed the probate process and the importance of a probate attorney, we at Reinfeld & Cabrera, P.A. have decided to put together a quick list of some of the ways on how to avoid probate in Florida. By making use of an experienced probate attorney you will be able to avoid probate with relative ease. As the saying goes prevention is better than cure – especially with the guidance of a probate attorney from Reinfeld & Cabrera, P.A.

1. Name a beneficiary:
Property that lists a transfer on death beneficiary (TOD), or a pay on death beneficiary (POD), passes directly to the named beneficiary. Therefore naming a beneficiary is a frequently used method of avoiding probate. You may name anyone you choose as a TOD or POD on each of your vehicles, your checking and savings accounts, and any annuities, retirement savings, CDs, or other investments that you have. With the guidance of an experienced probate attorney such as Reinfeld & Cabrera, P.A. you will easily be able navigate your way through this process.

2. Create a revocable living trust:
Simply put a revocable living trust is a changeable or revocable legal agreement, in which you name someone as trustee/executor of your affairs description. Upon your death, your chosen trustee/executor will acquire legal title. They will then be able to decide what to do with your property and possessions. In this manner you will be able to avoid many aspects of a traditional will. Naming your trustee must be done through extensive consideration, as they will have a big effect on how your property and possessions are handled after death. A living trust is alterable and assists in avoiding probate. However, a living trust does have some disadvantages. In order to set up a trust and to discuss advantages and disadvantages of revocable living trusts contact a probate attorney such as Reinfeld & Cabrera, P.A.

3. Share ownership:
Share ownership means to take title of property with someone else. If you have joint ownership of property or possessions with another person such as a spouse you can avoid probate. When one of the owners dies, the title will simply pass on to the other owner thus circumventing probate. Contact a probate attorney at Reinfeld & Cabrera, P.A. to discuss setting up joint ownership as well as the potential the advantages and drawbacks of creating joint ownership.

4. Gifting items:
A simple way to avoid probate is to give away items that you don’t want caught up in probate proceedings. By gifting away your property or possession (especially more expensive items) it cannot go into probate.

There are various other ways to avoid probate, many of which are state specific. Consult a probate attorney such as Reinfeld & Cabrera, P.A. for comprehensive guidance on how to best avoid probate in Florida.

Breaking Down The Probate Process

For many people the probate process may seem like an overwhelming and daunting task. So the probate attorney’s from Reinfeld & Cabrera, P.A are here to make things easier.

To begin the probate process the executor of the decedent’s will must come forward with the will. If there is no will or an executor and the family cannot agree on one, then the court may assign an administrator. The executor or Personal Representative’s authority extends only as far as the decedent’s probate estate. An experienced probate attorney can clarify which assets qualify for probate. A Petition for Probate of Will and Appointment of Personal Representative’s as well as the decedent’s death certificate needs to be filed at the court clerk’s office. The court will then review the petition and an Personal Representative will be formally appointed. It is wise to have a probate lawyer assist with this process. Once this has been given the green-light the probate process can officially begin.

Step One: Probate Assets
All the decedent’s assets will need to be collected, inventoried and appraised. These assets include money owed to the decedent or estate such as life insurance or loans. Other assets such as real estate or valuable collections will need to be appraised by professionals and financial accounts such as stocks or bonds may need to be reviewed or sold in order to collect all the assets to be distributed.

Step Two: Paying-out
All debts and expenses must be paid. The Personal Representative is responsible for paying these expenses with the estate funds. Expenses will be paid usually in the following order:

  • Costs/expenses of administration (for example – attorneys or appraisers)
  • Funeral expenses
  • Debts and taxes
  • All other claims

The Personal Representative is in charge of reviewing all debts, bills or claims against the decedent. After reviewing all necessary documents and proof of claims the a Personal Representative then has the right to reject those which are deemed invalid and pay the ones that need to be paid. Rejected claims may be appealed by claimants within a particular time period; these cases may then need to be handled by probate attorneys.

Step Three: Distributing Assets
The remainder of the estate can be distributed to the beneficiaries as the will states, or as the administrator sees fit if not stated, or (in the case of no will) according to intestate law. A public announcement in a newspaper is required to be published stating that the estate is in probate to allow any remaining creditors to come forward. This is also the point in the process where those who want to dispute the distribution of assets can be heard.

Even though these steps may make the probate process seem a lot simpler and manageable than before, there are many technical and important details which can be explained when contacting an experienced probate attorney. The probate attorney’s at Reinfeld & Cabrera, P.A are uniquely qualified and experienced in the administration of the probate estate, they can either guide you or be the administrator.

Scary Truths of Probate

If the word “probate” makes you feel uncomfortable, then you need to understand the estate planning process and make sure your estate is taken care of after you pass away. Probate doesn’t have to be a scary process. The attorneys at Reinfeld & Cabrera, P.A. can make sure your estate is in order and take the worry out of probate.

Probate is the formal court procedures that administer a person’s estate after they have died. It is during this process where outstanding debts can be paid and property can be sold or transferred to another person. It some cases, it can be a complex procedure so it is always wise to set up your estate plans before you pass away. In other cases, probate can be a problem-free carrying out of a person’s will. It all depends on the specifics of each situation and we can help you determine what impact probate could have on your estate.

Only certain aspects of a person’s estate will enter into the probate process. For instance, probate does not involve a trust, life insurance, or retirement accounts that have named beneficiaries, or jointly-owned property, when the first joint owner has died.

Probate, which is part of public record, can be a lengthy process that lasts six months or longer. We can help you at Reinfeld & Cabrera, P.A. to recognize what parts of your estate might be better suited to a trust, in order to avoid the probate process. We will also help you recognize when a will is appropriate for your specific situation, and when probate will be necessary.

While it may not be possible to set up your estate to completely avoid probate, we may be able to better set up your estate so that probate is manageable. By creating trusts, setting up some joint ownerships, and designating beneficiaries, we will be able to avoid probate in some areas. Let us help you with your estate planning and to make probate seem less scary.