Opening your mailbox in Broward, Miami-Dade, or Palm Beach County often feels like an unpredictable gamble. One afternoon you are enjoying South Florida weather, and the next you are holding a notice from your insurance carrier stating that your 12-year-old roof is suddenly an uninsurable liability—demanding a $25,000 full replacement under threat of immediate non-renewal.
Before panicking or signing a contract with a door-to-door roofer, understand the ground rules. Florida property insurance regulations give homeowners explicit statutory protections that many carriers conveniently omit in their automated non-renewal letters.
Executive Legal Summary: Florida’s Roof Age Laws at a Glance
Roofs Under 15 Years Old: Under Florida Statute § 627.7011(5), property insurance carriers cannot deny coverage or refuse to renew a policy solely based on the age of your roof.
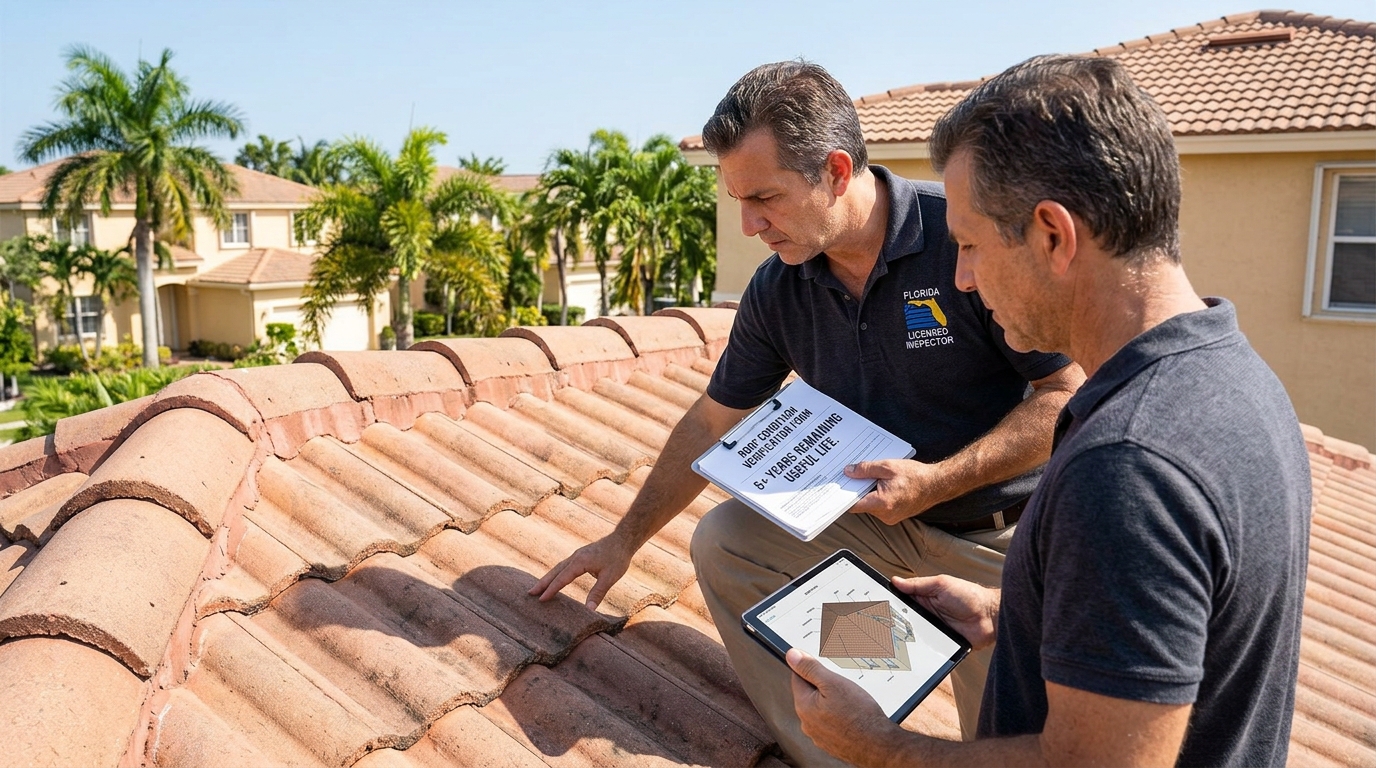
Roofs 15 Years or Older: Insurers can require a roof inspection, but they cannot deny coverage or force a replacement if an authorized inspector certifies that the roof has at least 5 years of remaining useful life.
Authorized Inspector Qualifications: Inspections must be completed by a licensed general contractor, building contractor, residential contractor, professional engineer, professional architect, or certified building code inspector.
Citizens Property Insurance Thresholds: Citizens requires roofs over 25 years old (for shingle) or 50 years old (for tile/metal) to submit a 4-Point or Roof Inspection Form proving 5+ years of useful life.
Many homeowners mistakenly believe that reaching the 10- or 12-year mark on an asphalt shingle roof gives an insurer automatic legal authorization to cancel their policy. That is false.
FLORIDA ROOF AGE STATUTORY TIMELINE
0 to 14 Years Old
➔
CANNOT NON-RENEW SOLELY ON AGE
(Fla. Stat. § 627.7011(5))
15+ Years Old
➔
INSPECTION REQUIRED
• 5+ Years Useful Life = COVERAGE MANDATED
• < 5 Years Useful Life = Replacement / Repair
Protection for Roofs Under 15 Years
Florida Statute § 627.7011(5) explicitly states that an insurance company issuing or renewing a homeowners policy cannot refuse coverage solely because of roof age if the roof surface is less than 15 years old. If your carrier sends a non-renewal notice citing only a 12-year or 14-year roof age, they are violating state insurance guidelines.
The “5-Year Useful Life” Rule for Older Roofs
Once your roof hits or exceeds 15 years of age, the insurer gains the right to demand a professional roof inspection prior to policy renewal. However, the law still protects you: if the inspection proves your roof has at least 5 years of remaining useful life, the insurance company cannot reject your renewal application or force a complete replacement based on age alone.
2. Insurance Company Scare Tactics vs. Florida Statutory Law
Claim Made by Insurance Carrier
Actual Florida Legal & Statutory Standard
Impact on Property Owner
“Your shingle roof is 12 years old, so you must replace it within 30 days to keep your policy.”
Violates Fla. Stat. § 627.7011(5). Insurers cannot drop policies solely for roof age under 15 years.
You do not have to replace a functional 12-year-old roof just because the carrier requests it.
“Your 16-year-old roof failed our satellite image review, so we are non-renewing.”
Insurers must allow you to hire an authorized inspector to perform an in-person evaluation.
Aerial satellite photos cannot override a physical inspection certifying 5+ years of useful life.
“Only our internal adjusters can determine if your roof is acceptable.”
Inspections can be completed by any licensed Florida contractor, engineer, or home inspector.
You have the right to hire your own independent inspector to document your roof’s actual condition.
“You must switch to an Actual Cash Value (ACV) endorsement or face immediate cancellation.”
Policy changes must comply with OIR filings, and insurers must give advance written notice of endorsement alterations.
ACV reduces payouts by factoring in heavy depreciation; understand what rights you give up before signing.
3. RCV vs. ACV: The Hidden Policy Trap
Understanding how your insurance carrier calculates roof damage payouts is essential when navigating renewals and storm damage claims.
Replacement Cost Value (RCV): The insurer covers the actual cost to repair or replace the damaged roof with similar materials at current market prices, without deducting money for age or wear and tear.
Actual Cash Value (ACV): The insurer deducts depreciation based on the age and condition of the roof before issuing a payment.
If a 15-year-old roof with a 20-year lifespan suffers severe storm damage under an ACV policy, the insurer may only pay 25% of the replacement cost, leaving the homeowner responsible for the remaining 75% out-of-pocket. Pay close attention to policy renewal documents—carriers frequently attempt to slip ACV roof endorsements onto older homes during annual renewals.
4. Roof Materials & Expected Insurable Lifespans
The material covering your home dramatically influences underwriting guidelines across private carriers and state-backed insurers like Citizens Property Insurance Corporation.
Roof Material Type
Typical Industry Life
Citizens Inspection Limit
Architectural Shingle
15 to 25 Years
Inspection at 25 Years
Concrete / Clay Tile
25 to 50 Years
Inspection at 50 Years
Standing Seam Metal
30 to 50+ Years
Inspection at 50 Years
Flat / Low-Slope Membrane
10 to 15 Years
Inspection at 15 Years
Asphalt Shingle Roofs: Private carriers scrutinize shingle roofs most heavily starting at year 15. However, high-grade architectural shingles often maintain structural integrity well beyond 15 years if properly maintained.
Tile & Metal Roofs: Concrete tiles, clay tiles, and standing-seam metal roofs regularly handle South Florida wind loads for decades. Citizens Property Insurance allows tile and metal roofs to reach up to 50 years before mandatory age-based useful life documentation is triggered.
5. Step-by-Step Defense Action Plan: Responding to a Non-Renewal Notice
If an insurance company delivers a notice demanding roof replacement or threatening non-renewal in Broward, Miami-Dade, or Palm Beach County, follow this structured response plan:
ROOF INSPECTION & AUDIT PROCESS
Step 1: Audit Notice
Check stated reasons and roof age dates.
➔
Step 2: Hire Inspector
Independent 4-Point Roof Inspection.
➔
Step 3: Submit Form
Provide 5-year cert to insurance carrier.
➔
Step 4: Legal Review
Enforce statutory rights if denied.
Audit the Non-Renewal Letter: Check the exact reason cited by the carrier. If the only reason listed is that your roof is between 1 and 14 years old, the notice violates Fla. Stat. § 627.7011(5).
Order an Independent Roof Inspection: Contact a licensed Florida general contractor, building inspector, or engineer. Ask specifically for a Florida 4-Point Inspection or Roof Condition Verification Form.
Secure the 5-Year Useful Life Certification: Ensure the inspector documents that the roof has at least 5 years of remaining useful life. This written verification serves as your primary protection under state law.
Submit Formal Documentation via Certified Mail: Send the completed inspection report directly to your insurance agent and carrier. Request formal written confirmation that the non-renewal notice has been rescinded.
Consult Legal Counsel if the Carrier Refuses: If an insurer ignores state statute and refuses to accept a valid 5-year useful life certification, legal intervention may be required to protect your property rights and coverage.
6. Frequently Asked Questions
Can my insurance company drop me if my shingle roof is only 12 years old?
No. Under Florida Statute § 627.7011(5), insurance companies cannot refuse to issue or renew a homeowners insurance policy solely because of roof age if the roof is less than 15 years old.
Who qualifies as an “authorized inspector” in Florida?
Under state law, authorized inspectors include licensed general contractors, building contractors, residential contractors, professional engineers, professional architects, and certified building code inspectors.
What happens if my roof is over 15 years old but in great condition?
If an authorized inspector certifies that your 15+ year old roof has at least 5 years of remaining useful life, Florida law prevents the insurer from denying or non-renewing your coverage solely based on roof age.
Does Citizens Property Insurance follow the same roof rules?
Yes, Citizens Property Insurance must comply with Florida statutory requirements. Citizens requires documentation verifying at least 5 years of remaining useful life for shingle roofs older than 25 years and tile/metal roofs older than 50 years.
Protecting Your Property Rights Across South Florida
When insurance carriers issue arbitrary non-renewal demands, knowing the statutory rules keeps you in control. If your insurance company is threatening improper non-renewal, forcing unnecessary roof replacements, or mishandling a property damage claim, our team can help you enforce your statutory protections.
Disclaimer: The information provided in this guide is for general informational and educational purposes only and does not constitute formal legal advice. Property insurance laws and underwriting rules change frequently. Consult a qualified Florida legal professional regarding your specific situation.
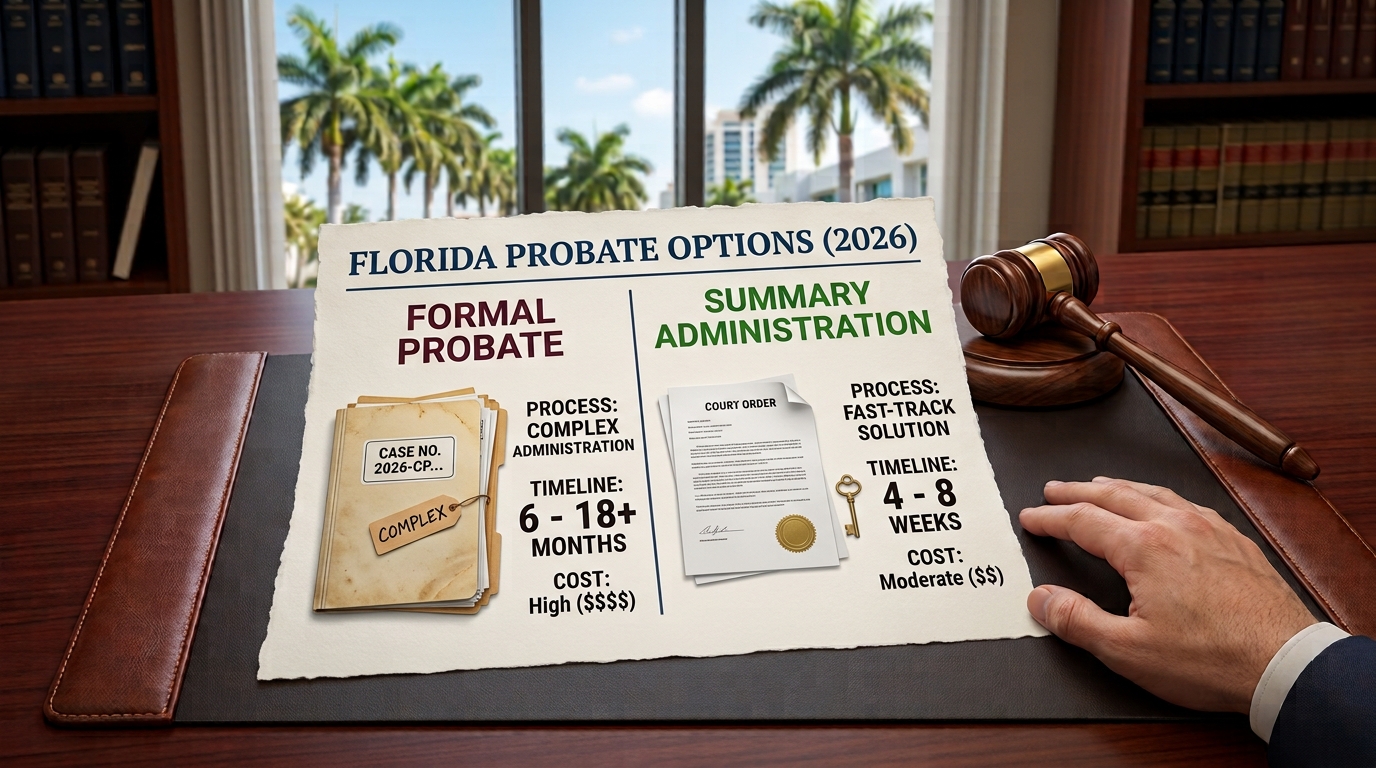
When a loved one passes away in Florida, families often assume they are facing a year-long legal battle filled with court dates, stacks of paperwork, and exorbitant administrative costs. However, under Chapter 735 of the Florida Probate Code, many families qualify for a fast-track judicial process known as Summary Administration.
Effective July 1, 2026, Florida doubled the statutory limit for small estate probate under Fla. Stat. § 735.201 from $75,000 to $150,000. This critical update allows significantly more families to distribute estate assets in a matter of weeks rather than months.
Direct Answer
What are the requirements for Summary Administration in Florida?
To qualify for Summary Administration in Florida under Fla. Stat. § 735.201, an estate must satisfy either of the following two criteria:
The $150,000 Asset Cap: The total value of non-exempt Florida probate assets is $150,000 or less (for deaths on or after July 1, 2026).
The 2-Year Rule: The decedent has been deceased for more than two years, regardless of total estate value.
Additionally, the decedent’s Last Will and Testament must not explicitly mandate Formal Estate Administration.
The Two Pathways to Qualifying for Summary Probate
Unlike Formal Administration—which requires the court to appoint a Personal Representative (Executor) and oversee a lengthy administration period—Summary Administration acts as a direct judicial order transferring assets straight to beneficiaries.
SUMMARY ADMINISTRATION QUALIFICATION
↓
Does the Estate meet EITHER rule?
↓
The $150,000 Cap
Non-Exempt Assets ≤ $150k
(Deaths Post-July 2026)
OR
2-Year Rule
Deceased > 2 Years
(No Asset Limit Cap)
1. The $150,000 Asset Limit (Non-Exempt Property)
For decedents passing on or after July 1, 2026, the estate’s total non-exempt probate assets must not exceed $150,000. (For deaths occurring prior to July 1, 2026, the statutory limit remains $75,000).
2. The Two-Year Statute of Repose Rule
If the decedent passed away more than two years ago, the estate automatically qualifies for Summary Administration, regardless of how millions of dollars the estate is worth. Under Fla. Stat. § 733.710, Florida enforces a strict two-year statute of repose that permanently bars unfiled creditor claims, removing the necessity for a formal personal representative to manage debts.
Why “On-Paper” Net Worth Misleads Most Heirs
One of the most frequent misconceptions beneficiaries encounter is assuming that if a relative owned a high-value home in South Florida, they are automatically forced into Formal Probate.
Florida law only evaluates probate assets subject to court distribution. The following major asset categories are entirely excluded from the $150,000 threshold calculation:
Florida Protected Homestead Real Estate: Under Article X, Section 4 of the Florida Constitution, a primary residence passing to a surviving spouse or lineal heirs is constitutionally protected from general creditors. Because homestead rights vest immediately upon death, the home’s value (whether $400,000 or $2,000,000) does not count toward the $150,000 limit when petitions are properly structured.
Statutory Exempt Personal Property: Under Fla. Stat. § 732.402, up to $20,000 in household furniture/furnishings and two personal motor vehicles used by the decedent are exempt from creditor claims and excluded from the asset tally.
Non-Probate Financial Transfers: Bank accounts with Payable-on-Death (POD) or Transfer-on-Death (TOD) designations, life insurance policies with named beneficiaries, jointly owned property with rights of survivorship, and assets held inside a Revocable Living Trust bypass probate entirely.
“Many families walk into our office believing they owe thousands in court fees because their parent owned a $700,000 house in Coral Springs. Once we isolate the constitutional homestead and exempt vehicles, the actual probate asset is just a $40,000 checking account—qualifying them for fast-track Summary Administration instantly.”
Real-World Case Studies: How Summary Administration Works in Practice
Case Study 1: Bypassing Formal Probate for a Broward County Home & Bank Account
Scenario: A widow in Fort Lauderdale passed away, leaving a home valued at $550,000 and a sole-name savings account containing $65,000. Her two adult children were named as equal beneficiaries in her Will.
The Legal Challenge: A traditional law firm informed the siblings they needed Formal Administration due to the $615,000 gross estate value, quoting an estimated 9-month process and thousands in hourly fees.
The RCT Solution: Our probate team filed a Petition for Determination of Homestead Property alongside aPetition for Summary Administration. Because the $550,000 home was protected homestead, its value dropped to $0 for qualification purposes. The only remaining asset was the $65,000 account—well under the statutory limit.
Outcome: The Broward County Probate Court issued an Order of Summary Administration in 5 weeks. The bank released the funds directly to the siblings, and the homestead order cleared title for them to sell the home without appointing a Personal Representative.
Case Study 2: Settling an Estate Decades Later for Out-of-State Heirs
Scenario: A father passed away in Miami-Dade County in 2018 owning an unlinked parcel of land. His heirs, living in New York, never probated the estate because they believed the process was too complex from out-of-state.
The Legal Challenge: The land grew in value to $220,000. The heirs wanted to sell the land but could not clear title without court authorization.
The RCT Solution: Because the decedent had been deceased for over two years, the estate qualified under the 2-Year Rule regardless of the $220,000 property value. We managed the entire filing remotely via Florida’s electronic court portal without requiring the heirs to travel to Florida.
Outcome: The court signed the distribution order within 4 weeks, enabling the title company to execute a seamless sale.
Detailed Comparison: Summary vs. Formal Administration
Key Feature
Summary Administration (Fla. Stat. § 735.201)
Formal Administration (Fla. Stat. Ch. 733)
Statutory Eligibility
Non-exempt assets $\le \$150,000$ OR death > 2 years ago
Estates over $\$150,000$ or complex litigation cases
Average Timeline
4 to 8 weeks
6 to 12+ months
Personal Representative
None appointed by the court
Court appoints an Executor/PR
Letters of Administration
Not issued
Issued (gives PR power to act for estate)
Primary Court Order
Order of Summary Administration
Order of Discharge
Legal Costs
Significantly lower; often structured as a Flat Fee
Higher court fees, inventory costs, and hourly rates
Frequently Asked Questions (FAQ)
Does Florida have a Small Estate Affidavit to avoid probate?
No. Florida does not recognize a standalone “Small Estate Affidavit” for transferring real estate or bank accounts like some other states do. Florida’s equivalent for small estates is Summary Administration or, for extremely small asset values under funeral costs, Disposition Without Administration (Fla. Stat. § 735.301).
What happens to outstanding creditor debts in Summary Administration?
Because no Personal Representative is appointed to manage estate claims, beneficiaries who receive assets through Summary Administration remain personally liable for valid debts of the decedent up to the dollar value of what they inherited. To eliminate this risk, a probate attorney can publish an optional Notice to Creditors in a local South Florida newspaper, initiating a 30-day window that permanently bars unfiled claims.
Can an out-of-state beneficiary file for Summary Administration in Florida?
Yes. Florida probate courts utilize 100% digital filing systems. Out-of-state heirs in New York, New Jersey, or anywhere across the country can hire a local Florida probate lawyer to execute the entire proceeding remotely without ever stepping foot inside a courtroom.
How long does it take to get an Order of Summary Administration?
In South Florida courts (Broward, Miami-Dade, and Palm Beach counties), an uncontested Petition for Summary Administration typically takes 4 to 8 weeks from initial filing to final judge signature, depending on judicial caseloads.
Why Choose Reinfeld & Cabrera, P.A. for South Florida Probate?
Navigating court petitions while grieving a family member can feel overwhelming. At Reinfeld & Cabrera, P.A. (mypersonalattorneys.com), we simplify the Florida probate process with transparency and local courtroom experience:
Transparent Flat-Fee Pricing: We eliminate financial anxiety by offering predictable flat legal fees for uncontested Summary Administration—no hidden hourly bills.
Bilingual Legal Representation: Our attorneys and staff speak fluent English and Spanish, ensuring clear communication for non-English speaking beneficiaries.
Full-Service Local Filings: We handle all court communication across Broward (17th Judicial Circuit), Miami-Dade (11th Judicial Circuit), and Palm Beach (15th Judicial Circuit) counties.
If you need to transfer real estate, recover frozen bank accounts, or resolve an estate in South Florida, contact Reinfeld & Cabrera, P.A. today for a free case evaluation.
Direct Phone: (954) 334-1520 / (855) 529-7123
Coral Springs Office: 9625 W. Sample Rd, Coral Springs, FL 33065
If you believe someone has misused a financial power of attorney in Florida, there are legal ways to challenge what happened. Depending on the circumstances, a court may review the agent’s conduct, require an accounting, remove the agent, terminate the agent’s authority, or order other relief.
Usually, though, nobody starts with a lawsuit.
It starts with a bank statement.
A parent gave a son or daughter power of attorney to handle the bills. An elderly relative needed someone to manage investments. Everything seemed ordinary until a family member noticed a withdrawal that did not make sense.
Then there is another one.
Maybe money went to the agent. Perhaps a house was sold. Maybe someone suddenly has a very good explanation for why several thousand dollars disappeared.
The uncomfortable part is that having power of attorney does give someone real authority. The document may allow an agent to handle bank accounts, investments, real estate, and other financial matters. But that authority comes with legal duties, and the agent has to stay within the authority the principal actually granted.
So what happens when the numbers stop making sense?
The answer usually starts with the power of attorney itself, the agent’s actions, and the financial records showing what happened to the principal’s money.
What Is a Financial Power of Attorney?
A power of attorney allows one person, called the principal, to authorize another person, called the agent, to act on the principal’s behalf.
The authority can be broad or limited. Depending on the document, an agent may be able to handle bank accounts, investments, contracts, real estate, or other financial matters.
Florida law generally limits an agent to the authority actually granted in the power of attorney. A broad statement saying that the agent can perform every act the principal could perform does not automatically create every possible specific power under the statute. Certain powers require separate, signed authorization.
That detail can become extremely important when a family disputes a transaction.
The document itself has to be examined.
What Does Financial Power of Attorney Abuse Look Like?
There is no single transaction that automatically proves abuse.
An agent might legitimately withdraw money to pay the principal’s mortgage. The same type of withdrawal could become a serious problem if the money goes toward the agent’s own mortgage.
Warning signs can include:
Unexplained withdrawals from bank or investment accounts
Transfers to the agent or the agent’s relatives
Personal expenses paid from the principal’s accounts
Property transferred or sold for the agent’s benefit
Large gifts that do not fit the principal’s history or instructions
Financial accounts being changed without a clear explanation
Missing receipts or financial records
Transactions occurring after the power of attorney was revoked
The records matter.
Florida requires an agent to keep records of transactions made on behalf of the principal, and the Florida Bar notes that an agent may be required to provide an accounting.
“A power of attorney gives someone authority to act for another person. It does not give that person ownership of the principal’s money.”
Can a Power of Attorney Agent Take Money From the Principal?
An agent can use the principal’s money when the transaction is authorized and consistent with the agent’s legal duties.
The agent cannot simply treat the principal’s checking account as a second personal account.
Florida law describes the agent as a fiduciary. The agent generally must act loyally for the sole benefit of the principal, avoid conflicts that interfere with impartial decision-making, and exercise the care, competence, and diligence ordinarily expected in similar circumstances.
Consider a simple example.
A daughter has power of attorney for her father. She uses his account to pay his property taxes, medical bills, insurance, and other expenses. Those transactions may be entirely appropriate.
Then she transfers $50,000 to herself and says, “Dad wanted me to have it.”
That raises a very different set of questions.
Was the gift authorized?
Did the power of attorney contain the necessary authority?
Was the transaction consistent with the father’s known wishes?
Did the agent have a conflict of interest?
What records exist?
A court looking at a disputed transaction may need to answer those questions rather than simply deciding whether money changed hands.
Can a Power of Attorney Agent Use the Principal’s Property?
Real estate can create especially complicated disputes.
Florida law allows a power of attorney to grant authority to convey or mortgage homestead property, but the applicable formalities and statutory requirements matter. The Florida Bar likewise explains that an agent may sell a principal’s home when the power of attorney satisfies the applicable requirements and grants the necessary authority.
Suppose an agent sells a property and deposits the proceeds into an account belonging to the principal. That may be an ordinary transaction.
Suppose the proceeds instead end up financing the agent’s own house.
Now the transaction deserves serious scrutiny.
The same problem can arise when an agent uses the principal’s money to purchase property that is titled in the agent’s name.
A Broward County case shows how messy this can become
In Sacco-Martin v. Romano, decided by Florida’s Fourth District Court of Appeal in August 2025, elderly parents had granted powers of attorney to their daughter and her husband in 2019 and 2020. They revoked those powers of attorney in May 2021. A subsequent guardian alleged that the former agents had nevertheless exercised control over the parents’ financial accounts and transferred hundreds of thousands of dollars.
The probate court ordered an accounting covering the period during which the agents had acted under the powers of attorney. It reviewed bank statements and testimony and ultimately ordered the former agents to return substantial funds to the guardianship estate.
The Fourth DCA affirmed most of that ruling. It did, however, reverse one $20,000 portion because the particular transfer occurred before the relevant power of attorney period and therefore fell outside the accounting period established by the probate court.
The case also involved two properties purchased with the parents’ money. One was purchased with more than $562,000 transferred from the parents’ account and titled in the parents’ names. The property was later sold. Another property was purchased around the same time, with questions about whether the parents’ money ultimately funded the purchase and why that property was titled in the former agents’ names.
That is a useful lesson in how these disputes actually develop.
The question may begin with, “Where did the money go?”
It can eventually become a dispute involving bank records, property titles, closing statements, accounting periods, alleged gifts, and the scope of the agent’s authority.
Can a Court Remove a Power of Attorney Agent in Florida?
Yes.
Florida Statutes §709.2116 allows a court to construe or enforce a power of attorney, review an agent’s conduct, terminate the agent’s authority, remove the agent, and grant other appropriate relief.
The statute also identifies people who may petition the court. They include the principal or agent, certain fiduciaries, a person authorized to make health care decisions in specified circumstances, and another interested person who can demonstrate an interest in the principal’s welfare and a good-faith belief that court intervention is necessary.
That can matter when the principal is no longer capable of handling the dispute personally.
It also means that a family disagreement does not automatically give every relative the right to take over the situation. Standing, the principal’s circumstances, the agent’s conduct, and the available evidence all matter.
Can You Force a Power of Attorney Agent to Provide an Accounting?
Potentially, yes.
Financial records are often central to a dispute over an agent’s conduct. Florida law requires an agent to maintain records of receipts, disbursements, and transactions made for the principal. The Florida Bar likewise advises agents to maintain careful records and explains that an agent may be required to provide an accounting.
An accounting can help answer basic but important questions:
What money came into the account?
What money went out?
Who received it?
What was the payment for?
Was the transaction authorized?
Was the principal’s money used for the principal’s benefit?
Sometimes the accounting clears things up.
Sometimes it creates several new questions.
What Evidence Can Help Prove Power of Attorney Abuse?
If you suspect that a financial power of attorney has been misused, preserve the records before they disappear into the digital equivalent of a junk drawer.
Useful evidence can include:
The original power of attorney and any amendments
Bank and investment statements
Canceled checks
Wire transfer records
Deeds
Closing statements
Tax records
Credit card statements
Receipts
Emails and text messages
Communications with banks or financial institutions
Records showing the principal’s usual financial practices
Documents concerning the principal’s estate plan
The power of attorney itself is especially important.
A transaction can look suspicious until the document reveals that the agent had express authority to perform it. The opposite can also happen: a transaction can look ordinary until the document shows that the agent lacked the authority to make it.
What If the Principal Is Still Capable?
If the principal still has the legal capacity to make financial decisions, the situation may be different from one involving a principal who can no longer manage their affairs.
Florida law provides for revocation of a power of attorney, and a principal who remains capable may be able to revoke the existing authority and appoint another agent. The details depend on the circumstances and the document.
When there are already disputed transactions, however, changing the agent may be only one part of the problem.
There may also be questions about money already transferred, property already sold, or records that have not been provided.
What Happens to a Financial Power of Attorney After Death?
A power of attorney generally terminates when the principal dies. Florida’s statute expressly provides that the principal’s death terminates the power of attorney.
That does not erase transactions that happened while the principal was alive.
If family members believe an agent misused the principal’s property before death, those transactions can become relevant to an estate or probate dispute.
The legal framework then shifts. The personal representative or another person with appropriate authority may need to investigate what happened to the deceased person’s assets.
This is one reason a power of attorney dispute can eventually become a probate matter.
How Common Is Financial Exploitation?
Power of attorney abuse sits within a much larger financial exploitation problem.
The Administration for Community Living reported that older Americans lost nearly $2.4 billion to fraud in 2024, up from $1.9 billion in 2023. The agency also cautioned that reported fraud represents only part of the actual harm because many incidents go unreported.
The numbers cover fraud generally, not power of attorney abuse specifically.
But the broader pattern is relevant. Financial exploitation can occur within relationships of trust, including relationships involving family members, caregivers, and other people who have access to an older person’s finances.
A South Florida federal case illustrates how severe one of these situations can become.
In 2025, federal prosecutors sentenced former financier Brett Thomas Graham to seven years in prison after he admitted defrauding an elderly family member of approximately $8.4 million. According to the U.S. Attorney’s Office, Graham later became the woman’s power of attorney and was obligated to act in her best interest while continuing to divert money for his own expenses.
That is an extreme case.
Most power of attorney disputes will not involve $8.4 million, federal wire fraud charges, or a seven-year prison sentence.
The underlying problem can be much smaller and still be devastating to a family.
What Can Families Do About Power of Attorney Abuse?
Start with the document and the records.
Find out what authority the principal actually granted. Identify the transactions that are causing concern. Gather the financial records. Establish when the transactions occurred. Determine whether the power of attorney was still effective.
Then ask the uncomfortable questions.
Was the transaction authorized?
Was it for the principal’s benefit?
Did the agent personally benefit?
Was there a gift?
Was there a conflict of interest?
Can the agent account for the money?
Those questions are far more useful than simply asking whether someone in the family “did something shady.”
And sometimes the records show that the agent acted properly.
That possibility deserves to be taken seriously too.
“Financial disputes between relatives can become emotional very quickly. The documents give everyone something concrete to examine.”
Power of Attorney Disputes in Coral Springs and Broward County
For families in Coral Springs and throughout Broward County, a financial power of attorney dispute may overlap with probate, guardianship, estate litigation, real estate, or financial exploitation proceedings.
Broward County’s Probate and Guardianship Division handles probate and guardianship matters through the Seventeenth Judicial Circuit. The county also provides procedures and resources for matters involving vulnerable adult exploitation, guardianship accountings, probate filings, and related proceedings.
That local connection matters when a dispute moves from a family disagreement into a court proceeding.
A court may be asked to review the agent’s conduct, terminate the agent’s authority, remove the agent, order an accounting, or provide another appropriate remedy under Florida law.
Frequently Asked Questions
What is a financial power of attorney in Florida?
A financial power of attorney allows a principal to authorize an agent to handle specified financial or property matters. The agent’s authority depends on the language of the document and Florida law.
Can a power of attorney agent take money from the principal?
An agent may use the principal’s money when authorized and when acting consistently with the agent’s fiduciary duties. An agent cannot simply treat the principal’s assets as personal property.
How do you prove power of attorney abuse?
Evidence can include the power of attorney itself, bank records, transfers, property records, closing documents, receipts, communications, and other evidence showing what authority the agent had and what the agent actually did.
Could a power of attorney agent be removed in Florida?
Yes. Florida law allows a court to review an agent’s conduct, terminate the agent’s authority, remove the agent, and grant other appropriate relief.
Can a family member challenge a power of attorney agent?
Potentially. Florida law permits certain interested persons to petition the court when they meet the statutory requirements for intervention. A family relationship by itself does not determine whether someone has standing.
Can a power of attorney agent be required to provide an accounting?
An agent has a statutory duty to keep records of receipts, disbursements, and transactions made for the principal, and an accounting may be required in appropriate circumstances.
What happens to a power of attorney after the principal dies?
The power of attorney terminates when the principal dies. Transactions carried out before death can still become relevant to a later probate or estate dispute.
When a Financial Power of Attorney Goes Wrong
A financial power of attorney is built on a simple arrangement: one person gives another person authority to handle matters the principal cannot or does not want to handle personally.
Most of the time, that arrangement exists because someone needs help.
When the relationship breaks down, the family may be left reconstructing months or years of financial decisions while trying to determine who has the legal authority to do something about them.
That is why the document, the financial records, the agent’s conduct, and the principal’s circumstances all need to be examined together.
When you walk into your kitchen, grab a cup of coffee, and find a foreclosure notice sitting right next to the toaster, the panic hits you square in the chest.
How on earth did things get this far, and is there any actual, realistic way to save your home before the bank schedules a fire sale on the courthouse steps?
Quick Answer: Under Florida law, a judicial foreclosure typically takes 6 to 14 months to complete, providing homeowners with a vital legal window to pursue loss mitigation options like a Fannie Mae Flex Modification or file a formal defense. Under federal RESPA rules (12 C.F.R. § 1024.41), mortgage servicers are strictly prohibited from dual tracking a foreclosure while a complete loan modification application is under review.
If you wander onto the internet looking for mortgage relief, you will trip over old blog posts, expired federal initiatives from decades past, or blanket quick fixes that vanished years ago. Relying on outdated internet advice or waiting around for a government bailout program that no longer exists is a marvelous way to lose your property while wondering what went wrong.
So what options do Florida homeowners actually have right now when facing default, past due mortgage payments, or a looming court summons in the 17th Judicial Circuit? Let us break down how modern loan modifications, loss mitigation, and active foreclosure defenses work in today’s real estate market without any corporate mumbo jumbo.
Why Modern Loss Mitigation Replaced One Size Fits All Federal Programs
When banks initiate foreclosure proceedings in Florida, they move through a strict, formal judicial process. Older programs like HAMP dictated a rigid federal template, but today mortgage servicing relies on standardized corporate guidelines and portfolio specific workouts.
Modern foreclosure defense requires looking at your current financial snapshot and choosing an active legal path:
Standardized Lender Modifications: Major loan servicers and government backed entities like Fannie Mae and Freddie Mac utilize structured programs—such as the Flex Modification—to lower monthly payments by extending loan terms up to 40 years, capitalizing missed arrears, or adjusting interest rates.
Chapter 13 Bankruptcy Protection: For homeowners with steady income facing an imminent foreclosure auction, filing a Chapter 13 plan can halt the bank instantly, giving you a court approved safety net to catch up on mortgage arrears over three to five years.
Strategic Loss Mitigation & Short Sales: If staying in the home is no longer financially viable, a managed exit strategy protects your overall credit profile and helps avoid a predatory deficiency judgment.
How Modern Loan Modifications Work With Your Lender
Securing a permanent loan modification requires navigating a structured underwriting review with your loan servicer.
Ask yourself: Does my current monthly income realistically support a restructured payment if the bank agrees to stretch out the loan term or lower the interest rate?
To qualify for a modern in-house or agency backed loan modification, your servicer will typically look for three key criteria:
Proof of Stable Income: Verifying that you have sufficient monthly earnings through pay stubs, profit and loss statements, or tax documents to support a modified payment structure.
Primary Residence Verification: Demonstrating that the property is your primary home rather than an unmanaged investment portfolio asset.
Financial Hardship Documentation: Providing a signed hardship affidavit explaining the life event—such as a medical emergency, job change, or temporary income reduction—that caused you to fall behind.
Avoiding Dual Tracking and Protecting Your Rights Under Federal Servicing Rules
When dealing with mortgage default or foreclosure in Florida, many homeowners worry that submitting a loan modification application will cause the bank to quietly move forward with a foreclosure judgment behind their backs.
What safeguards actually prevent lenders from rushing an auction while your loss mitigation paperwork is sitting on an underwriter desk?
Under federal regulations governed by the Consumer Financial Protection Bureau (12 C.F.R. § 1024.41), mortgage servicers are strictly prohibited from engaging in dual tracking. Dual tracking occurs when a lender simultaneously processes a foreclosure lawsuit while a complete loss mitigation or modification application is actively under review.
Critical Protection Milestones for Florida Borrowers
The 120 Day Rule: Under federal rules, a mortgage servicer generally cannot officially file a judicial foreclosure complaint in court until a borrower is more than 120 days delinquent on payments. This window gives homeowners ample time to submit an initial loss mitigation package.
The Evaluation Freeze: If you submit a complete modification application before the bank makes its first official foreclosure filing or moves for a judgment, the servicer cannot move for foreclosure judgment or conduct a judicial sale until they have formally evaluated your application and provided you with written notice of their decision.
The Right to Appeal: If a servicer denies a modification, federal guidelines often provide a 14 day window to appeal the decision if the application was submitted at least 90 days before a scheduled sale date.
If a lender or bank servicer violates these federal protections or mishandles your paperwork while operating in local courts like the 17th Judicial Circuit in Broward County, an experienced foreclosure defense attorney can leverage these violations to halt the lawsuit, challenge the bank’s standing under Fla. Stat. § 702.015, and force the lender back to the negotiating table.
Real-World Case Example: Stopping Dual Tracking in Broward County
Consider a case our firm handled where a Broward County homeowner inherited a residential property after a family member passed away. The mortgage servicer quickly initiated a foreclosure action in the 17th Judicial Circuit. To make matters worse, the bank mishandled the estate transfer documents and loss mitigation paperwork, attempting to rush a foreclosure judgment while the surviving family member was trying to secure a loan modification.
How Our Legal Team Resolved the Case
Challenging Standing: We filed formal defenses requiring the bank to prove proper legal standing under Florida law.
Stopping Dual Tracking: We enforced federal rules under 12 C.F.R. § 1024.41 to halt the foreclosure sale while the modification paperwork was under review.
Securing the Result: The active defense forced the lender to stop the rushed timeline and approve a permanent solution that allowed the family to keep their home.
Frequently Asked Questions About Florida Foreclosures
Can I fight a foreclosure lawsuit while simultaneously applying for a loan modification?
Yes. Under Florida law and federal mortgage servicing rules, working with your lender on loss mitigation options does not mean you should ignore a pending lawsuit. Having a defense attorney file a formal answer in court protects you from a default judgment while your modification application is actively being reviewed.
What happens if the bank wrongfully denies my loan modification request?
If a servicer improperly denies your modification or violates federal RESPA (Real Estate Settlement Procedures Act) guidelines by dual tracking your file while a complete modification application is pending, a real estate litigation attorney can hold them accountable in court.
How long does the judicial foreclosure process take in Florida?
Because Florida is a strict judicial foreclosure state, lenders cannot seize property without filing a formal lawsuit in circuit court. On average, an uncontested or contested foreclosure timeline spans anywhere from 6 to 14 months, providing a critical window to evaluate defense options, pursue loss mitigation, or negotiate with the bank.
What is a Fannie Mae or Freddie Mac Flex Modification?
The Flex Modification is a standardized loss mitigation program used for government backed conventional loans. It is designed to achieve a target reduction in monthly principal and interest payments by capitalizing delinquent amounts, lowering interest rates, or extending the loan maturity term up to 480 months.
Does filing for bankruptcy stop a scheduled foreclosure sale in Broward County?
Yes. The moment a Chapter 13 or Chapter 7 bankruptcy petition is filed, an automatic stay goes into effect under federal law. This injunction immediately halts all collection efforts, creditor calls, and scheduled foreclosure sales governed by the 17th Judicial Circuit in Broward County, giving you breathing room to reorganize your debts.
Can a lender proceed with foreclosure if I never received a default notice?
Lenders must comply with strict contractual notice conditions precedent outlined in standard mortgage agreements, typically requiring a formal notice of default and intent to accelerate thirty days prior to filing a lawsuit. If the bank failed to provide proper statutory or contractual notice, a defense attorney can leverage this error to dismiss or delay the foreclosure action.
Protect Your Home and Your Financial Future
Facing foreclosure alone is a risk you should not take. Whether your goal is to restructure your loan, fight the bank standing in court, or execute a graceful exit strategy to preserve your credit, you need a localized game plan.
The foreclosure defense attorneys at Reinfeld & Cabrera P.A. help homeowners across South Florida navigate complex lender disputes, evaluate modification alternatives, and protect their rights.
Schedule a Confidential Foreclosure Consultation
Do not wait until a sale date is scheduled. Speak directly with an attorney today to review your options:
Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
Website: mypersonalattorneys.com
Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all surrounding communities across Broward, Miami Dade, and Palm Beach Counties.
If you manage or own rental property in South Florida, tenant turnovers and the occasional eviction are bound to happen. But here is the catch: when a lease ends or a tenant vacates under court order, how you handle their security deposit can make or break your legal standing.
Can you simply keep the deposit to cover unpaid rent or property damage? Not without following Florida procedural rules to the letter. Missing a statutory deadline or skipping a certified letter notice can strip away your legal right to hold those funds even if the tenant destroyed your floors or walked out owing months of rent.
So how does Fla. Stat. § 83.49 actually work when you are standing inside an empty unit staring at ruined drywall? What concrete steps must you take right now to protect your bottom line, and how can you keep yourself far away from costly disputes in local South Florida courtrooms? Let us break down everything you need to navigate move outs safely.
What Are Florida Security Deposit Notice Deadlines?
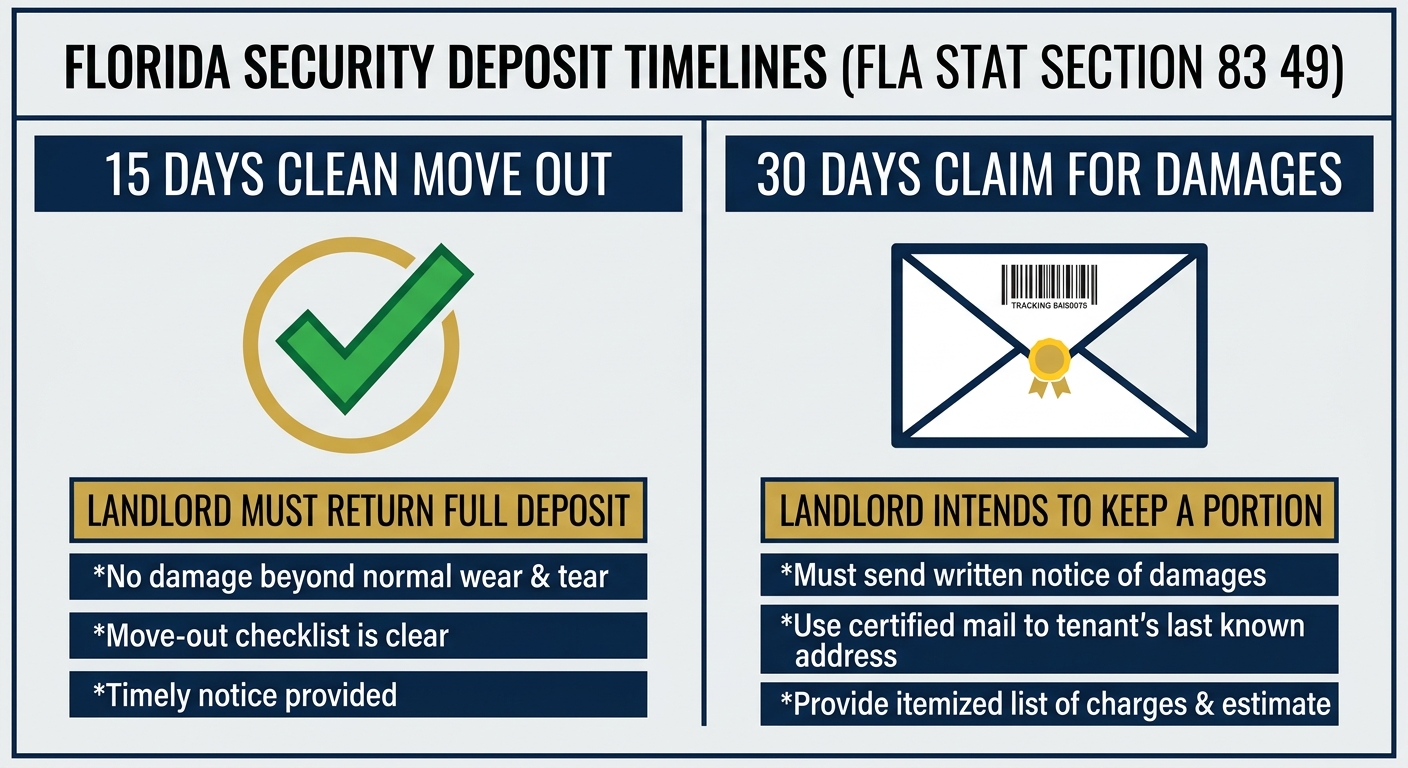
Quick Answer: Under Fla. Stat. § 83.49, Florida landlords have 15 days to return a security deposit in full if no deductions are being made. However, if you are claiming money for property damage, deep cleaning, or unpaid rent, you have 30 days to send an itemized claim via Certified Mail to the tenant last known address. If you fail to send this notice within 30 days, you legally forfeit your right to claim any part of the deposit.
The Core Rule: 15 Days vs 30 Days
Why do so many property owners get tripped up by Florida security deposit timelines? Usually, it comes down to confusing a clean turnover with a damage claim. You might ask yourself: Am I simply handing back their money, or am I preparing to fight for repair costs? The law divides move outs into two distinct paths:
No Claim on Deposit (15 Days): Timeline is 15 days from move out. Action requires a full refund plus accrued interest if held in an interest account. Target is clean turnovers.
Imposing a Claim (30 Days): Timeline is 30 days from move out. Action requires sending an itemized claim via Certified Mail containing required statutory text. Target covers physical damage, back rent, or unpaid utility fees.
1. The Clean Turnover (15 Day Window)
Suppose your tenant moves out, hands over the keys, and leaves the home in excellent shape with zero unpaid rent. Under Fla. Stat. § 83.49(3)(a), you have exactly 15 days from the date they vacate to return their full deposit along with any accrued interest if kept in an interest bearing account.
2. The Damage or Back Rent Claim (30 Day Window)
Now, what if you walk into the property and find broken drywall, ruined carpets, or an unpaid utility balance? Would a quick text message or an informal email suffice to let them know you are withholding funds? Absolutely not.
In this scenario, you have 30 days to issue a formal written notice detailing your intent to keep part or all of the deposit. Florida law strictly mandates that this notice must be sent by Certified Mail to the tenant forwarding address or last known mailing address. I often tell property owners to treat that certified mail receipt like pure gold because without it, proving you met your 30 day clock becomes nearly impossible.
What Happens if You Skip the Statutory Warning Language?
Here is a detail that continuously catches self managing landlords off guard: it is never enough to write a quick note stating, “I am keeping $500 for carpet repairs.”
Florida statute explicitly mandates that your notice include specific statutory warning language informing the tenant of their right to object within 15 days.What actually happens if you leave this mandatory wording out? Legally, the entire notice becomes invalid. That means you forfeit your right to retain the deposit and could end up paying the tenant legal fees under Fla. Stat. § 83.48 if they retain an attorney to contest your error.
I always think: Why risk losing thousands over a missed paragraph when the statute gives you the exact script to copy?
The 15 Day Tenant Objection Clock
Once the tenant receives your certified letter, the ball moves directly into their court:
If they do not object within 15 days: You are legally authorized to deduct the claimed amount from the deposit and return any remaining balance to them within 30 days of the original notice date.
If they object in writing: You now have a formal legal dispute on your hands. If that disagreement escalates into county court in Broward, Miami Dade, or Palm Beach County, a judge will review whether every single statutory notice rule was meticulously followed.
What Counts as Legitimate Deductions vs Normal Wear and Tear?
One of the most frequent friction points between landlords and departing tenants is deciding what damage justifies keeping deposit funds.
Before you start writing up your itemized bill, ask yourself: Is this issue the natural result of everyday human living, or does it represent actual property destruction and tenant negligence?
Permissible Deductions (Tenant Damage)
Unpaid rent, fees, or utility balances
Holes in drywall, broken doors, or cracked floor tiles
Pet damage such as scratched doors, carpet stains, or deep odors
Trash removal and heavy cleaning charges for abandoned personal property
Impermissible Deductions (Normal Wear and Tear)
Faded wall paint or small nail holes from picture frames
Minor carpet wear or light scuffs along high traffic hallways
Aging, worn door handles or standard cabinet hinges
Routine HVAC filter servicing or standard dust accumulation
Frequently Asked Questions for Florida Landlords
What if I completely miss the 30 day Certified Mail deadline?
If you miss the 30 day window, you automatically forfeit your right to retain the security deposit under Fla. Stat. § 83.49, meaning you must return 100 percent of the money to the tenant. Does this mean you are completely out of options if they wrecked your rental property? Not entirely. Missing the deposit deadline prevents you from holding onto their deposit money, but it does not prevent you from filing a separate lawsuit against the former tenant in court for breach of contract or physical property damage.
Does winning an eviction judgment mean I can automatically keep the deposit?
Surprisingly, no. Even if you secure a writ of possession in the 17th Judicial Circuit Court of Broward County, you remain legally bound to send the 30 day certified claim notice if you intend to apply the security deposit toward back rent or damages caused by the evicted tenant. I see landlords fall into this exact trap all the time assuming an eviction order wipes out their security deposit duties.
Can I include a clause in my lease waiving these notice rules?
No. Florida courts treat Fla. Stat. § 83.49 as a mandatory protection statute. Any clause inside a residential rental agreement that attempts to bypass, shorten, or alter these statutory notice timelines is considered legally null and void.
Protect Your Real Estate Investments with Legal Counsel
Whether you manage a single rental home in Coral Springs or an apartment complex in Fort Lauderdale, administrative slip ups during tenant move outs can cost you thousands in lost funds and legal fee awards.
The real estate litigation team at Reinfeld & Cabrera P.A.helps South Florida landlords, investors, and property managers enforce lease agreements, execute formal evictions, and navigate security deposit compliance smoothly.
Schedule a Property Law Consultation
Facing a tenant dispute or need assistance structuring legally compliant lease agreements? Speak directly with a South Florida real estate attorney today:
Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
Website: mypersonalattorneys.com
Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and surrounding communities across Broward, Miami Dade, and Palm Beach Counties.
A Lady Bird Deed in Florida is an enhanced life estate deed that allows a property owner to name someone who will receive the property after the owner’s death while retaining broad control over the property during life.
Unlike a traditional life estate, a properly drafted Lady Bird Deed can allow the owner to sell, mortgage, or otherwise convey the property without the future beneficiary’s permission. It can also allow the property to pass outside the ordinary probate process.
Because Florida does not have a statutory form called a “Lady Bird Deed,” the language used in the deed is especially important.
How Does It Work?
The property owner transfers the property through a deed that reserves an enhanced life estate and identifies one or more people who are intended to receive the property after the owner’s death.
During the owner’s lifetime, the owner generally retains the right to:
Live in and use the property
Sell the property
Mortgage the property
Convey the property to someone else
Change or defeat the beneficiary’s future interest, depending on the deed’s language
If the owner dies while the deed remains effective, the property can pass to the designated beneficiary without becoming part of the owner’s probate estate.
The exact result depends on the language of the deed and the circumstances surrounding the property.
Lady Bird Deed vs. a Regular Life Estate
The most important difference is the amount of control retained by the original owner.
With a traditional life estate, the owner keeps the right to possess and use the property for life but gives another person a present remainder interest. Selling or mortgaging the entire property can therefore require the remainderman’s participation.
An enhanced life estate, by contrast, can reserve the owner’s power to sell, mortgage, or convey the property without the beneficiary joining the transaction.
Florida courts have recognized this distinction. In Hirschenson v. Compu-Link Corp. of MI, the Third District Court of Appeal discussed an enhanced life estate as allowing the holder to sell, convey, mortgage, and otherwise manage the property without the remainderman’s joinder.
Does It Avoid Probate?
One reason Florida property owners consider this type of deed is probate avoidance.
If the deed is properly executed and remains effective when the owner dies, the designated beneficiary can receive the property without the real estate passing through the owner’s ordinary probate estate.
That does not mean every Lady Bird Deed will accomplish the same result. The deed must be legally effective, the property’s ownership must be correctly identified, and other Florida property laws may affect the transfer.
Why the Deed’s Language Matters
The enhanced powers need to be clearly established in the deed.
A Florida appellate case illustrates what can happen when the language is unclear. In Hirschenson, the deed contained inconsistent language concerning the power to mortgage the property. The resulting dispute required the court to determine what the deed actually meant, and the trial court ultimately reformed the deed. The appellate court affirmed that decision.
This is why a Lady Bird Deed should not simply be copied from an unidentified online form.
Can You Sell or Mortgage the Property?
A properly drafted enhanced life estate deed can preserve the owner’s ability to sell or mortgage the property without obtaining the future beneficiary’s consent.
That retained control is one of the defining characteristics of the arrangement.
However, the specific deed should be reviewed before a sale or mortgage. The deed’s wording, the property’s current title, and the requirements of the lender or title company can all matter.
What If the Beneficiary Dies First?
This depends on how the deed was drafted.
If the named beneficiary dies before the property owner, the deed should be reviewed to determine what happens to that person’s future interest. The owner may want to name alternate beneficiaries or include other provisions addressing this possibility.
This is one reason the beneficiary provisions should be considered carefully when the deed is prepared.
What If the Property Is Florida Homestead?
Homestead property requires additional care.
Florida law places special restrictions on the disposition of homestead, particularly when the owner has a spouse or minor children. Sections 732.4015 and 732.4017 of the Florida Statutes address important rules concerning homestead and lifetime transfers.
A Lady Bird Deed involving a Florida homestead therefore should not be evaluated solely on whether it can avoid probate. The owner’s family situation, title, and homestead status should all be considered before the deed is prepared.
Who Actually Owns the Property?
Before preparing the deed, it is important to determine how the property is currently titled.
For example, the property may be owned individually, jointly, through a trust, or subject to an existing interest.
In Johnson v. Johnson, Florida’s First District Court of Appeal considered enhanced life estate deeds that had been prepared in an individual’s name even though the properties were actually held by a living trust. The court affirmed reformation of the deeds based on the evidence concerning the mistake.
The practical lesson is simple: the current deed and ownership records should be checked before preparing a new conveyance.
When Might a Lady Bird Deed Be Useful?
A Florida property owner may consider an enhanced life estate deed when the goal is to:
Retain control of the property during life
Continue living in the property
Designate who should receive it after death
Preserve the ability to sell or mortgage the property
Potentially transfer the property outside probate
It may not be appropriate for every estate plan. More complicated family circumstances, multiple properties, trusts, creditor issues, or other planning concerns may call for a different approach.
It is an enhanced life estate deed that allows a property owner to retain substantial control over real estate while designating who should receive the property after the owner’s death.
Does a Lady Bird Deed avoid probate?
A properly drafted and effective deed can allow the property to pass to the designated beneficiary outside the ordinary probate process.
Is a Lady Bird Deed the same as a life estate?
No. A Lady Bird Deed is an enhanced form of life estate that can reserve significantly greater powers for the original owner.
Can I sell my house after signing a Lady Bird Deed?
Generally, an enhanced life estate can preserve the owner’s power to sell or convey the property without the beneficiary’s consent. The specific deed should be reviewed to confirm the powers it reserves.
Can I mortgage property with a Lady Bird Deed?
A properly drafted deed can reserve the owner’s power to mortgage the property. The exact language matters.
What happens when the owner dies?
If the deed remains effective and the property has not otherwise been conveyed, the designated beneficiary can receive the property according to the deed’s terms, potentially without probate.
Does a Lady Bird Deed work for Florida homestead?
It can, but Florida’s homestead rules create additional considerations involving spouses, minor children, and the owner’s particular circumstances.
Florida Estate Planning Attorneys Serving South Florida
A Lady Bird Deed can be a useful way to plan for the future of Florida real estate while retaining control during life. But the deed needs to match the property’s title and the owner’s circumstances.
Florida does not require every homebuyer to hire an attorney, but legal review can be valuable before signing a purchase contract. A real estate attorney can identify contractual, title, ownership, and closing issues that may affect your rights as a buyer.
For a home purchase in Coral Springs or elsewhere in Broward County, the legal review may involve:
Title: Examining the ownership history and identifying liens, judgments, probate issues, defective deeds, easements, or other recorded interests.
Deed and ownership: Determining how the property will be titled and whether the proposed ownership structure fits the buyer’s circumstances.
Closing: Reviewing documents and addressing unresolved legal issues before ownership transfers.
Florida homestead: Evaluating homestead considerations when the property will be the buyer’s primary residence.
Estate planning: Considering how the new property fits into the buyer’s will, trust, and broader estate plan.
Probate: Identifying potential probate issues when the property was inherited or when its future transfer may involve an estate.
The timing of the legal review matters. A lawyer who examines the transaction before the purchase contract is signed may be able to identify provisions that become difficult to change later. Title and ownership issues should also be addressed before closing, when resolving them can become more complicated.
For buyers in Coral Springs and Broward County, these questions arise under Florida real estate law, but the appropriate legal strategy depends on the specific property, contract, ownership structure, and family circumstances.
When should you hire a real estate attorney?
Many buyers think about hiring a lawyer when they reach the closing table. By that point, the most important contractual decisions may already have been made.
The purchase contract establishes the legal framework for the transaction. It can determine the buyer’s rights concerning financing, inspections, repairs, deposits, title, closing dates, and termination.
The Florida Bar recommends consulting an experienced Florida real estate lawyer before signing a purchase contract. Its consumer guidance explains that important provisions can become difficult to change once the agreement has been signed.
That timing matters whether you are buying a home in Coral Springs, Fort Lauderdale, Parkland, Coconut Creek, or another Broward County community.
Suppose an inspection later reveals substantial roof damage. The buyer may want the seller to make repairs or provide a credit. Whether the buyer can demand either remedy depends on the contract and the circumstances surrounding the transaction.
The same principle applies to financing problems, delays, title defects, and disputes about property condition.
A lawyer who reviews the agreement before signature can explain what the buyer has agreed to and identify provisions that deserve attention.
What does a real estate attorney do for a homebuyer?
The work depends on the transaction.
A real estate attorney may review the purchase agreement, examine title records, review the deed, address liens and judgments, examine closing documents, advise on ownership, and represent the buyer if a dispute develops.
Some transactions require little legal intervention after the contract and title are reviewed. Others become complicated because of the property’s history.
A house in Broward County may have changed hands several times. A previous owner may have died. A divorce may have affected ownership. An old mortgage may remain in the public record. A judgment may have attached to an owner’s interest. A deed may contain an error.
The current seller may have no knowledge of any of these issues.
That does not necessarily prevent the sale. It does mean that the issue should be identified and resolved before the buyer accepts the property.
For a buyer purchasing a home in Coral Springs, the property’s recorded history deserves the same attention as its current condition.
Why title matters when buying a house
A real estate listing tells you who is selling the property. It does not establish the entire legal history of the property.
A title examination looks at recorded documents affecting ownership. Depending on the property, those records may include deeds, mortgages, liens, judgments, probate documents, and other instruments.
Florida law governs the recording of interests in real property. Florida Statutes Section 695.01 addresses the recording of conveyances, mortgages, and other interests in land and explains when recorded instruments have priority against certain creditors and subsequent purchasers.
For a buyer, the practical issue is whether the seller can deliver the ownership interest required by the purchase contract.
Consider a property that has passed through several generations.
The owner listed on the tax record may have inherited the house from a parent. That parent may have inherited it from someone else. At some point, an estate may have been administered incorrectly or a deed may have failed to include someone whose interest mattered.
The problem can remain hidden until the property is sold.
A title examination can reveal that history.
This is particularly relevant in established Broward County neighborhoods, where some properties have changed ownership several times over many years.
What happens when the seller inherited the house?
Inherited property can create title questions that do not appear in an ordinary residential sale.
If the seller acquired the property through an estate, the circumstances surrounding that transfer may need to be examined. The buyer may need documentation showing how ownership passed from the deceased person to the current seller.
Probate can therefore become part of a real estate transaction.
This is one reason real estate law and probate law sometimes meet in the same file.
A buyer does not need to become an expert in probate procedure. The important question is whether the person selling the property has the legal authority to transfer the interest the buyer expects to receive.
If that authority is unclear, the transaction may need additional documentation or court action before closing.
A buyer should not assume that an inherited property has a clean title simply because the seller has lived there for years.
The deed deserves careful attention
The deed is the document that transfers the seller’s interest in the property.
Buyers sometimes give it little attention because the purchase agreement and mortgage receive most of the discussion. The deed deserves its own review.
The buyer should understand what interest is being conveyed and who will receive it.
That second question is particularly important.
A person buying a house alone may have a straightforward ownership arrangement. A married couple may have different estate planning concerns. Two unmarried people purchasing together may need to consider what happens if one owner dies or wants to sell.
Parents sometimes purchase property with adult children. Some buyers consider a trust or another ownership arrangement.
Each situation raises different legal questions.
The answer should be based on the buyer’s circumstances rather than a generic preference about how property should be titled.
How you take title can affect your estate
Buying a house creates an asset that may eventually become part of your estate.
The way that asset is owned can affect what happens after death.
Certain forms of ownership can affect whether an interest passes through probate. Other ownership arrangements may require the property to be addressed through the owner’s estate.
This is why the deed and the estate plan should be considered together.
A person might have a carefully prepared will but never review whether the way the person’s property is titled supports the intended estate plan.
That can create problems later.
The purchase of a home is therefore a useful point to review the larger ownership picture.
For a Coral Springs homeowner purchasing a primary residence, that conversation may also involve Florida homestead law.
Florida’s homestead laws deserve special attention when the property will be the buyer’s primary residence.
Florida provides significant legal protections for qualifying homestead property. The state also has specific rules concerning what happens to homestead property after the owner’s death.
Florida Statutes Section 732.401 addresses the descent of homestead property when an owner dies. Section 732.4015 places restrictions on the owner’s ability to devise homestead property when certain family members survive the owner.
These rules can affect surviving spouses and children.
For example, when a Florida homeowner dies while survived by a spouse and descendants, the disposition of the homestead may be governed by statutory rules rather than by whatever result the owner assumed a will would produce.
The details depend on the family and ownership circumstances.
That is why homeowners in Coral Springs and Broward County should not assume that a will alone determines what happens to their Florida homestead.
Can a will control who receives your house?
Sometimes. Florida law can limit what a homeowner may accomplish through a will when the property qualifies as homestead.
The owner’s family situation matters.
The ownership structure matters.
The type of property matters.
The timing of transfers can matter as well.
Florida Statutes Section 732.4015 contains specific restrictions concerning the devise of homestead when a spouse or minor child survives the owner. Section 732.401 also establishes rules concerning descent when a Florida resident dies without a valid disposition controlling the property.
This is one reason estate planning should be based on the actual assets a person owns.
A will should not be viewed in isolation from deeds, trusts, beneficiary arrangements, and Florida’s property laws.
Should you put your house in a trust?
A trust can be useful in some estate plans. It is not the right ownership arrangement for every homeowner.
The decision depends on what the owner wants the estate plan to accomplish.
A revocable living trust, for example, may be considered as part of an incapacity and estate administration plan. Other trusts can serve different purposes.
The important question is whether a particular trust arrangement fits the person’s property, family circumstances, and estate planning objectives.
Florida also has specific rules concerning transfers of homestead property into trusts and other lifetime transfers. Florida Statutes Section 732.4017 addresses certain transfers of homestead property and explains circumstances affecting the way the property is treated under the homestead rules.
That makes professional review useful before changing the title to a Florida home.
A homeowner should understand the consequences of the transfer before signing a new deed.
What if the inspection reveals serious damage?
A home inspection and a legal review serve different purposes.
An inspector examines the physical condition of the house. An attorney examines the legal rights and obligations created by the transaction.
Suppose an inspection reveals structural damage.
The buyer may want the seller to make repairs. A buyer may prefer a price reduction. The buyer may want a credit at closing. The buyer may decide that the property is no longer worth purchasing.
The purchase agreement determines which options are available.
An inspection report does not automatically give the buyer a right to cancel the transaction.
The contract may contain deadlines governing inspection objections. It may establish particular procedures for repairs or termination. Missing those deadlines can affect the buyer’s rights.
A lawyer can explain the relevant provisions before the buyer takes action.
What happens when a title search reveals a lien?
A lien does not always mean the buyer has to abandon the transaction.
The first step is understanding what the lien is and whose obligation created it.
A mortgage may need to be satisfied at closing. A judgment may require resolution. A construction lien may involve a contractor or subcontractor. An estate matter may require additional documentation.
The appropriate solution depends on the problem.
This is where title work becomes practical rather than abstract. The buyer needs to know whether the defect can be resolved before closing and whether the title company will insure the buyer’s intended ownership.
A buyer should also understand any exceptions listed in the title commitment.
Accepting an exception without understanding it can leave the buyer with a title issue that was visible before closing.
Is title insurance enough?
Title insurance provides protection against covered title risks under the terms of the policy.
It does not perform the same function as an attorney representing the buyer.
The Florida Bar explains that a title examination generally precedes issuance of a title insurance policy. A title commitment identifies requirements that must be satisfied before the policy can be issued and lists exceptions to coverage.
Those exceptions deserve attention.
A buyer should know what the policy covers and what it does not cover.
The buyer should also know who represents the buyer.
A closing attorney may be involved in the transaction without representing the buyer personally. The Florida Bar specifically advises consumers to determine who the closing attorney represents.
If you want independent legal advice, ask that question before closing.
When should a Broward County homebuyer consider legal representation?
Some circumstances call for particular caution.
Consider speaking with a Florida real estate attorney when:
The purchase contract contains provisions you do not understand.
The seller inherited the property.
The property has been involved in probate.
The title search identifies a lien or judgment.
A previous deed appears defective.
A divorce affected ownership.
You are buying with someone who is not your spouse.
You are considering buying the property through a trust or business entity.
The house will be a major part of your estate.
The inspection reveals serious defects.
The seller disputes a repair obligation.
The transaction involves seller financing.
The property has unusual easements or restrictions.
A dispute develops before closing.
You are unsure how the property should be titled.
These circumstances are not limited to any particular Broward County neighborhood. They can arise in a Coral Springs purchase just as they can in a transaction elsewhere in South Florida.
The common factor is uncertainty.
A buyer does not need to wait until a dispute reaches court before asking a lawyer to review the transaction.
What should you bring to the attorney?
The purchase contract is the obvious starting point.
If you have not signed it, bring the proposed agreement.
If you have already signed it, bring the complete version along with any amendments.
Other useful documents can include the title commitment, inspection report, seller disclosures, survey, mortgage documents, homeowners association documents, and written communications about repairs.
If the property was inherited, information about the estate can also be important.
If you are purchasing the property as part of an estate plan, bring the relevant estate planning documents.
The attorney also needs to know what you intend to do with the property.
Will it be your primary residence?
Will you own it alone?
Will someone else share ownership?
Do you expect to leave the property to your children?
Are you considering a trust?
Those answers can change the legal analysis.
What does this have to do with probate?
A house can become one of the largest assets handled by an estate.
When the owner dies, the legal treatment of that property depends on how it was owned and the circumstances surrounding the owner’s death.
Some properties pass through probate. Others may pass through a different legal mechanism. Homestead can create additional rules.
This is why the deed signed at the time of purchase can become relevant years later in an estate administration.
A buyer may be thinking about a mortgage and a move.
An estate planning attorney may also need to think about incapacity, death, family rights, and the eventual transfer of the property.
Both perspectives concern the same asset.
For families in Coral Springs and throughout Broward County, that connection can be particularly useful when a home is expected to remain in the family.
A house can create legal consequences long after closing
The closing date is only one point in the property’s legal history.
The deed remains part of the public record. The mortgage may remain for decades. The property may become subject to homestead protections. Ownership may change through marriage, divorce, death, or another transfer.
The house may eventually become part of a probate estate.
That is why a home purchase can be a useful time to review an estate plan.
If you live in Coral Springs or elsewhere in Broward County, the attorney reviewing your purchase should understand the Florida laws that govern the property and your ownership interest.
The goal is to understand the legal consequences before they become difficult to correct.
Questions to ask before signing a purchase contract
A buyer does not need a law degree to ask useful questions.
Start with these:
Who owns the property now?
The answer should be supported by the title records.
Can the seller deliver the title required by the contract?
A title examination can identify issues that need attention.
What happens if the inspection reveals a serious problem?
The answer should come from the purchase agreement and applicable law.
What happens if financing is delayed or denied?
The contract should establish the buyer’s rights in that situation.
Who will own the property after closing?
The deed should reflect the intended ownership arrangement.
What happens to the property if one owner dies?
That question can bring estate planning into the discussion.
Does the property qualify as homestead?
If it will be the buyer’s primary residence, Florida’s homestead laws deserve attention.
Does my estate plan account for this property?
If the house will be a significant asset, the answer should be clear.
The right legal question is often a little earlier
Homebuyers usually have plenty of practical questions.
How much will the mortgage cost?
When can we move in?
Did the inspection find anything serious?
Are the repairs finished?
Those questions matter.
There is another question worth asking before signing:
Do I understand the legal rights I am acquiring and the obligations I am accepting?
If the answer is uncertain, a Florida real estate attorney can review the transaction before the buyer becomes committed to terms that may be difficult to change.
For buyers in Coral Springs and throughout Broward County, that conversation can also include estate planning and probate considerations when the property is expected to remain a significant family asset.
A home purchase creates ownership.
The way that ownership is established can matter for years afterward.
Frequently Asked Questions
Do I need a real estate attorney to buy a house in Florida?
Florida does not require every residential buyer to hire a lawyer. The Florida Bar recommends that prospective buyers consult an experienced Florida licensed real estate attorney before signing a purchase contract. Legal advice can be particularly useful when the transaction involves title questions, unusual contract terms, probate, ownership concerns, or estate planning.
What does a real estate attorney check when buying a house?
A real estate attorney can review the purchase contract, examine title records, review the deed and closing documents, identify liens or other title problems, advise on ownership, and address disputes that arise before closing.
Should I hire an attorney before signing a purchase contract?
If you want legal advice about the agreement, reviewing it before signing gives the attorney an opportunity to identify provisions that could affect your rights. The Florida Bar specifically recommends consulting a Florida real estate lawyer before signing a purchase contract.
Can buying a house affect my estate plan?
Yes. The way a home is owned can affect what happens to the property during incapacity and after death. Florida also has special rules concerning homestead property.
Does a will determine who receives my Florida home?
A will may control some aspects of an estate, but Florida homestead law can restrict how a homestead property may be devised when a surviving spouse or minor child is involved. The ownership structure and family circumstances need to be considered.
Can a house become part of probate?
Yes. Real estate can become part of a probate estate when its owner dies, depending on the ownership structure and circumstances. Property that belonged to a deceased owner may therefore require probate administration before it can be transferred or sold.
Is a title search the same as a home inspection?
No. A home inspection examines the physical condition of the property. A title examination investigates ownership and recorded interests affecting the property.
Does title insurance replace a real estate attorney?
No. Title insurance protects against covered risks under the policy. An attorney can provide legal advice about the contract, title, ownership, closing documents, and other legal issues affecting the buyer.
Should I discuss estate planning when buying a house?
It can be useful when the property will be a significant asset or when the buyer has specific plans for its future ownership. The purchase may be a good opportunity to review the relationship between the new property, the deed, and the existing estate plan.
Can I put my Florida home into a trust?
A Florida homeowner may be able to transfer a home into a trust, but the consequences depend on the type of trust, the property, the owner’s circumstances, and Florida homestead law. Legal advice should be obtained before changing the title.
Talk with an attorney before signing
A home purchase can involve questions about contracts, title, ownership, homestead, probate, and estate planning.
An estate plan under Florida law is not a single isolated document, but an interlocking system of distinct legal instruments.
To function effectively, it coordinates asset titling (how property is owned), contractual beneficiary designations (such as life insurance and retirement accounts that bypass probate), revocable living trusts (for private asset management), and a Last Will and Testament (which acts as an administrative backstop for stray assets and nominates guardians for minor children under the 17th Judicial Circuit probate framework).
Direct Transfer InstrumentsBeneficiary designations and trusts that bypass probate to route funds directly to intended recipients.
The Backstop AdministrationWills and probate courts acting as the administrative safety net for any leftover or stray assets.
A common misconception among clients entering an attorney’s office is that estate planning is merely a shopping exercise. People assume they need to choose between buying a will or setting up a trust. As if these documents were competing consumer products on a shelf.
In practice, a durable estate plan functions less like a single document and more like an interlocking machine. Each piece: whether it is a deed, a beneficiary designation, a trust agreement, or a last will and testament – answers a different legal question about your property, your care, and your family’s future security under Florida law.
Asset Ownership Sets the Foundation
Every legal instrument relies entirely on the underlying registration of your property.
The name on a title holds more legal authority over where property goes than almost any standard clause you can write down. Consider how differently law treats various holdings. A commercial storefront in Coral Springs tied to a corporate entity, a family home structured with survivorship rights, or an ordinary checking account carrying no payable on death instructions. Each follows its own strict statutory track.
Property registration and testamentary instruments point in opposite directions. The title or contractual beneficiary designation almost always supersedes your written documents. For instance, naming a child in a will has no legal effect on a bank account where a different individual is listed as the sole payable on death recipient. A thorough planning process evaluates these existing ownership titles first. Therefore ensuring that deeds, corporate shares, and financial accounts are adjusted or harmonized before any wills or trusts are finalized.
Different Assets Can Follow Different Paths
When an individual passes away, their property does not automatically flow down one universal river. Different asset classes utilize entirely distinct legal conduits:
Contractual Transfers: Life insurance policies, retirement accounts, and payable on death bank accounts bypass both wills and trusts entirely. Thus transferring directly to named beneficiaries by operation of contract law.
Trust Administration: Assets properly titled in the name of a revocable living trust flow privately through trustee administration without judicial interference.
Probate Administration: Assets left solely in an individual name with no beneficiary designation must be processed through the probate court system.
Understanding that these pathways operate simultaneously is the key to grasping how an estate plan actually functions.
The Operational Reality of Financial Accounts and Institutional Payables
A common blind spot in estate planning is assuming that legal documents command absolute authority over every dollar an individual owns. In practice, financial institutions, such as major banks operating in Coral Springs and regional credit unions, don’t act like this. They do not look to your will or trust first when an account holder passes away.
Instead, financial operations are strictly governed by internal institutional protocols and direct account contracts. When a bank representative reviews an account after a death certificate is presented, they execute whatever binding agreement is physically attached to that specific account file. If a bank ledger lists an individual payable on death designation, or if a brokerage account registers a transfer on death instruction, institutional compliance departments are legally bound to disburse those funds directly to the named individual, bypassing any instructions found in a trust agreement or a court supervised will.
An integrated estate plan accounts for this operational friction by auditing every institutional account agreement during the drafting phase. Therefore ensuring that corporate paperwork matches your overarching legal strategy before a financial institution ever faces a disbursement decision.
Where the Will Fits Into the Plan
Rather than acting as the absolute ruler of your entire estate, a Last Will and Testament serves a specific structural purpose within the broader system.
Within an integrated plan, a will functions primarily as a legal backstop. It catches stray assets that were never retitled into a trust. Names guardians for minor children. It also nominates the personal representative to manage the probate administration process if court intervention becomes necessary.
Where a Trust Fits Into the Plan
A revocable living trust operates as an alternative operating system for asset management and distribution.
When properly funded during your lifetime, the trust holds legal title to your major property holdings. Instead of directing asset distribution through public probate filings, the trust instrument coordinates private management rules. It establishes exact conditions for beneficiaries, and governs how assets are handled if you experience temporary or permanent incapacity.
If certain assets remain outside your trust or lack beneficiary designations, the probate court becomes the mandatory administrative mechanism required to clear title and transfer ownership. The goal of comprehensive planning is not always to eliminate every possibility of court involvement, but to ensure that probate handles only what is necessary while private mechanisms handle the bulk of your wealth.
What Happens When the Pieces Do Not Match?
The most critical test of an estate plan occurs when its individual instruments conflict with one another.
Consider a scenario where an individual executes a trust directing that their financial account be divided equally among three children, but the underlying bank account form lists only one child as a payable on death beneficiary. Under Florida law, the contractual beneficiary designation on the account typically overrides the instructions in the trust or will.
When beneficiary designations, trust agreements, and asset titles point in opposing directions, family disputes and unintended disinheritances frequently follow. Coordination prevents these friction points.
Through durable powers of attorney and healthcare surrogate designations, your plan designates trusted individuals to manage financial transactions, sign documents, and make medical decisions if you are unable to speak for yourself. These instruments integrate seamlessly with your property management framework, ensuring continuity whether you are navigating daily life or managing a medical crisis in Broward County.
Frequently Asked Questions
Does having a revocable living trust mean my estate will completely avoid probate in Florida?
Not automatically. A trust only avoids probate for assets that were properly titled in the name of the trust during your lifetime. Any remaining individually owned assets left outside the trust at the time of death will still require a probate administration unless alternative transfer mechanisms apply.
Can a beneficiary designation override the instructions written in my last will and testament?
Yes. Contractual arrangements such as life insurance policies, retirement accounts, and payable on death bank accounts operate independently of a will. The financial institution distributes funds directly to the named beneficiary on file, regardless of what your will states.
Why is asset titling just as important as drafting a will or trust?
Asset titling dictates the legal pathway property travels upon death or incapacity. If your legal documents specify one distribution plan but your deeds or account titles are registered under a conflicting ownership structure, the ownership title or beneficiary form frequently overrides your written documents.
How does local court jurisdiction in Broward County affect the administration of an estate plan?
When an estate plan requires judicial oversight, such as formal or summary administration through the 17th Judicial Circuit Court in Broward County, local procedural rules govern how property titles are cleared and distributed.
An integrated estate plan accounts for these local court requirements ahead of time, minimizing administrative delays for real estate located in Coral Springs, Parkland, or Fort Lauderdale by ensuring property deeds and trust funding are properly structured before probate ever becomes necessary.
What happens if instructions in a revocable living trust contradict a financial account beneficiary form?
If a revocable living trust states that all liquid accounts should be divided equally among beneficiaries, but an individual retirement account or bank account lists a single person as a payable on death recipient, the financial institution is legally bound to honor the beneficiary form.
A comprehensive estate audit resolves these discrepancies proactively to prevent unintended disinheritances.
Coordinate Your Estate Plan in Broward County
The goal of estate planning is not to accumulate the largest stack of legal documents. It is to ensure that your ownership titles, beneficiary forms, trusts, and wills work together as a unified system to protect your family and assets.
The best real estate attorney in Coral Springs is not necessarily the lawyer with the most reviews, the longest list of services, or the strongest advertising. The right attorney depends on the type of property matter you need to resolve, the attorney’s experience with that type of matter, and whether you need transactional advice, dispute resolution, or litigation. For homeowners, buyers, sellers, landlords, tenants, and businesses in Coral Springs and throughout Broward County, identifying those factors can make it easier to find appropriate legal representation.
Choosing a real estate attorney starts with understanding what kind of legal problem you actually have. A lawyer who regularly handles residential purchases may have a different focus from one who handles title disputes, commercial transactions, foreclosure matters, or real estate litigation.
That makes the right question less about finding the attorney with the biggest advertisement and more about finding an attorney whose experience fits your situation.
For property owners, buyers, sellers, landlords, and businesses in Coral Springs and throughout Broward County, a few practical considerations can help narrow that choice.
Start With the Real Estate Problem
Real estate law covers a wide range of matters. Before choosing an attorney, identify what you need help with.
A person buying a home may need contract review or help addressing a title problem. A property owner facing a dispute may need representation in litigation. A landlord and tenant may need advice about their respective rights and obligations. A business purchasing or leasing commercial property may face substantially different legal and financial issues.
Some common matters include:
Residential and commercial real estate transactions
Purchase and sale agreements
Contract review and disputes
Title and ownership disputes
Foreclosure matters
Landlord and tenant disputes
Property damage claims
Short sales and distressed property
Real estate litigation
Commercial leases and other property agreements
The important point is that real estate experience is not one-size-fits-all. The nature of the problem should help determine what kind of attorney you need.
Ask What Experience Actually Applies to Your Matter
A long legal career can be valuable, but years of practice alone do not tell you whether an attorney is a good fit for a particular property issue.
Consider whether the attorney regularly handles matters similar to yours. Someone experienced in negotiating residential purchase agreements may approach a title dispute differently from an attorney whose practice includes real estate litigation.
The same applies to commercial property. A transaction involving a business, commercial lease, development project, or other substantial investment can involve issues that do not arise in a typical residential purchase.
The more closely an attorney’s experience matches the problem, the easier it may be to identify the relevant risks and available options.
Ask Who Will Actually Handle the Matter
It is reasonable to ask who will be responsible for your case or transaction after the initial consultation.
Will the attorney you meet personally review the important documents? Who will communicate with you if a dispute develops? If litigation becomes necessary, does the firm have experience handling that type of proceeding?
These questions can matter because a real estate matter may begin as a transaction and later become a dispute. Understanding who will be handling the legal work can help you make a more informed decision before retaining counsel.
Know When a Real Estate Problem Needs Legal Attention
Not every property question requires an attorney immediately. Some situations, however, can become considerably harder to resolve if important documents are signed, deadlines pass, or a dispute escalates before the legal issues are understood.
A consultation may be particularly useful when:
A purchase or sale agreement contains language you do not understand.
The parties disagree about the meaning or performance of a contract.
A title search reveals a lien, ownership issue, or other unexpected problem.
Someone challenges your ownership or right to use a property.
A landlord and tenant dispute has escalated beyond an ordinary disagreement.
You have received legal papers involving a property.
A foreclosure or other serious action may affect your property rights.
A transaction has stalled because the parties cannot resolve a legal issue.
Property damage has created a disagreement about responsibility or compensation.
The point is not that every disagreement will lead to litigation. Early legal advice can sometimes clarify the parties’ rights, identify documents that need attention, or reveal an issue that should be addressed before the transaction or dispute progresses further.
What Should You Bring to a Real Estate Attorney?
The usefulness of an initial consultation often depends on how much relevant information is available. You do not need to organize every document perfectly, but bringing the important records can help an attorney understand the situation more quickly.
Depending on the matter, useful documents may include:
Purchase or sale contracts
Deeds and other property records
Lease agreements
Closing documents
Title or lien information
Mortgage or foreclosure documents
Property management records
Written communications between the parties
Notices, demands, or court documents
Photographs or records relating to property damage
Previous agreements concerning the property
A lawyer may need additional information after reviewing these materials. Still, having the relevant documents available can make it easier to identify the central issue and determine what should happen next.
Understand What the First Consultation Should Accomplish
A useful consultation should give you a clearer understanding of the legal issue, even if the matter cannot be resolved during the first meeting.
Depending on the circumstances, you should expect to discuss:
The property and the people or businesses involved
The documents relevant to the matter
Important deadlines or upcoming transactions
Potential legal problems or areas of uncertainty
Possible ways to address the issue
Whether additional documents or investigation are needed
What the next stage of the legal process may involve
How the attorney’s fees and representation would be structured
You do not necessarily need a definitive answer to every question during an initial consultation. Real estate disputes can depend on documents, ownership records, contracts, communications, and other facts that require careful review.
What matters is leaving the consultation with a better understanding of what the problem is and what needs to happen next.
Consider Whether You Need a Transactional Attorney or a Litigator
One distinction can be especially important when choosing a real estate attorney: Will the matter involve a transaction, a dispute, or potentially both?
Transactional work can involve reviewing and negotiating contracts, addressing closing issues, examining title concerns, and helping clients complete property transactions.
Litigation involves a different set of considerations. If the parties are already in a dispute over ownership, a contract, property damage, a landlord and tenant relationship, or another real estate issue, the matter may require representation in a legal proceeding.
Some situations can also move from one category to the other. A disagreement that begins during a transaction can become a formal dispute.
Understanding where your matter falls can help you find an attorney whose experience matches the stage and nature of the problem.
Local Experience Can Matter
Real estate law is governed by Florida law, but local circumstances can still matter when dealing with property in Coral Springs and elsewhere in Broward County.
A local attorney may be familiar with the types of residential, commercial, ownership, and property disputes that commonly arise in the area. More importantly, the attorney should understand the Florida laws governing the particular issue rather than relying solely on general real estate experience.
For property owners and businesses in Coral Springs, the goal should be to find counsel who understands both the legal issue and the circumstances surrounding the property.
Look Beyond Marketing Claims
Searching for the “best” real estate attorney can produce plenty of advertisements, awards, testimonials, and claims of experience.
Those things can be useful information, but they should not be the only basis for choosing counsel.
A better evaluation asks:
Does the attorney handle matters like mine?
Does the attorney understand the relevant Florida law?
Will I know who is responsible for my matter?
Can the attorney explain the risks and options clearly?
Do I understand how the representation will work?
Does the firm’s experience fit the problem I am trying to solve?
The attorney with the longest list of services is not necessarily the right attorney for every situation. The best fit depends on the legal problem, the property involved, and the type of representation required.
Choosing the Right Real Estate Attorney
Finding a real estate attorney in Coral Springs should begin with the problem you need to solve, not simply with a search for the most prominent name.
Whether you are buying or selling property, dealing with a title or ownership dispute, facing a foreclosure issue, managing a landlord and tenant matter, or dealing with another real estate concern, the attorney’s relevant experience should be one of the first things you evaluate.
For residents and businesses in Coral Springs and throughout Broward County, a consultation can help determine what legal issues are involved, what information needs to be reviewed, and what options may be available.
The best attorney is ultimately the one whose experience and approach fit your particular real estate matter.
Frequently Asked Questions
When should I contact a real estate attorney in Coral Springs?
You should consider contacting a real estate attorney when a property matter involves a contract, dispute, significant financial risk, or legal obligation you do not fully understand. This can include reviewing a purchase or sale agreement, addressing a title problem, dealing with a landlord tenant dispute, or responding to a property related lawsuit. Getting legal advice early can help identify problems before they become harder or more expensive to resolve.
Do I need a real estate attorney for a standard property transaction?
Not every transaction requires the same level of legal assistance. Some matters may be relatively straightforward, while others involve unusual contract terms, title issues, financing concerns, ownership disputes, or other complications. A consultation can help determine whether your particular transaction would benefit from legal review and what issues should be addressed before you sign.
How do I choose the right real estate attorney for my situation?
Start by identifying the specific property issue you need help with and then look for an attorney with relevant experience. Ask who will handle your matter, whether the attorney regularly handles similar cases, and what the initial consultation will cover. Local experience in Coral Springs and Broward County can also be useful when your matter involves local property, courts, or other parties in the area.
How does local court jurisdiction in Broward County affect the administration of an estate plan?
When an estate plan requires judicial oversight, such as formal or summary administration through the 17th Judicial Circuit Court in Broward County, local procedural rules govern how property titles are cleared and distributed. An integrated estate plan accounts for these local court requirements ahead of time, minimizing administrative delays for real estate located in Coral Springs, Parkland, or Fort Lauderdale by ensuring property deeds and trust funding are properly structured before probate ever becomes necessary.
What happens if instructions in a revocable living trust contradict a financial account beneficiary form?
Under Florida law, contractual arrangements and direct asset titling rules generally supersede instructions written inside a will or a trust. If a revocable living trust states that all liquid accounts should be divided equally among beneficiaries, but an individual retirement account or bank account lists a single person as a payable on death recipient, the financial institution is legally bound to honor the beneficiary form. A comprehensive estate audit resolves these discrepancies proactively to prevent unintended disinheritances.
Need Help With a Real Estate Matter?
If you are dealing with a property transaction, contract issue, landlord tenant dispute, title problem, or real estate litigation in Coral Springs or Broward County, the right legal advice can help you understand your options before you make an important decision.
MyPersonalAttorneys has been recognized by local readers and community organizations for its legal services, including recognition as a Readers’ Choice favorite in Coral Springs. If you need assistance with a real estate matter, contact our firm to discuss your situation with an experienced real estate attorney.
Under Florida law, you generally cannot use a standard landlord-tenant eviction to remove a family member who does not pay rent and has no lease. Instead, homeowners must file an Unlawful Detainer action under Florida Statutes Chapter 82. This has to be done in county court to legally regain possession of the property.
Inviting an adult child, relative, or guest to stay in your home can start as a temporary arrangement. When that relationship breaks down or the guest refuses to leave, the situation quickly becomes stressful and emotionally exhausting.
For homeowners in Broward County, trying to resolve this can feel overwhelming, especially if you are worried about legal missteps.
The biggest mistake a homeowner can make is treating a family member like a standard tenant. Under Florida law, the legal mechanism for removing a guest or family member is entirely different from evicting a renter. Using the wrong procedure can lead to immediate dismissal in the 17th Judicial Circuit, wasting valuable time.
Why a Family Member Is Usually Not a “Tenant”
Many homeowners assume that anyone living in a home without paying rent can be put out through a standard landlord-tenant eviction.
Under Florida Statutes Chapter 83, a residential eviction requires a valid landlord-tenant relationship, which typically involves a lease agreement or a formal agreement to pay regular rent.
If you permitted a family member, friend, or former partner to move into your Coral Springs home without a lease and without paying rent, they are legally considered a guest or occupant, not a tenant.
Attempting to issue a standard 3-day or 7-day tenant notice or filing a Chapter 83 landlord-tenant lawsuit for someone who isn’t a tenant can cause a judge to throw the case out of court.
Instead, the proper legal remedy under Florida law for removing an unauthorized or overstaying guest who has no ownership interest or lease is an Unlawful Detainer action under Florida Statutes Chapter 82.
An unlawful detainer action is a lawsuit filed in county court to regain possession of property from someone who entered with permission. Such as a family member or guest – but whose permission has since been revoked.
Key elements of a Florida unlawful detainer include:
No Lease Required: The occupant has no written or oral lease agreement.
No Rent Paid: The occupant does not pay regular rent (occasional or minor household contributions do not create a tenancy).
Revoked Consent: You have officially withdrawn permission for them to remain on the property.
Unlike standard tenant evictions, an unlawful detainer action generally does not require a statutory advance notice period before filing the complaint in court, though giving clear written notice to vacate is often a prudent first step to encourage voluntary compliance.
The Legal Process to Remove an Occupant in Broward County
When a family member refuses to leave after you have asked them to go, navigating the court system correctly is essential. The process in Broward County typically follows these procedural phases:
1. Revoking Consent and Demanding Possession
While not strictly mandated by Chapter 82 for every scenario, providing a clear, written demand letter stating that permission to occupy the property is terminated by a specific date helps establish a clean timeline for the court.
2. Filing the Unlawful Detainer Complaint
If the individual remains on the property, the homeowner files a formal Unlawful Detainer Complaint in the County Civil Division of the 17th Judicial Circuit. At this stage, you are designated as the Plaintiff, and the occupant is the Defendant.
3. Service of Process via the Broward County Sheriff
Once filed, the Clerk issues a summons. The summons and complaint must be formally served to the occupant by the Broward County Sheriff’s Office or a certified process server.
4. The Response Window and Court Hearing
In Florida unlawful detainer actions, the defendant is given a short window (typically 5 business days from service) to file a written response with the court.
If the occupant fails to respond, you can move for a default judgment.
If the occupant files an answer contesting the removal, the court will schedule a hearing where both sides present evidence regarding who holds the superior right to possession.
5. Issuance and Execution of the Writ of Possession
If the court rules in your favor, a Final Judgment of Possession is entered, and the clerk issues a Writ of Possession. This writ is delivered to the Broward County Sheriff, who will execute the removal to restore full possession back to the homeowner.
Why You Should Never Take Matters Into Your Own Hands
Property owners are sometimes tempted to change the locks or remove a family member’s belongings while they are out.
Under Florida law, “self help” evictions or lockouts are strictly illegal—even against non-tenant guests or family members. Engaging in self help can expose a homeowner to civil liability, tenant rights claims, and court penalties.
Working with an experienced Coral Springs real estate and property litigation attorney matters. It ensures that every step follows statutory guidelines, protecting you from procedural delays.
Frequently Asked Questions
What is the difference between an eviction and an unlawful detainer in Florida?
An eviction (Chapter 83) is used exclusively to remove tenants who have a lease or an agreement to pay rent. An unlawful detainer (Chapter 82) is used to remove guests, former partners, or family members who never had a lease. They never paid rent, and refuse to leave after permission is revoked.
Do I have to give a 3-day or 7-day notice before filing an unlawful detainer?
Unlike standard residential evictions, Florida law does not require a statutory advance notice period before filing a Chapter 82 action. But providing written notice is often recommended.
Can the police physically remove a family member from my house?
Generally, local law enforcement agencies in Broward County will treat disputes involving occupants who were originally invited into the home as a “civil matter” rather than a criminal trespass. Therefore requiring the homeowner to obtain a court order or Writ of Possession.
What if the family member claims they have an ownership interest in the house?
If an occupant asserts a legitimate claim to title of the property, a standard unlawful detainer action may be insufficient. That’s why an ejectment action in Circuit Court may be required instead.
How long does an unlawful detainer take in Broward County?
Because unlawful detainer actions qualify for Florida’s summary procedure statutes, they are designed to move faster than standard civil lawsuits. Timelines depend on court scheduling, service of process, and whether the defendant contests the action.
Schedule a Consultation with Our Coral Springs Real Estate Attorneys
Dealing with an uncooperative family member in your home is stressful and legally complex. Whether you need assistance filing a Chapter 82 unlawful detainer or evaluating the right property recovery procedure in Coral Springs, Broward County, or South Florida, Alan Reinfeld and Stuart Reinfeld can help. Contact our office today to protect your property rights and resolve the situation lawfully.