When you walk into your kitchen, grab a cup of coffee, and find a foreclosure notice sitting right next to the toaster, the panic hits you square in the chest.
How on earth did things get this far, and is there any actual, realistic way to save your home before the bank schedules a fire sale on the courthouse steps?
Quick Answer: Under Florida law, a judicial foreclosure typically takes 6 to 14 months to complete, providing homeowners with a vital legal window to pursue loss mitigation options like a Fannie Mae Flex Modification or file a formal defense. Under federal RESPA rules (12 C.F.R. § 1024.41), mortgage servicers are strictly prohibited from dual tracking a foreclosure while a complete loan modification application is under review.
If you wander onto the internet looking for mortgage relief, you will trip over old blog posts, expired federal initiatives from decades past, or blanket quick fixes that vanished years ago. Relying on outdated internet advice or waiting around for a government bailout program that no longer exists is a marvelous way to lose your property while wondering what went wrong.
So what options do Florida homeowners actually have right now when facing default, past due mortgage payments, or a looming court summons in the 17th Judicial Circuit? Let us break down how modern loan modifications, loss mitigation, and active foreclosure defenses work in today’s real estate market without any corporate mumbo jumbo.
Why Modern Loss Mitigation Replaced One Size Fits All Federal Programs
When banks initiate foreclosure proceedings in Florida, they move through a strict, formal judicial process. Older programs like HAMP dictated a rigid federal template, but today mortgage servicing relies on standardized corporate guidelines and portfolio specific workouts.
Modern foreclosure defense requires looking at your current financial snapshot and choosing an active legal path:
Standardized Lender Modifications: Major loan servicers and government backed entities like Fannie Mae and Freddie Mac utilize structured programs—such as the Flex Modification—to lower monthly payments by extending loan terms up to 40 years, capitalizing missed arrears, or adjusting interest rates.
Chapter 13 Bankruptcy Protection: For homeowners with steady income facing an imminent foreclosure auction, filing a Chapter 13 plan can halt the bank instantly, giving you a court approved safety net to catch up on mortgage arrears over three to five years.
Strategic Loss Mitigation & Short Sales: If staying in the home is no longer financially viable, a managed exit strategy protects your overall credit profile and helps avoid a predatory deficiency judgment.
How Modern Loan Modifications Work With Your Lender
Securing a permanent loan modification requires navigating a structured underwriting review with your loan servicer.
Ask yourself: Does my current monthly income realistically support a restructured payment if the bank agrees to stretch out the loan term or lower the interest rate?
To qualify for a modern in-house or agency backed loan modification, your servicer will typically look for three key criteria:
Proof of Stable Income: Verifying that you have sufficient monthly earnings through pay stubs, profit and loss statements, or tax documents to support a modified payment structure.
Primary Residence Verification: Demonstrating that the property is your primary home rather than an unmanaged investment portfolio asset.
Financial Hardship Documentation: Providing a signed hardship affidavit explaining the life event—such as a medical emergency, job change, or temporary income reduction—that caused you to fall behind.
Avoiding Dual Tracking and Protecting Your Rights Under Federal Servicing Rules
When dealing with mortgage default or foreclosure in Florida, many homeowners worry that submitting a loan modification application will cause the bank to quietly move forward with a foreclosure judgment behind their backs.
What safeguards actually prevent lenders from rushing an auction while your loss mitigation paperwork is sitting on an underwriter desk?
Under federal regulations governed by the Consumer Financial Protection Bureau (12 C.F.R. § 1024.41), mortgage servicers are strictly prohibited from engaging in dual tracking. Dual tracking occurs when a lender simultaneously processes a foreclosure lawsuit while a complete loss mitigation or modification application is actively under review.
Critical Protection Milestones for Florida Borrowers
The 120 Day Rule: Under federal rules, a mortgage servicer generally cannot officially file a judicial foreclosure complaint in court until a borrower is more than 120 days delinquent on payments. This window gives homeowners ample time to submit an initial loss mitigation package.
The Evaluation Freeze: If you submit a complete modification application before the bank makes its first official foreclosure filing or moves for a judgment, the servicer cannot move for foreclosure judgment or conduct a judicial sale until they have formally evaluated your application and provided you with written notice of their decision.
The Right to Appeal: If a servicer denies a modification, federal guidelines often provide a 14 day window to appeal the decision if the application was submitted at least 90 days before a scheduled sale date.
If a lender or bank servicer violates these federal protections or mishandles your paperwork while operating in local courts like the 17th Judicial Circuit in Broward County, an experienced foreclosure defense attorney can leverage these violations to halt the lawsuit, challenge the bank’s standing under Fla. Stat. § 702.015, and force the lender back to the negotiating table.
Real-World Case Example: Stopping Dual Tracking in Broward County
Consider a case our firm handled where a Broward County homeowner inherited a residential property after a family member passed away. The mortgage servicer quickly initiated a foreclosure action in the 17th Judicial Circuit. To make matters worse, the bank mishandled the estate transfer documents and loss mitigation paperwork, attempting to rush a foreclosure judgment while the surviving family member was trying to secure a loan modification.
How Our Legal Team Resolved the Case
Challenging Standing: We filed formal defenses requiring the bank to prove proper legal standing under Florida law.
Stopping Dual Tracking: We enforced federal rules under 12 C.F.R. § 1024.41 to halt the foreclosure sale while the modification paperwork was under review.
Securing the Result: The active defense forced the lender to stop the rushed timeline and approve a permanent solution that allowed the family to keep their home.
Frequently Asked Questions About Florida Foreclosures
Can I fight a foreclosure lawsuit while simultaneously applying for a loan modification?
Yes. Under Florida law and federal mortgage servicing rules, working with your lender on loss mitigation options does not mean you should ignore a pending lawsuit. Having a defense attorney file a formal answer in court protects you from a default judgment while your modification application is actively being reviewed.
What happens if the bank wrongfully denies my loan modification request?
If a servicer improperly denies your modification or violates federal RESPA (Real Estate Settlement Procedures Act) guidelines by dual tracking your file while a complete modification application is pending, a real estate litigation attorney can hold them accountable in court.
How long does the judicial foreclosure process take in Florida?
Because Florida is a strict judicial foreclosure state, lenders cannot seize property without filing a formal lawsuit in circuit court. On average, an uncontested or contested foreclosure timeline spans anywhere from 6 to 14 months, providing a critical window to evaluate defense options, pursue loss mitigation, or negotiate with the bank.
What is a Fannie Mae or Freddie Mac Flex Modification?
The Flex Modification is a standardized loss mitigation program used for government backed conventional loans. It is designed to achieve a target reduction in monthly principal and interest payments by capitalizing delinquent amounts, lowering interest rates, or extending the loan maturity term up to 480 months.
Does filing for bankruptcy stop a scheduled foreclosure sale in Broward County?
Yes. The moment a Chapter 13 or Chapter 7 bankruptcy petition is filed, an automatic stay goes into effect under federal law. This injunction immediately halts all collection efforts, creditor calls, and scheduled foreclosure sales governed by the 17th Judicial Circuit in Broward County, giving you breathing room to reorganize your debts.
Can a lender proceed with foreclosure if I never received a default notice?
Lenders must comply with strict contractual notice conditions precedent outlined in standard mortgage agreements, typically requiring a formal notice of default and intent to accelerate thirty days prior to filing a lawsuit. If the bank failed to provide proper statutory or contractual notice, a defense attorney can leverage this error to dismiss or delay the foreclosure action.
Protect Your Home and Your Financial Future
Facing foreclosure alone is a risk you should not take. Whether your goal is to restructure your loan, fight the bank standing in court, or execute a graceful exit strategy to preserve your credit, you need a localized game plan.
The foreclosure defense attorneys at Reinfeld & Cabrera P.A. help homeowners across South Florida navigate complex lender disputes, evaluate modification alternatives, and protect their rights.
Schedule a Confidential Foreclosure Consultation
Do not wait until a sale date is scheduled. Speak directly with an attorney today to review your options:
Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
Website: mypersonalattorneys.com
Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all surrounding communities across Broward, Miami Dade, and Palm Beach Counties.
If you manage or own rental property in South Florida, tenant turnovers and the occasional eviction are bound to happen. But here is the catch: when a lease ends or a tenant vacates under court order, how you handle their security deposit can make or break your legal standing.
Can you simply keep the deposit to cover unpaid rent or property damage? Not without following Florida procedural rules to the letter. Missing a statutory deadline or skipping a certified letter notice can strip away your legal right to hold those funds even if the tenant destroyed your floors or walked out owing months of rent.
So how does Fla. Stat. § 83.49 actually work when you are standing inside an empty unit staring at ruined drywall? What concrete steps must you take right now to protect your bottom line, and how can you keep yourself far away from costly disputes in local South Florida courtrooms? Let us break down everything you need to navigate move outs safely.
What Are Florida Security Deposit Notice Deadlines?
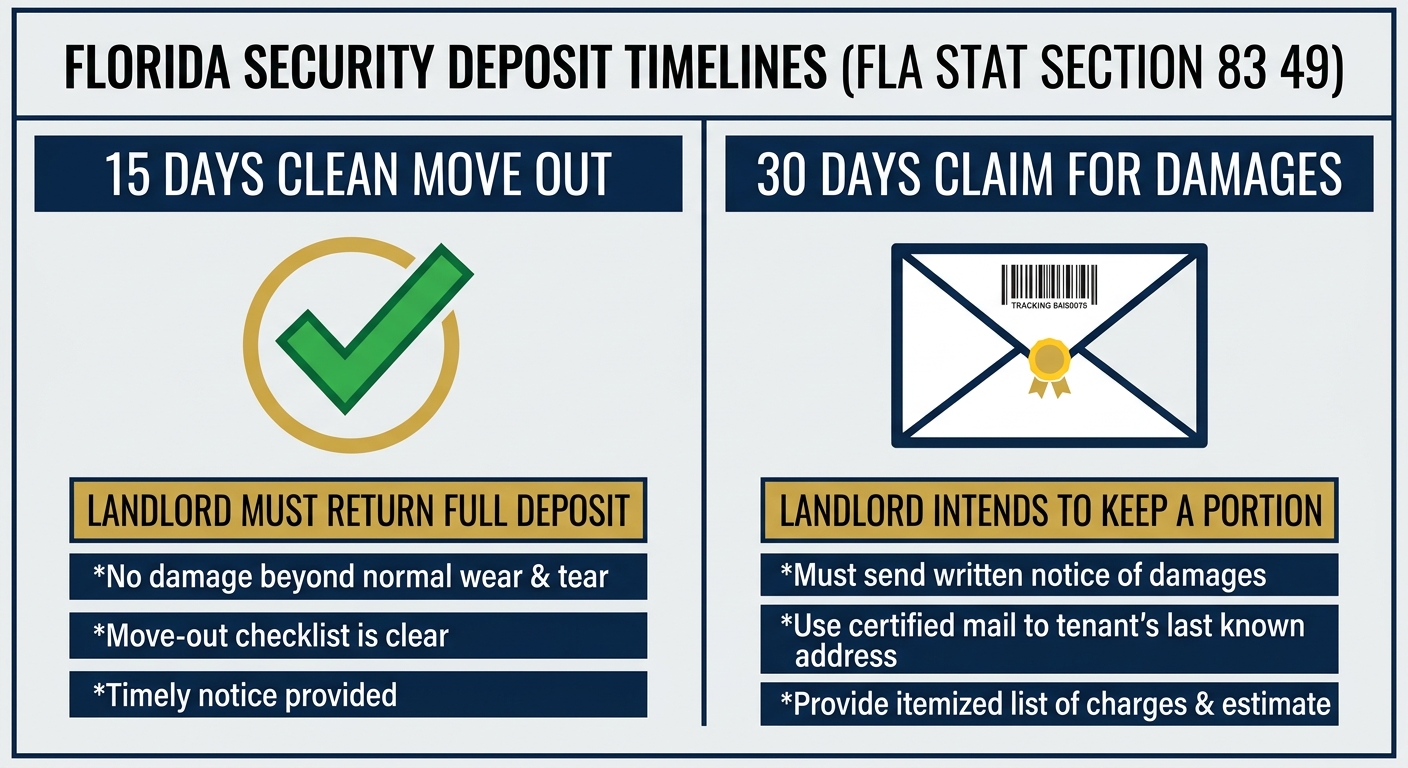
Quick Answer: Under Fla. Stat. § 83.49, Florida landlords have 15 days to return a security deposit in full if no deductions are being made. However, if you are claiming money for property damage, deep cleaning, or unpaid rent, you have 30 days to send an itemized claim via Certified Mail to the tenant last known address. If you fail to send this notice within 30 days, you legally forfeit your right to claim any part of the deposit.
The Core Rule: 15 Days vs 30 Days
Why do so many property owners get tripped up by Florida security deposit timelines? Usually, it comes down to confusing a clean turnover with a damage claim. You might ask yourself: Am I simply handing back their money, or am I preparing to fight for repair costs? The law divides move outs into two distinct paths:
No Claim on Deposit (15 Days): Timeline is 15 days from move out. Action requires a full refund plus accrued interest if held in an interest account. Target is clean turnovers.
Imposing a Claim (30 Days): Timeline is 30 days from move out. Action requires sending an itemized claim via Certified Mail containing required statutory text. Target covers physical damage, back rent, or unpaid utility fees.
1. The Clean Turnover (15 Day Window)
Suppose your tenant moves out, hands over the keys, and leaves the home in excellent shape with zero unpaid rent. Under Fla. Stat. § 83.49(3)(a), you have exactly 15 days from the date they vacate to return their full deposit along with any accrued interest if kept in an interest bearing account.
2. The Damage or Back Rent Claim (30 Day Window)
Now, what if you walk into the property and find broken drywall, ruined carpets, or an unpaid utility balance? Would a quick text message or an informal email suffice to let them know you are withholding funds? Absolutely not.
In this scenario, you have 30 days to issue a formal written notice detailing your intent to keep part or all of the deposit. Florida law strictly mandates that this notice must be sent by Certified Mail to the tenant forwarding address or last known mailing address. I often tell property owners to treat that certified mail receipt like pure gold because without it, proving you met your 30 day clock becomes nearly impossible.
What Happens if You Skip the Statutory Warning Language?
Here is a detail that continuously catches self managing landlords off guard: it is never enough to write a quick note stating, “I am keeping $500 for carpet repairs.”
Florida statute explicitly mandates that your notice include specific statutory warning language informing the tenant of their right to object within 15 days.What actually happens if you leave this mandatory wording out? Legally, the entire notice becomes invalid. That means you forfeit your right to retain the deposit and could end up paying the tenant legal fees under Fla. Stat. § 83.48 if they retain an attorney to contest your error.
I always think: Why risk losing thousands over a missed paragraph when the statute gives you the exact script to copy?
The 15 Day Tenant Objection Clock
Once the tenant receives your certified letter, the ball moves directly into their court:
If they do not object within 15 days: You are legally authorized to deduct the claimed amount from the deposit and return any remaining balance to them within 30 days of the original notice date.
If they object in writing: You now have a formal legal dispute on your hands. If that disagreement escalates into county court in Broward, Miami Dade, or Palm Beach County, a judge will review whether every single statutory notice rule was meticulously followed.
What Counts as Legitimate Deductions vs Normal Wear and Tear?
One of the most frequent friction points between landlords and departing tenants is deciding what damage justifies keeping deposit funds.
Before you start writing up your itemized bill, ask yourself: Is this issue the natural result of everyday human living, or does it represent actual property destruction and tenant negligence?
Permissible Deductions (Tenant Damage)
Unpaid rent, fees, or utility balances
Holes in drywall, broken doors, or cracked floor tiles
Pet damage such as scratched doors, carpet stains, or deep odors
Trash removal and heavy cleaning charges for abandoned personal property
Impermissible Deductions (Normal Wear and Tear)
Faded wall paint or small nail holes from picture frames
Minor carpet wear or light scuffs along high traffic hallways
Aging, worn door handles or standard cabinet hinges
Routine HVAC filter servicing or standard dust accumulation
Frequently Asked Questions for Florida Landlords
What if I completely miss the 30 day Certified Mail deadline?
If you miss the 30 day window, you automatically forfeit your right to retain the security deposit under Fla. Stat. § 83.49, meaning you must return 100 percent of the money to the tenant. Does this mean you are completely out of options if they wrecked your rental property? Not entirely. Missing the deposit deadline prevents you from holding onto their deposit money, but it does not prevent you from filing a separate lawsuit against the former tenant in court for breach of contract or physical property damage.
Does winning an eviction judgment mean I can automatically keep the deposit?
Surprisingly, no. Even if you secure a writ of possession in the 17th Judicial Circuit Court of Broward County, you remain legally bound to send the 30 day certified claim notice if you intend to apply the security deposit toward back rent or damages caused by the evicted tenant. I see landlords fall into this exact trap all the time assuming an eviction order wipes out their security deposit duties.
Can I include a clause in my lease waiving these notice rules?
No. Florida courts treat Fla. Stat. § 83.49 as a mandatory protection statute. Any clause inside a residential rental agreement that attempts to bypass, shorten, or alter these statutory notice timelines is considered legally null and void.
Protect Your Real Estate Investments with Legal Counsel
Whether you manage a single rental home in Coral Springs or an apartment complex in Fort Lauderdale, administrative slip ups during tenant move outs can cost you thousands in lost funds and legal fee awards.
The real estate litigation team at Reinfeld & Cabrera P.A.helps South Florida landlords, investors, and property managers enforce lease agreements, execute formal evictions, and navigate security deposit compliance smoothly.
Schedule a Property Law Consultation
Facing a tenant dispute or need assistance structuring legally compliant lease agreements? Speak directly with a South Florida real estate attorney today:
Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
Website: mypersonalattorneys.com
Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and surrounding communities across Broward, Miami Dade, and Palm Beach Counties.
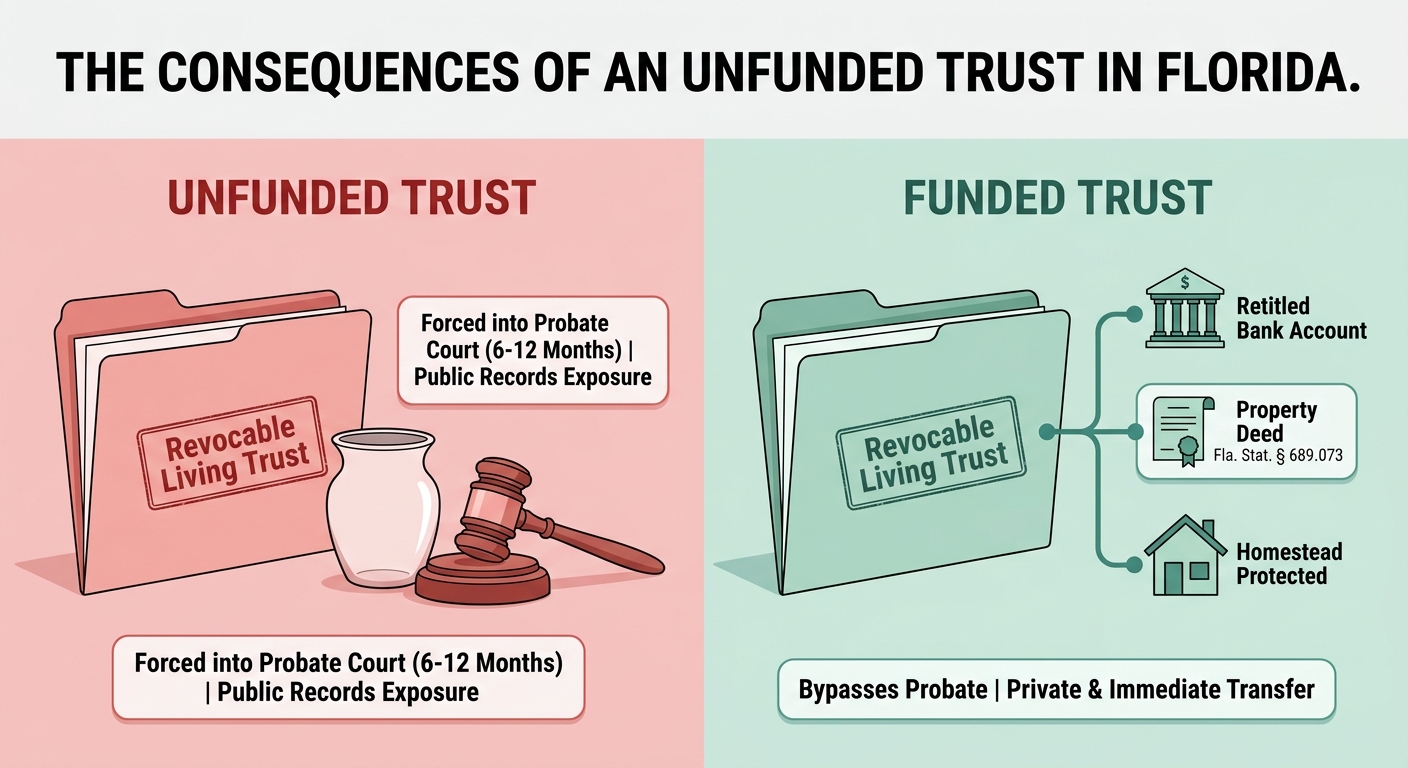
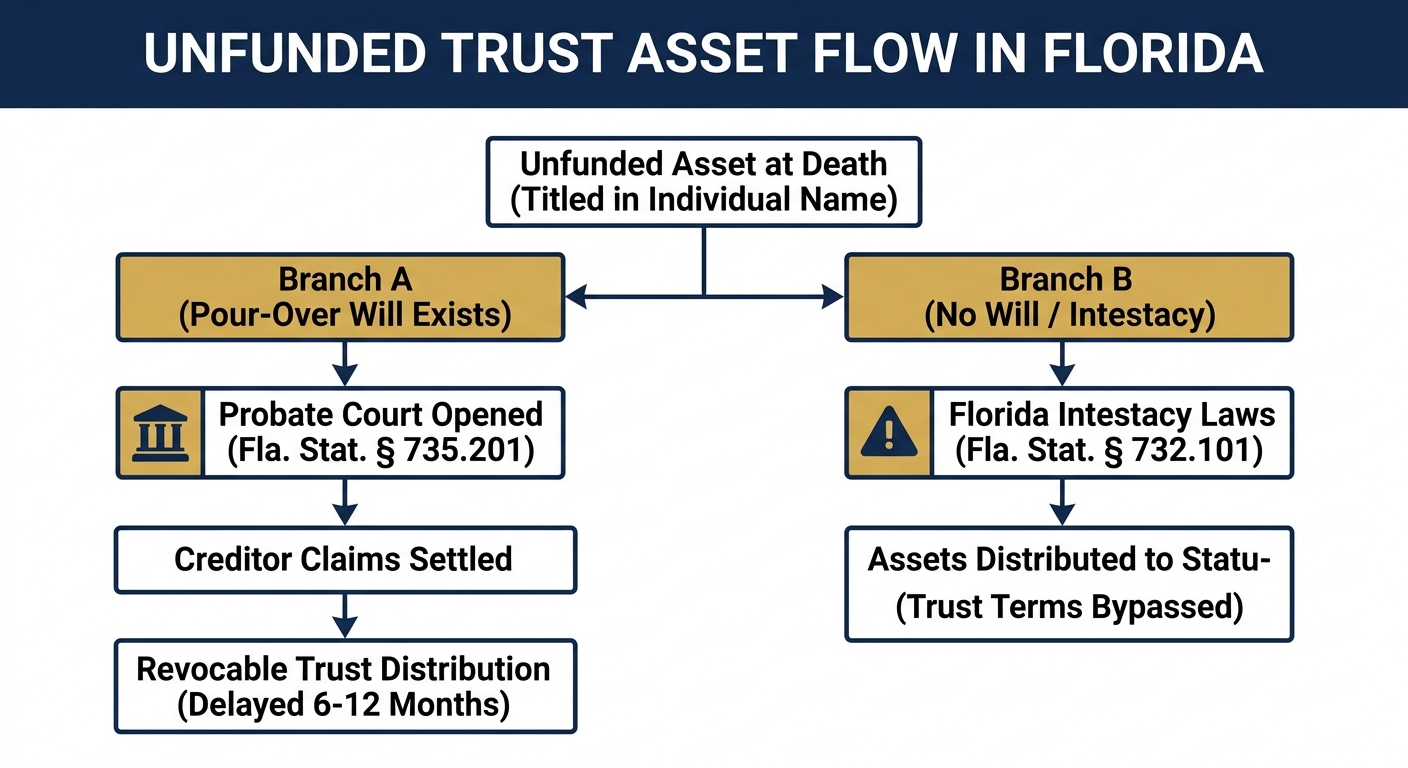
In Florida, a Revocable Living Trust is essentially an empty vessel with written instructions. Signing the trust document creates the legal framework, but if assets are not officially retitled into the name of the trust—a process known as funding—the trust cannot govern or transfer those assets upon your death or incapacity.
Here is an in-depth look at what happens in Florida when a trust remains unfunded, the legal consequences, and how Florida law resolves the gap.
1. The Core Problem: Loss of Probate Avoidance
The primary reason individuals establish revocable living trusts in Florida is to keep their assets out of probate court.
If Funded:Specifically, assets owned by ‘John Doe, as Trustee of the John Doe Revocable Trust’ pass directly to beneficiaries via the successor trustee according to the terms of the trust, bypassing probate court entirely.
If Unfunded: Any asset that remains in an individual’s personal name at death (e.g., “John Doe”) forms part of the decedent’s probate estate. The trust document holds no legal authority over these individually titled assets.
2. The Legal Safety Net: The Florida “Pour-Over Will”
To protect against unfunded or forgotten assets, a properly executed Florida estate plan includes a Pour-Over Will.
How it works: The Pour-Over Will acts as a catch-all safety net. It states that any asset remaining in the individual’s name at death should be transferred (or “poured over”) into the trust.
The Catch:A Pour-Over Will must go through Florida Probate Court.
The Process:During this process, the court appoints a Personal Representative to collect the unfunded assets, satisfy valid creditor claims under Florida Probate Rules, and then transfer the remaining net assets to the trustee to distribute according to the trust’s instructions.
The Outcome: The wishes outline in the trust are eventually honored, but the estate experiences the exact court delays (6 to 12+ months), public record disclosures, and legal/court costs that the trust was designed to prevent.
3. What Happens If There Is No Pour-Over Will?
If a trust is unfunded and the creator (settlor) dies without executing a Pour-Over Will (or any valid Will):
Intestacy Laws Take Over: The unfunded assets pass according to Florida’s intestate succession laws (Fla. Stat. § 732.101 et seq.), which default to statutory family order (surviving spouse, adult children, parents, siblings).
Accidental Disinheritance:Furthermore, the trust’s provisions, such as leaving equal shares to children, funding charities, or holding money in trust for minors, are bypassed completely for those unfunded assets.
Key Complications Specific to Unfunded Trusts in Florida
Consequently, if real estate is not deeded to the trust using a properly drafted Quitclaim or Warranty Deed (specifying trust powers under Fla. Stat. § 689.073), the home remains individual property.
Upon death, the homestead therefore requires a court proceeding (a Petition to Determine Homestead) to pass free of claims to legal heirs, regardless of what the trust document outlines.
B. Loss of Incapacity Protection
A key function of a Florida revocable trust is managing assets if the creator becomes incapacitated (e.g., due to dementia or stroke).
Funded Trust: The successor trustee steps in smoothly to manage trust assets without court involvement.
Unfunded Trust: The successor trustee has no authority over individually owned bank accounts or real estate. Family members must instead rely on a Durable Power of Attorney or petition a Florida court for a costly Guardianship proceeding.
C. Exposure of Financial & Personal Privacy
Once probate is opened to catch unfunded assets, the estate inventory, financial balances, names of heirs, and trust references become part of the public court record in the county where the probate is filed.
Summary of Consequences
Scenario
Fully Funded Florida Trust
Unfunded Trust (with Pour-Over Will)
Unfunded Trust (NO Pour-Over Will)
Probate Required?
No (Bypasses court entirely)
Yes (Formal or Summary Administration required)
Yes (Must go through Intestate Probate)
Distribution Time
Immediate or within weeks
6 to 12+ months
6 to 12+ months
Privacy
Private (Kept out of court records)
Public (Will and asset inventories filed with court)
Public (Filed with court)
Who Inherits?
Trust Beneficiaries
Trust Beneficiaries (after probate completion)
Statutory Heirs under Florida Intestacy Laws
How Funding Is Completed in Florida
To fund a trust properly under Florida law:
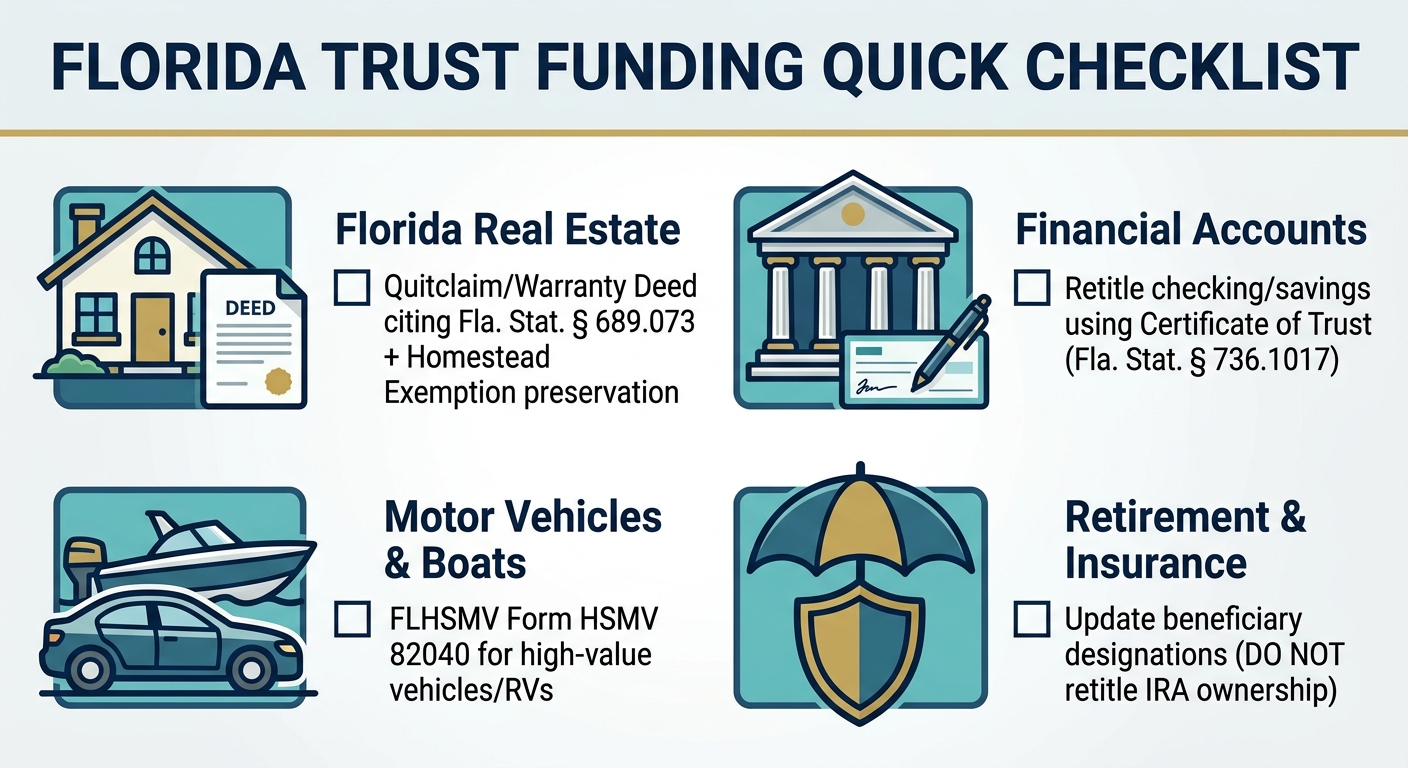
Real Estate: Draft and record a deed transferring title from the individual to the trust in the county where the property is located.
Financial Accounts: Change account ownership at banks and brokerages to the trust’s name.
Beneficiary Designations: Update primary or contingent beneficiary forms for life insurance policies, retirement accounts (IRAs/401ks), or Pay-on-Death (POD) accounts where appropriate.
Florida Revocable Living Trust Funding Checklist
A Revocable Living Trust cannot avoid probate or manage assets until those assets are retitled into the trust’s name. Follow this streamlined checklist to ensure your trust is properly funded under Florida law.
Essential Prerequisites
Certificate of Trust (Fla. Stat. § 736.1017): Provides banks, brokers, and title companies proof of trustee authority without exposing private beneficiary details.
Standard Trust Titling Format: [Trustee Name(s)], Trustee(s) of the [Trust Name], dated [Execution Date]
Quick-Action Asset Checklist
1. Bank Accounts & Cash Assets
Checking & Savings: Present your Certificate of Trust at your bank to retitle existing accounts or open new trust accounts.
Certificates of Deposit (CDs): Confirm in writing first that the bank will waive early withdrawal penalties for trust transfers before retitling.
Safe Deposit Boxes: Execute a new lease naming the trust or trustee to ensure immediate successor access.
2. Florida Real Estate
Deed Execution: Record a Quitclaim or Special Warranty Deed transferring title to the trustee.
Statutory Protection (Fla. Stat. § 689.073):To be valid under Florida law, the deed must explicitly grant the trustee full power to sell, lease, or encumber property.”
Preserve Homestead Exemptions: Include homestead occupancy rights in the deed/trust to safeguard tax caps (Fla. Admin. Code 12D-7.011) and creditor exemptions (Fla. Const. Art. X, § 4).
3. Motor Vehicles & Vessels (FLHSMV)
Selective Retitling: Under Fla. Stat. § 319.28, Florida allows heirs to transfer simple vehicle titles outside probate. We primarily recommend retitling high-value vehicles, RVs, or boats directly into the trust via FLHSMV Form HSMV 82040.
4. Investment Accounts & Non-Probate Assets
Brokerage Accounts: Submit ownership change forms to custodians (Schwab, Fidelity, Vanguard) along with your Certificate of Trust.
Life Insurance: Assign the trust as the primary or contingent beneficiary to ensure immediate, unencumbered payout administration.
Tax-Deferred Accounts (IRAs/401ks):However, do not retitle ownership, as this triggers immediate tax liabilities. Instead, update beneficiary designations carefully following SECURE Act 2.0 guidelines.
Complete Your Trust Execution with Experienced Counsel
Ensure your real estate, financial accounts, and business assets are properly structured under Florida law. Contact our South Florida estate planning team today:
Direct Telephone: (954) 866-4878 | Toll-Free: 954-866-HURT
Coral Springs Office: 9625 W. Sample Rd, Coral Springs, FL 33065
Fort Lauderdale Office: 2933 W. Cypress Creek Rd, Suite 201, Ft. Lauderdale, FL 33309
Website: mypersonalattorneys.com
Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all surrounding areas of Broward County
Florida does not require every homebuyer to hire an attorney, but legal review can be valuable before signing a purchase contract. A real estate attorney can identify contractual, title, ownership, and closing issues that may affect your rights as a buyer.
For a home purchase in Coral Springs or elsewhere in Broward County, the legal review may involve:
Title: Examining the ownership history and identifying liens, judgments, probate issues, defective deeds, easements, or other recorded interests.
Deed and ownership: Determining how the property will be titled and whether the proposed ownership structure fits the buyer’s circumstances.
Closing: Reviewing documents and addressing unresolved legal issues before ownership transfers.
Florida homestead: Evaluating homestead considerations when the property will be the buyer’s primary residence.
Estate planning: Considering how the new property fits into the buyer’s will, trust, and broader estate plan.
Probate: Identifying potential probate issues when the property was inherited or when its future transfer may involve an estate.
The timing of the legal review matters. A lawyer who examines the transaction before the purchase contract is signed may be able to identify provisions that become difficult to change later. Title and ownership issues should also be addressed before closing, when resolving them can become more complicated.
For buyers in Coral Springs and Broward County, these questions arise under Florida real estate law, but the appropriate legal strategy depends on the specific property, contract, ownership structure, and family circumstances.
When should you hire a real estate attorney?
Many buyers think about hiring a lawyer when they reach the closing table. By that point, the most important contractual decisions may already have been made.
The purchase contract establishes the legal framework for the transaction. It can determine the buyer’s rights concerning financing, inspections, repairs, deposits, title, closing dates, and termination.
The Florida Bar recommends consulting an experienced Florida real estate lawyer before signing a purchase contract. Its consumer guidance explains that important provisions can become difficult to change once the agreement has been signed.
That timing matters whether you are buying a home in Coral Springs, Fort Lauderdale, Parkland, Coconut Creek, or another Broward County community.
Suppose an inspection later reveals substantial roof damage. The buyer may want the seller to make repairs or provide a credit. Whether the buyer can demand either remedy depends on the contract and the circumstances surrounding the transaction.
The same principle applies to financing problems, delays, title defects, and disputes about property condition.
A lawyer who reviews the agreement before signature can explain what the buyer has agreed to and identify provisions that deserve attention.
What does a real estate attorney do for a homebuyer?
The work depends on the transaction.
A real estate attorney may review the purchase agreement, examine title records, review the deed, address liens and judgments, examine closing documents, advise on ownership, and represent the buyer if a dispute develops.
Some transactions require little legal intervention after the contract and title are reviewed. Others become complicated because of the property’s history.
A house in Broward County may have changed hands several times. A previous owner may have died. A divorce may have affected ownership. An old mortgage may remain in the public record. A judgment may have attached to an owner’s interest. A deed may contain an error.
The current seller may have no knowledge of any of these issues.
That does not necessarily prevent the sale. It does mean that the issue should be identified and resolved before the buyer accepts the property.
For a buyer purchasing a home in Coral Springs, the property’s recorded history deserves the same attention as its current condition.
Why title matters when buying a house
A real estate listing tells you who is selling the property. It does not establish the entire legal history of the property.
A title examination looks at recorded documents affecting ownership. Depending on the property, those records may include deeds, mortgages, liens, judgments, probate documents, and other instruments.
Florida law governs the recording of interests in real property. Florida Statutes Section 695.01 addresses the recording of conveyances, mortgages, and other interests in land and explains when recorded instruments have priority against certain creditors and subsequent purchasers.
For a buyer, the practical issue is whether the seller can deliver the ownership interest required by the purchase contract.
Consider a property that has passed through several generations.
The owner listed on the tax record may have inherited the house from a parent. That parent may have inherited it from someone else. At some point, an estate may have been administered incorrectly or a deed may have failed to include someone whose interest mattered.
The problem can remain hidden until the property is sold.
A title examination can reveal that history.
This is particularly relevant in established Broward County neighborhoods, where some properties have changed ownership several times over many years.
What happens when the seller inherited the house?
Inherited property can create title questions that do not appear in an ordinary residential sale.
If the seller acquired the property through an estate, the circumstances surrounding that transfer may need to be examined. The buyer may need documentation showing how ownership passed from the deceased person to the current seller.
Probate can therefore become part of a real estate transaction.
This is one reason real estate law and probate law sometimes meet in the same file.
A buyer does not need to become an expert in probate procedure. The important question is whether the person selling the property has the legal authority to transfer the interest the buyer expects to receive.
If that authority is unclear, the transaction may need additional documentation or court action before closing.
A buyer should not assume that an inherited property has a clean title simply because the seller has lived there for years.
The deed deserves careful attention
The deed is the document that transfers the seller’s interest in the property.
Buyers sometimes give it little attention because the purchase agreement and mortgage receive most of the discussion. The deed deserves its own review.
The buyer should understand what interest is being conveyed and who will receive it.
That second question is particularly important.
A person buying a house alone may have a straightforward ownership arrangement. A married couple may have different estate planning concerns. Two unmarried people purchasing together may need to consider what happens if one owner dies or wants to sell.
Parents sometimes purchase property with adult children. Some buyers consider a trust or another ownership arrangement.
Each situation raises different legal questions.
The answer should be based on the buyer’s circumstances rather than a generic preference about how property should be titled.
How you take title can affect your estate
Buying a house creates an asset that may eventually become part of your estate.
The way that asset is owned can affect what happens after death.
Certain forms of ownership can affect whether an interest passes through probate. Other ownership arrangements may require the property to be addressed through the owner’s estate.
This is why the deed and the estate plan should be considered together.
A person might have a carefully prepared will but never review whether the way the person’s property is titled supports the intended estate plan.
That can create problems later.
The purchase of a home is therefore a useful point to review the larger ownership picture.
For a Coral Springs homeowner purchasing a primary residence, that conversation may also involve Florida homestead law.
Florida’s homestead laws deserve special attention when the property will be the buyer’s primary residence.
Florida provides significant legal protections for qualifying homestead property. The state also has specific rules concerning what happens to homestead property after the owner’s death.
Florida Statutes Section 732.401 addresses the descent of homestead property when an owner dies. Section 732.4015 places restrictions on the owner’s ability to devise homestead property when certain family members survive the owner.
These rules can affect surviving spouses and children.
For example, when a Florida homeowner dies while survived by a spouse and descendants, the disposition of the homestead may be governed by statutory rules rather than by whatever result the owner assumed a will would produce.
The details depend on the family and ownership circumstances.
That is why homeowners in Coral Springs and Broward County should not assume that a will alone determines what happens to their Florida homestead.
Can a will control who receives your house?
Sometimes. Florida law can limit what a homeowner may accomplish through a will when the property qualifies as homestead.
The owner’s family situation matters.
The ownership structure matters.
The type of property matters.
The timing of transfers can matter as well.
Florida Statutes Section 732.4015 contains specific restrictions concerning the devise of homestead when a spouse or minor child survives the owner. Section 732.401 also establishes rules concerning descent when a Florida resident dies without a valid disposition controlling the property.
This is one reason estate planning should be based on the actual assets a person owns.
A will should not be viewed in isolation from deeds, trusts, beneficiary arrangements, and Florida’s property laws.
Should you put your house in a trust?
A trust can be useful in some estate plans. It is not the right ownership arrangement for every homeowner.
The decision depends on what the owner wants the estate plan to accomplish.
A revocable living trust, for example, may be considered as part of an incapacity and estate administration plan. Other trusts can serve different purposes.
The important question is whether a particular trust arrangement fits the person’s property, family circumstances, and estate planning objectives.
Florida also has specific rules concerning transfers of homestead property into trusts and other lifetime transfers. Florida Statutes Section 732.4017 addresses certain transfers of homestead property and explains circumstances affecting the way the property is treated under the homestead rules.
That makes professional review useful before changing the title to a Florida home.
A homeowner should understand the consequences of the transfer before signing a new deed.
What if the inspection reveals serious damage?
A home inspection and a legal review serve different purposes.
An inspector examines the physical condition of the house. An attorney examines the legal rights and obligations created by the transaction.
Suppose an inspection reveals structural damage.
The buyer may want the seller to make repairs. A buyer may prefer a price reduction. The buyer may want a credit at closing. The buyer may decide that the property is no longer worth purchasing.
The purchase agreement determines which options are available.
An inspection report does not automatically give the buyer a right to cancel the transaction.
The contract may contain deadlines governing inspection objections. It may establish particular procedures for repairs or termination. Missing those deadlines can affect the buyer’s rights.
A lawyer can explain the relevant provisions before the buyer takes action.
What happens when a title search reveals a lien?
A lien does not always mean the buyer has to abandon the transaction.
The first step is understanding what the lien is and whose obligation created it.
A mortgage may need to be satisfied at closing. A judgment may require resolution. A construction lien may involve a contractor or subcontractor. An estate matter may require additional documentation.
The appropriate solution depends on the problem.
This is where title work becomes practical rather than abstract. The buyer needs to know whether the defect can be resolved before closing and whether the title company will insure the buyer’s intended ownership.
A buyer should also understand any exceptions listed in the title commitment.
Accepting an exception without understanding it can leave the buyer with a title issue that was visible before closing.
Is title insurance enough?
Title insurance provides protection against covered title risks under the terms of the policy.
It does not perform the same function as an attorney representing the buyer.
The Florida Bar explains that a title examination generally precedes issuance of a title insurance policy. A title commitment identifies requirements that must be satisfied before the policy can be issued and lists exceptions to coverage.
Those exceptions deserve attention.
A buyer should know what the policy covers and what it does not cover.
The buyer should also know who represents the buyer.
A closing attorney may be involved in the transaction without representing the buyer personally. The Florida Bar specifically advises consumers to determine who the closing attorney represents.
If you want independent legal advice, ask that question before closing.
When should a Broward County homebuyer consider legal representation?
Some circumstances call for particular caution.
Consider speaking with a Florida real estate attorney when:
The purchase contract contains provisions you do not understand.
The seller inherited the property.
The property has been involved in probate.
The title search identifies a lien or judgment.
A previous deed appears defective.
A divorce affected ownership.
You are buying with someone who is not your spouse.
You are considering buying the property through a trust or business entity.
The house will be a major part of your estate.
The inspection reveals serious defects.
The seller disputes a repair obligation.
The transaction involves seller financing.
The property has unusual easements or restrictions.
A dispute develops before closing.
You are unsure how the property should be titled.
These circumstances are not limited to any particular Broward County neighborhood. They can arise in a Coral Springs purchase just as they can in a transaction elsewhere in South Florida.
The common factor is uncertainty.
A buyer does not need to wait until a dispute reaches court before asking a lawyer to review the transaction.
What should you bring to the attorney?
The purchase contract is the obvious starting point.
If you have not signed it, bring the proposed agreement.
If you have already signed it, bring the complete version along with any amendments.
Other useful documents can include the title commitment, inspection report, seller disclosures, survey, mortgage documents, homeowners association documents, and written communications about repairs.
If the property was inherited, information about the estate can also be important.
If you are purchasing the property as part of an estate plan, bring the relevant estate planning documents.
The attorney also needs to know what you intend to do with the property.
Will it be your primary residence?
Will you own it alone?
Will someone else share ownership?
Do you expect to leave the property to your children?
Are you considering a trust?
Those answers can change the legal analysis.
What does this have to do with probate?
A house can become one of the largest assets handled by an estate.
When the owner dies, the legal treatment of that property depends on how it was owned and the circumstances surrounding the owner’s death.
Some properties pass through probate. Others may pass through a different legal mechanism. Homestead can create additional rules.
This is why the deed signed at the time of purchase can become relevant years later in an estate administration.
A buyer may be thinking about a mortgage and a move.
An estate planning attorney may also need to think about incapacity, death, family rights, and the eventual transfer of the property.
Both perspectives concern the same asset.
For families in Coral Springs and throughout Broward County, that connection can be particularly useful when a home is expected to remain in the family.
A house can create legal consequences long after closing
The closing date is only one point in the property’s legal history.
The deed remains part of the public record. The mortgage may remain for decades. The property may become subject to homestead protections. Ownership may change through marriage, divorce, death, or another transfer.
The house may eventually become part of a probate estate.
That is why a home purchase can be a useful time to review an estate plan.
If you live in Coral Springs or elsewhere in Broward County, the attorney reviewing your purchase should understand the Florida laws that govern the property and your ownership interest.
The goal is to understand the legal consequences before they become difficult to correct.
Questions to ask before signing a purchase contract
A buyer does not need a law degree to ask useful questions.
Start with these:
Who owns the property now?
The answer should be supported by the title records.
Can the seller deliver the title required by the contract?
A title examination can identify issues that need attention.
What happens if the inspection reveals a serious problem?
The answer should come from the purchase agreement and applicable law.
What happens if financing is delayed or denied?
The contract should establish the buyer’s rights in that situation.
Who will own the property after closing?
The deed should reflect the intended ownership arrangement.
What happens to the property if one owner dies?
That question can bring estate planning into the discussion.
Does the property qualify as homestead?
If it will be the buyer’s primary residence, Florida’s homestead laws deserve attention.
Does my estate plan account for this property?
If the house will be a significant asset, the answer should be clear.
The right legal question is often a little earlier
Homebuyers usually have plenty of practical questions.
How much will the mortgage cost?
When can we move in?
Did the inspection find anything serious?
Are the repairs finished?
Those questions matter.
There is another question worth asking before signing:
Do I understand the legal rights I am acquiring and the obligations I am accepting?
If the answer is uncertain, a Florida real estate attorney can review the transaction before the buyer becomes committed to terms that may be difficult to change.
For buyers in Coral Springs and throughout Broward County, that conversation can also include estate planning and probate considerations when the property is expected to remain a significant family asset.
A home purchase creates ownership.
The way that ownership is established can matter for years afterward.
Frequently Asked Questions
Do I need a real estate attorney to buy a house in Florida?
Florida does not require every residential buyer to hire a lawyer. The Florida Bar recommends that prospective buyers consult an experienced Florida licensed real estate attorney before signing a purchase contract. Legal advice can be particularly useful when the transaction involves title questions, unusual contract terms, probate, ownership concerns, or estate planning.
What does a real estate attorney check when buying a house?
A real estate attorney can review the purchase contract, examine title records, review the deed and closing documents, identify liens or other title problems, advise on ownership, and address disputes that arise before closing.
Should I hire an attorney before signing a purchase contract?
If you want legal advice about the agreement, reviewing it before signing gives the attorney an opportunity to identify provisions that could affect your rights. The Florida Bar specifically recommends consulting a Florida real estate lawyer before signing a purchase contract.
Can buying a house affect my estate plan?
Yes. The way a home is owned can affect what happens to the property during incapacity and after death. Florida also has special rules concerning homestead property.
Does a will determine who receives my Florida home?
A will may control some aspects of an estate, but Florida homestead law can restrict how a homestead property may be devised when a surviving spouse or minor child is involved. The ownership structure and family circumstances need to be considered.
Can a house become part of probate?
Yes. Real estate can become part of a probate estate when its owner dies, depending on the ownership structure and circumstances. Property that belonged to a deceased owner may therefore require probate administration before it can be transferred or sold.
Is a title search the same as a home inspection?
No. A home inspection examines the physical condition of the property. A title examination investigates ownership and recorded interests affecting the property.
Does title insurance replace a real estate attorney?
No. Title insurance protects against covered risks under the policy. An attorney can provide legal advice about the contract, title, ownership, closing documents, and other legal issues affecting the buyer.
Should I discuss estate planning when buying a house?
It can be useful when the property will be a significant asset or when the buyer has specific plans for its future ownership. The purchase may be a good opportunity to review the relationship between the new property, the deed, and the existing estate plan.
Can I put my Florida home into a trust?
A Florida homeowner may be able to transfer a home into a trust, but the consequences depend on the type of trust, the property, the owner’s circumstances, and Florida homestead law. Legal advice should be obtained before changing the title.
Talk with an attorney before signing
A home purchase can involve questions about contracts, title, ownership, homestead, probate, and estate planning.
Preplanning your final arrangements is one of the most effective ways to lift an emotional and financial burden from your family. Documenting your wishes ensures that your funeral or cremation is handled according to your exact preferences. And without forcing grieving relatives to guess or overspend.
However, moving from preplanning (recording your wishes) to prepaying (funding those arrangements through a preneed contract) introduces complex financial and legal regulations.
For seniors and families in Coral Springs and throughout Broward County, navigating Florida’s preneed laws requires careful oversight. Without proper legal structuring, prepaying can expose your money to provider insolvency. It can also create inflexibility if you relocate, or unintended tax and Medicaid complications.
The Critical Legal Distinction: Preplanning vs. Preneed Contracts
Under Florida law, terminology matters significantly:
Preplanning (Preneed without funds): This is simply documenting your choices. Things as casket types, service locations, and disposition preferences—with a licensed funeral home, with zero money changing hands upfront.
Preneed Contract: This is a legally binding agreement where you pay for goods and services in advance.
Under Florida Statutes Chapter 497, preneed contracts are heavily regulated to protect consumers. But the specific funding mechanism dictates how secure your money actually is.
How Florida Law Protects (and Exposes) Your Prepaid Funds
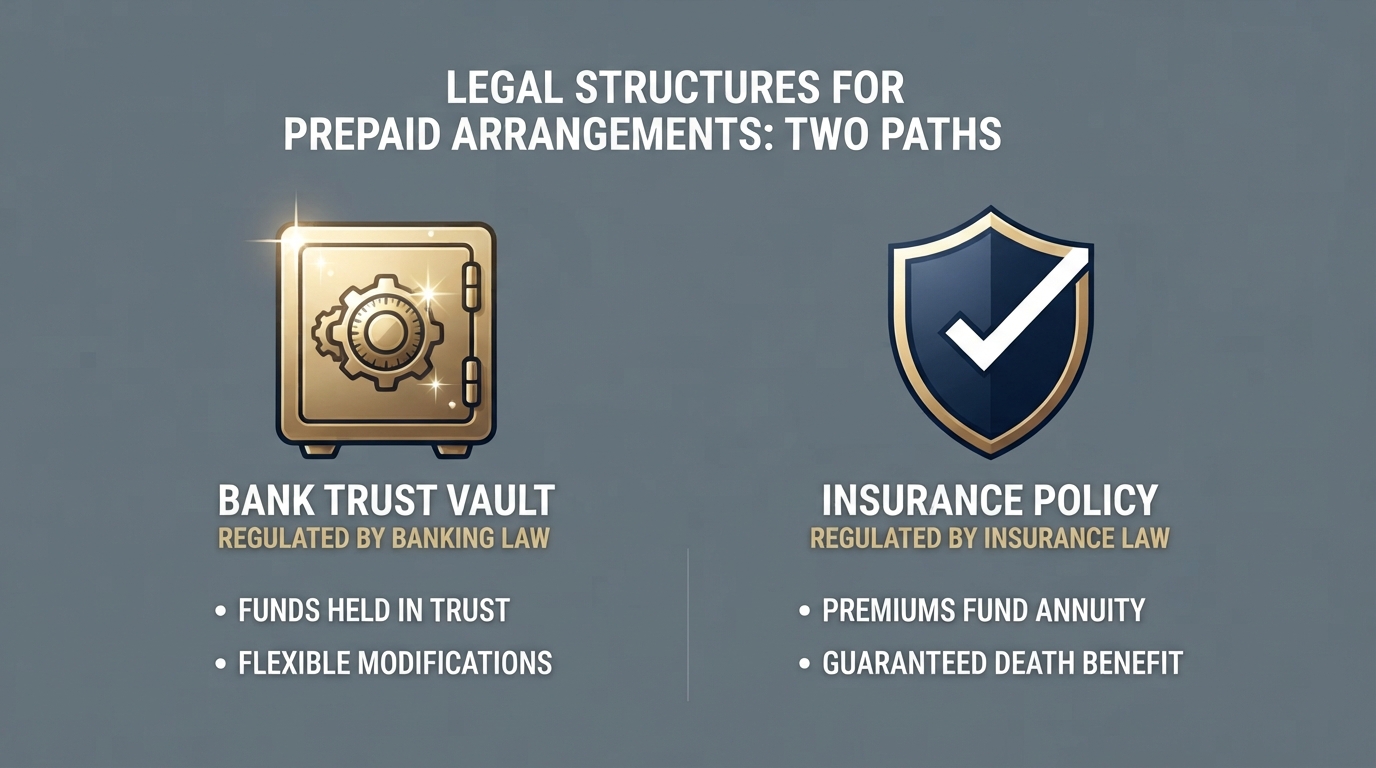
When you purchase a preneed contract from a licensed funeral home in Florida, the provider must handle your money using one of two primary statutory methods:
Under a trust arrangement, a portion of your payment (at least 70% of the service portion and specific percentages for merchandise) must be deposited into an independent trust. It should be managed by a financial institution, not kept in the funeral home’s operating account.
The Risk: Legally, trust-funded monies can leave the purchaser or their estate treated as an unsecured creditor. Especially if the funeral home faces financial distress or closes down.
2. Life-Insurance-Funded Preplans
An alternative approach involves funding the preneed agreement through a specialized final expense. Another option can be a whole life insurance policy where the funeral home is named as the beneficiary upon death.
Preneed Contracts and Medicaid Planning in South Florida
For many older adults in Broward County, preplanning intersects directly with Medicaid long-term care planning.
To qualify for Medicaid, applicants must meet strict asset limits (typically $2,000 for an individual). Florida law permits individuals to prepay funeral and burial expenses to reduce countable assets legally.
However, to count as an exempt asset for Medicaid purposes, a preneed funeral contract must be irrevocable.
The Trade-Off: Making a contract irrevocable means you permanently surrender the right to cash it out or change your mind for a refund.
The Legal Role: An experienced elder law attorney ensures that irrevocable burial trusts or preneed contracts are structured precisely to satisfy Department of Children and Families (DCF) guidelines without triggering unintended penalties.
Key Protections Every Consumer Must Demand
Before signing any preneed agreement or paying a funeral home in advance, protect your interests by verifying these statutory requirements:
Insist on the General Price List (GPL): Federal Trade Commission (FTC) rules and Florida law require providers to give you itemized price lists before you commit.
Review Portability Terms: If you move out of South Florida or wish to switch providers later, check whether your contract can be transferred cleanly without severe financial penalties.
Understand the Cancellation Window: Florida law provides a statutory right to cancel a preneed contract within 30 days of execution for a full refund. After that, cancellation terms depend strictly on whether the contract is revocable or irrevocable.
Get Price Guarantees in Writing: Ensure the contract specifies whether it is a “guaranteed” plan (meaning no additional out-of-pocket costs for your family at the time of death for the items listed) or a non-guaranteed plan that leaves families exposed to inflation gaps.
Frequently Asked Questions
Can I get my money back if I prepay my funeral in Florida?
If your preneed contract is revocable, you may cancel it, though refunds are subject to statutory formulas and trust rules under Chapter 497. If the contract was made irrevocable for Medicaid planning purposes, it cannot be canceled or refunded.
What happens if my prepaid funeral home goes out of business?
Florida maintains the Preneed Funeral Contract Consumer Protection Trust Fund to provide a safety net and claims process for consumers if a licensed preneed seller fails or closes. Working with an established, financially stable provider minimizes this risk.
Is there a limit to how much I can prepay for burial arrangements under Medicaid?
While Medicaid allows unlimited pre-funding through properly structured irrevocable preneed burial contracts, separate designated burial cash accounts are typically capped at $2,500. Every dollar must comply strictly with Florida Medicaid asset rules.
Can a preneed funeral plan be transferred to another funeral home?
It depends on the funding mechanism. Insurance-funded plans are often portable nationwide, whereas trust-funded contracts tied to a specific local funeral home can involve transfer hurdles or administrative fees.
Schedule a Consultation with Our Coral Springs Elder Law Attorneys
Integrating funeral preplanning into a comprehensive estate or Medicaid plan requires balancing emotional peace of mind with strict financial protection.
Yes, creditors can sometimes take money from a trust in Florida, but their rights depend on who owes the debt and how the trust is structured. Florida law generally allows creditors to reach assets in a revocable trust during the creator’s lifetime. A valid spendthrift provision in an irrevocable trust can protect a beneficiary’s undistributed interest from many ordinary creditors, although statutory exceptions apply.
When can creditors reach trust assets in Florida?
Revocable trusts: Creditors can generally pursue assets in a revocable trust when the person who created it owes the debt.
Spendthrift trusts: A valid spendthrift provision can protect a beneficiary’s undistributed interest from many ordinary creditors.
Distributed inheritances: Once the trustee pays the beneficiary, the funds may become subject to ordinary collection procedures.
Exceptions: Certain support claims and other legally recognized circumstances can permit creditors to reach otherwise protected interests.
Fraudulent transfers: Florida law allows qualifying transfers intended to hinder, delay, or defraud creditors to be challenged.
These rules are governed primarily by Part V of Florida’s Trust Code, including the provisions addressing spendthrift trusts and claims against revocable trust assets. The sections below explain how each rule works and what it means for beneficiaries and trustees in Coral Springs and Broward County.
Key points for Florida residents:
A creditor generally has broader access to assets in a revocable trust while its creator is alive.
A valid spendthrift provision can restrict a beneficiary’s creditors from reaching an undistributed trust interest.
Certain claims, including qualifying support obligations, may fall within statutory exceptions.
Money distributed to a beneficiary may lose some or all of its protection under trust law.
Transfers designed to hinder existing creditors can be challenged under Florida’s voidable transfer laws.
These rules matter when someone is planning an inheritance, administering a deceased relative’s estate, or responding to a creditor claim in Coral Springs or elsewhere in Broward County.
1. Can Creditors Reach Assets in a Florida Trust?
The first step is identifying whose debt is involved. Florida law does not treat the trust creator and the beneficiary as interchangeable.
When the person who created the trust owes the debt
A revocable living trust generally does not protect its assets from the creator’s creditors during the creator’s lifetime. Under Florida Statute § 736.0505, property in a revocable trust remains available to satisfy the claims of the settlor’s creditors.
A settlor is the person who creates and funds a trust. If that person can revoke the trust and recover its assets, the trust ordinarily does not place those assets beyond the reach of legitimate creditor claims.
Example: A Coral Springs homeowner transfers investment accounts into a revocable living trust. The homeowner later defaults on a substantial personal loan. The transfer alone does not prevent the lender from pursuing trust assets that remain subject to the homeowner’s control.
The analysis can change after the creator dies or when a trust is genuinely irrevocable. Even then, the specific statutory rules and the circumstances surrounding the transfer must be examined.
When a beneficiary owes the debt
The rules can be considerably more protective when the debtor is a beneficiary of an irrevocable trust created by someone else.
Under Florida Statute § 736.0502, a valid spendthrift provision can prevent a beneficiary from voluntarily transferring the protected interest. It can also prevent most creditors from attaching that interest before the trustee distributes the money.
Example: A father establishes an irrevocable trust for his adult daughter. The trust contains an enforceable spendthrift provision. The daughter later falls behind on credit card payments. A card issuer generally cannot seize her undistributed beneficial interest merely because she owes money.
That does not mean the trust is immune from every claim. Florida law recognizes exceptions, and a creditor may have other remedies depending on the facts.
2. What Is a Spendthrift Trust in Florida?
A spendthrift trust contains language restricting a beneficiary’s ability to transfer the beneficiary’s interest. The restriction also limits the ability of creditors to reach that interest before the trustee distributes it.
Florida Statute § 736.0502 establishes the requirements for an enforceable spendthrift provision. The provision must restrain both voluntary and involuntary transfers of the beneficiary’s interest.
This distinction matters. A clause that merely expresses the creator’s hope that a beneficiary will manage money responsibly does not necessarily establish the statutory protection.
How spendthrift protection works
Suppose a trust holds $400,000 for a beneficiary who has accumulated substantial unsecured debt. The trustee must follow the trust’s terms when deciding whether and when to distribute funds.
If the trust contains an enforceable spendthrift provision, the beneficiary generally cannot assign the protected interest to a creditor. The creditor ordinarily cannot attach that undistributed interest either, subject to the exceptions established by law.
The trustee must still administer the trust according to its terms and applicable fiduciary duties. Spendthrift language does not give a trustee unlimited discretion to disregard the beneficiary’s rights.
Does every irrevocable trust provide creditor protection?
No. Irrevocability alone does not guarantee that trust assets are protected from every creditor.
The trust’s language matters. So does the identity of the debtor. A trust created by a third party for a beneficiary presents a different legal situation from a trust a debtor creates for personal benefit.
A transfer into an irrevocable trust can also be challenged if it violates Florida’s voidable transfer laws. The relevant provisions appear in Florida Statutes Chapter 726.
The source of the money matters as well. A court will examine the actual arrangement rather than rely exclusively on the label attached to the trust.
3. Revocable Trusts vs. Irrevocable Trusts
The difference between revocable and irrevocable trusts is central to creditor protection.
Feature
Revocable trust
Irrevocable trust
Can the creator generally revoke it?
Yes, subject to the instrument and law
Generally not unilaterally, although some arrangements permit modification
Creditor access to the creator’s assets
Generally available during the creator’s lifetime
Depends on the creator’s retained rights and applicable law
Protection for a beneficiary
Depends on the arrangement and stage of administration
A valid spendthrift provision can protect an undistributed interest from many creditors
Can every creditor claim be blocked?
No
No
Can the transfer be challenged?
Depending on the circumstances
Yes, including under voidable transfer laws
Revocable Living Trusts
Revocable living trusts are popular for good reason. They let people decide how their property will be handled after death without necessarily putting their families through probate. They can also make things easier if the person who created the trust becomes unable to manage their own affairs.
But there’s an important limitation when creditors are involved. Under Florida Statute § 736.0505, assets in a revocable trust are generally available to the creator’s creditors during their lifetime. The creator can still revoke the trust and take the property back, so the transfer does little to separate those assets from their personal financial obligations.
This is where people can get caught out. A revocable trust may be perfectly suitable for managing an estate, yet do very little to protect the creator’s property from a creditor pursuing an unpaid debt. Those are two different goals, and a trust designed for one should not be mistaken for a solution to the other.
Irrevocable Trusts
Irrevocable trusts work differently because the person who creates one generally gives up the ability to take the assets back whenever they want. Depending on the trust’s terms, the property may be managed for beneficiaries who cannot demand an immediate distribution. That separation can make it harder for certain creditors to reach the assets.
Of course, the details matter. A trust does not become immune to creditors simply because its creator calls it irrevocable. The rights retained by the creator can affect the protection available, and Florida law allows creditors to challenge certain transfers.
Consider someone who moves valuable property into an irrevocable trust after learning that a lawsuit may be coming. Under Florida’s Uniform Voidable Transactions Act, Chapter 726, a creditor may challenge the transfer if the legal requirements are satisfied. A court can look at the circumstances and determine whether the arrangement was used to put assets beyond a creditor’s reach.
For anyone planning an estate, the distinction matters. An irrevocable trust may provide stronger creditor protection, but that protection comes with restrictions on what the creator can do with the property later. It is worth understanding those restrictions before transferring assets that may be difficult or impossible to recover.
4. Which Creditors Can Reach a Beneficiary’s Trust Interest?
Florida law provides meaningful protection for many trust beneficiaries, but it does not make every trust interest unreachable.
Ordinary unsecured creditors
Credit card companies and personal loan lenders generally cannot attach a beneficiary’s interest before distribution when an enforceable spendthrift provision applies.
That protection is not a blanket defense against every legal action. A creditor may still investigate whether an exception applies or whether the trust arrangement can be challenged.
Child support and spousal support
Florida Statute § 736.0503 establishes exceptions to spendthrift protection for certain claims. These include qualifying claims for support or maintenance of a beneficiary’s child, spouse, or former spouse.
The statute also addresses certain services that protect the beneficiary’s interest in the trust.
The precise claim and the statutory requirements matter. A creditor cannot assume that every family law judgment automatically overrides a spendthrift provision.
Government claims
Government claims require separate analysis. The availability of trust assets depends on the governing statute, the type of obligation, and the beneficiary’s rights under the trust.
For example, a claim involving taxes should not be analyzed as though it were an ordinary credit card debt. Federal collection rules may also be relevant.
Judgments and lawsuits
A creditor with a judgment does not automatically gain unrestricted access to every trust asset. The judgment establishes a legal claim, but collection still depends on the property involved and the law governing that property.
A court may need to determine whether the debtor has a present right to receive money or only a protected interest in future distributions.
5. What Happens When the Trustee Distributes the Money?
Distribution can change the analysis significantly.
Spendthrift protection generally applies to the beneficiary’s interest before the trustee transfers the money. Once funds reach the beneficiary, the creditor may be able to pursue them under ordinary collection law.
The outcome depends on where the money goes and whether another legal protection applies.
Money deposited into a personal bank account
Suppose a trustee distributes $50,000 to a beneficiary with outstanding credit card debt. The beneficiary deposits the money into a personal checking account.
The beneficiary should not assume that the original trust provision continues to protect the funds indefinitely. A judgment creditor may be able to pursue money in the account through lawful collection procedures.
Florida law provides exemptions for certain property and income. Those exemptions must be evaluated independently from the trust’s spendthrift clause.
Money used to buy another asset
Converting a distribution into another asset does not automatically preserve trust protection.
The result depends on the asset purchased and any applicable exemption. For example, Florida’s homestead protections may be relevant to a qualifying primary residence, but those rules have specific requirements and exceptions.
A beneficiary should not assume that purchasing a home with trust money makes the funds untouchable. The source of the money, the property’s use, and the applicable legal requirements all matter.
Money retained by the trustee
When the trustee has not distributed the money, the beneficiary’s creditors may have fewer collection options. The creditor must account for the trust terms and any applicable statutory exceptions.
The trustee should not make an improper distribution simply because a beneficiary is facing collection pressure. The trustee must follow the instrument and applicable law.
6. Can a Trustee Refuse to Distribute Money Because of a Creditor?
The answer depends on the trust’s distribution terms and the trustee’s legal duties.
Some trusts require distributions when specified conditions are met. Others give the trustee discretion to decide when distributions are appropriate.
A trustee cannot automatically withhold a mandatory distribution merely because the beneficiary has creditors. The trust instrument and Florida law determine what the trustee must do.
Discretionary distributions
Under Florida Statute § 736.0504, a creditor generally cannot compel a distribution that remains within the trustee’s discretion, subject to statutory exceptions.
For example, a trust may authorize distributions for a beneficiary’s health or education. The trustee must exercise that discretion according to the trust’s terms and fiduciary obligations.
A creditor generally cannot force the trustee to exercise discretion in the creditor’s favor simply because the beneficiary owes money.
Mandatory distributions
A trust may require a trustee to distribute a fixed amount at a specified age or on a defined date.
When a distribution becomes due, the legal position can differ from a situation in which the trustee has discretion. Florida Statute § 736.0506 addresses creditor claims involving certain overdue mandatory distributions.
The timing and wording of the trust are important. A beneficiary should not assume that an enforceable right to a distribution receives the same treatment as a purely discretionary interest.
What trustees should avoid
A trustee should not invent new restrictions simply to prevent a beneficiary’s creditor from collecting. The trustee should also avoid making an unauthorized distribution based on informal pressure from a beneficiary or creditor.
When a demand arrives, the trustee should review the instrument and determine whether the claimant has a legally enforceable right to the funds.
7. Can Creditors Challenge a Transfer Into an Irrevocable Trust?
Yes. Florida law permits certain transfers to be challenged when the transfer meets the legal requirements for a voidable transaction.
Under Florida Statutes Chapter 726, a court may examine the circumstances surrounding a transfer to determine whether it was made with actual intent to hinder, delay, or defraud a creditor. The statute also addresses certain transfers made without reasonably equivalent value when the debtor meets specified financial conditions.
A transfer made before financial trouble
A person who creates an irrevocable trust as part of a legitimate estate plan before any creditor dispute arises may present a different case from someone who transfers assets after receiving a lawsuit or collection demand.
Timing is relevant, but timing alone does not decide the outcome. The court may examine the debtor’s financial condition and other evidence surrounding the transaction.
A transfer made after a lawsuit begins
Suppose a business owner faces a substantial judgment and then transfers most personal assets into a trust for a family member.
The creditor may investigate whether the transfer was designed to obstruct collection. If the evidence supports a claim under Chapter 726, the creditor may seek a remedy through the court.
The trust’s irrevocable status does not automatically defeat that challenge.
A debtor who transfers property while concealing assets or giving misleading information may create additional legal exposure. The precise consequences depend on the conduct and the applicable law.
Anyone considering a trust transfer during an existing creditor dispute should obtain legal advice before moving property. A transfer that appears protective at first can become the basis of further litigation.
8. Florida Court Decisions That Help Explain Creditor Access
Statutory language establishes the basic rules, while court decisions illustrate how those rules operate in actual disputes.
Miller v. Kresser: Practical control did not defeat spendthrift protection
In Miller v. Kresser, 34 So. 3d 172 (Fla. 4th DCA 2010), Gary Kresser obtained a judgment of approximately $1.02 million against James Miller and his construction company. Unable to collect, Kresser pursued assets held in an irrevocable trust established for James by his mother. The trust contained a spendthrift clause and named James’s brother, Jerry, as trustee.
Although Jerry held formal authority over distributions, the trial court found that James effectively controlled the trust’s investments and operations. It invalidated the spendthrift protection and allowed Kresser to pursue trust assets, including the trust’s interest in property in Islamorada.
The Fourth District Court of Appeal reversed. It found that Jerry retained the legal authority to decide whether to distribute trust property. James could influence decisions, but he could not compel distributions. His practical involvement therefore did not, by itself, make the undistributed assets available to his creditor.
Why it matters: A creditor cannot necessarily seize trust assets because a beneficiary appears to control their management. The trust’s terms and the beneficiary’s enforceable rights are central to determining whether assets remain protected.
Zlatkiss v. All America Team Concepts: A valid judgment does not guarantee access to trust funds
In Zlatkiss v. All America Team Concepts, LLC, 116 So. 3d 525 (Fla. 5th DCA 2013), Robert and Linda Zlatkiss lent $350,000 to a company whose principal, Louis Steinmetz, personally guaranteed the loan. Steinmetz had represented that he had approximately $6.85 million available through a trust. When the loan went unpaid, the Zlatkisses sought recovery and challenged the constitutionality of Florida’s spendthrift trust protections after the trustee refused to release funds to satisfy the debt.
The Fifth District Court of Appeal upheld the protections. It explained that the constitutional right to access the courts allows creditors to pursue legal claims, but does not guarantee collection from every asset belonging to a debtor. Florida’s recognition of valid spendthrift trusts also predated the statutes challenged in the case.
Why it matters: A creditor may obtain a judgment against a debtor without gaining access to the debtor’s trust interest. For lenders, the case underscores the importance of determining whether a borrower can actually access trust assets before relying on them as a source of repayment.
In re Brown: A debtor could not shield an income interest in a trust she created
In In re Brown, 303 F.3d 1261 (11th Cir. 2002), Jane McLean Brown used an inheritance of approximately $250,000 to establish an irrevocable charitable remainder unitrust. She retained the right to receive annual payments equal to 7% of the trust’s value, while the remaining assets were designated for charitable beneficiaries. The trust included a spendthrift clause.
When Brown filed for Chapter 7 bankruptcy, she argued that the clause protected her interest from creditors. The Eleventh Circuit rejected that argument. Because Brown had created the trust for her own benefit and retained a right to income, she could not use the spendthrift provision to shield that interest in bankruptcy. Her retained income rights were available to the bankruptcy estate, although the trust principal itself was not available to satisfy her personal debts.
Why it matters: An irrevocable trust does not automatically protect every interest held by the person who created it. Courts may distinguish between property transferred irrevocably to others and income rights the creator retained for personal benefit.
What these decisions mean for Florida creditors and beneficiaries
These cases illustrate different limits on creditor access to trust assets. Miller examines practical control over a discretionary trust. Zlatkiss addresses the limits of collecting a judgment from protected trust interests. In re Brown concerns a debtor who created a trust while retaining an income interest.
The outcome depends on the trust agreement, the debtor’s legal rights, and the applicable law. Bankruptcy can introduce additional rules, so a decision arising under federal bankruptcy law should not automatically be treated as controlling every Florida collection dispute.
9. Household Debt and the Risk to Inheritances
An inheritance can arrive at an awkward time: a beneficiary may be dealing with unpaid debts just as money or property passes into their hands. The scale of household debt in the United States helps explain why this issue matters.
According to the Federal Reserve Bank of New York’s February 2026 household debt report, Americans owed approximately $18.8 trillion in household debt at the end of 2025. That balance grew by roughly $191 billion in a single quarter. The report also found that 4.8% of outstanding household debt was in some stage of delinquency.
These figures show the scale of the debt burden facing American households. They do not tell us how many Florida beneficiaries face collection claims, or how often creditors successfully reach trust assets. They do, however, provide context for a practical concern: when someone with unpaid debts inherits money, the legal protection surrounding that inheritance can make a substantial difference.
What these numbers mean for trust beneficiaries
A debt does not automatically give a creditor the right to seize trust assets. Florida law distinguishes between assets held in a trust and property a debtor owns or has the legal right to receive. A properly drafted spendthrift provision may protect a beneficiary’s undistributed interest from many creditors, subject to statutory exceptions.
That protection can change when a trustee distributes the funds. Once the inheritance reaches the beneficiary, it may become available to creditors under ordinary collection rules, depending on the circumstances and any applicable exemptions.
The figures above establish the financial context, not the legal outcome. Whether a creditor can reach an inheritance ultimately depends on the trust’s terms, the beneficiary’s rights, and the protections Florida law provides.
10. Common Misconceptions About Trusts and Creditors in Florida
Misconception 1: An irrevocable trust is immune from every creditor
Reality: Irrevocability does not eliminate all creditor rights. The creator’s retained interests, statutory exceptions, and potential challenges to the original transfer can affect the outcome.
Misconception 2: A revocable living trust protects the creator’s assets from personal debts
Reality: Florida Statute § 736.0505 generally allows creditors to reach assets in a revocable trust during the settlor’s lifetime.
A revocable trust may serve important estate planning purposes, but it should not be treated as a substitute for a valid creditor protection strategy.
Misconception 3: A beneficiary’s inheritance is protected forever
Reality: Spendthrift protection generally concerns the beneficiary’s interest before distribution. After receiving money, the beneficiary may face ordinary collection proceedings unless another protection applies.
Misconception 4: A creditor with a judgment can seize anything connected to the debtor
Reality: A judgment does not eliminate statutory protections. The creditor must still identify property that can legally be reached.
Misconception 5: A trustee can always refuse payment to keep creditors away
Reality: The trustee must follow the trust instrument. A mandatory distribution cannot automatically be withheld because the beneficiary has debts.
Misconception 6: Moving money into a trust after a lawsuit begins solves the problem
Reality: A creditor may challenge a transfer under Florida’s voidable transfer laws. The transaction can create further legal disputes rather than resolve the original debt.
Misconception 7: Trust protection and Florida homestead protection are the same
Reality: They are separate legal concepts. Florida’s homestead protections are governed by distinct constitutional and statutory rules, and the requirements depend on the property and circumstances.
11. Florida Homestead, Exemptions, and Other Protections
Trust law is only one part of the creditor analysis. Other Florida laws may protect particular assets or income, but those protections should not be assumed to apply automatically to inherited money.
Florida Homestead: When a Home Gets Special Protection
Florida’s homestead exemption is one of the state’s strongest forms of asset protection. Under the Florida Constitution, qualifying primary residences receive substantial protection against forced sale by many creditors. That can make a significant difference when someone faces a judgment and owns a home.
The protection has specific requirements and exceptions. In Havoco of America, Ltd. v. Hill (2001), a creditor argued that a debtor had used funds to acquire a homestead with the intent to keep those assets beyond creditors’ reach. The Florida Supreme Court concluded that the homestead exemption still applied under the circumstances, even though the purchase was allegedly motivated by creditor avoidance. The court explained that the constitutional protection could not be denied on that basis alone when the transaction did not fall within an established exception.
That ruling is powerful, but it is not a blanket permission to move any asset into a home and declare it untouchable. The property must qualify as homestead, and the legal circumstances matter. Nor does the decision mean that money held in a trust automatically receives homestead protection. The rules governing trust assets and those governing a qualifying residence are distinct.
Wage Exemptions: Your Paycheck May Have Protection of Its Own
Florida law also protects certain earnings from creditors. Under Florida Statute § 222.11, qualifying head of family earnings receive specific protections, subject to the statute’s requirements and exceptions.
These rules matter when a creditor seeks to garnish wages. They do not automatically extend to every dollar that later enters the same bank account. A beneficiary who receives a trust distribution should not assume that the payment qualifies as protected earnings simply because it will be used to cover ordinary living expenses.
The source of the money and the legal requirements for the exemption both matter. When wages and other funds are mixed together, identifying the protected portion may become more complicated.
Bankruptcy: A Different Set of Rules Can Change the Outcome
When a debtor files for bankruptcy, the analysis moves beyond ordinary state court collection procedures. Federal bankruptcy law determines what enters the bankruptcy estate and provides mechanisms for challenging certain transfers made before filing.
A trust that limits a creditor’s access under Florida law does not necessarily produce the same result in bankruptcy. The outcome depends on the debtor’s interest in the trust and the applicable bankruptcy rules. Transfers made before filing may also face scrutiny under federal law.
This is particularly important when someone creates a trust, transfers property into it, or retains rights to receive payments before seeking bankruptcy protection. The word irrevocable does not settle the question. The actual arrangement and the timing of the transactions must be examined.
Debt Collection Rights: Creditors Have Rules to Follow Too
Trust disputes are not the only legal issue a beneficiary may face. Collection communications can raise separate questions about what a debt collector is allowed to say or do.
However, rules governing collection conduct do not determine whether a creditor can legally reach a particular trust interest. A collector may be restricted in how it pursues a debt while still having a valid claim against assets available under applicable law. Conversely, a creditor’s right to collect a debt does not give it unlimited authority to seize protected property.
The important distinction: Asset protection and debt collection conduct are separate questions. A beneficiary needs to understand both the legal status of the assets and the limits on the creditor’s collection methods.
12. Practical Procedures When a Creditor Targets Trust Assets
A creditor demand involving a trust should be handled carefully. The trustee and beneficiary may have different rights and obligations, so each should understand their own position before responding.
Step 1: Identify the debtor
Determine whether the debt belongs to the trust creator, the beneficiary, or another person.
This is the first legal distinction to establish. A creditor pursuing the settlor may have rights that would not apply to an ordinary creditor of a beneficiary.
Step 2: Obtain and review the trust instrument
Locate the complete trust document and any amendments. Identify whether the trust is revocable or irrevocable and whether it contains a spendthrift provision.
Review the distribution terms as well. The trustee’s authority may differ depending on whether distributions are mandatory or discretionary.
Step 3: Determine whether the money has been distributed
Establish whether the assets remain in the trust or have already been transferred to the beneficiary.
This distinction may determine which creditor remedies are available. Keep records of the distribution date and the destination of the funds.
Step 4: Identify the creditor’s legal claim
Review the demand letter, judgment, court order, or other documents identifying the debt.
Determine whether the claim involves ordinary consumer debt, a support obligation, a tax liability, or another category that may trigger different rules. Do not assume every creditor has the same collection rights.
Step 5: Preserve relevant records
Keep copies of the trust instrument, account statements, distribution records, creditor correspondence, and any relevant court filings.
Do not destroy or alter records in response to a collection demand. Accurate documentation can help establish the nature and timing of the trust arrangement.
Step 6: Avoid informal promises or unauthorized distributions
A beneficiary should not promise a creditor access to trust money without understanding the legal position. A trustee should not make a distribution that conflicts with the trust instrument or applicable law.
If the creditor has served formal legal papers, observe the stated deadlines. Ignoring a court order or legal notice can create additional problems.
Step 7: Obtain legal advice when the claim is disputed
A Florida estate planning or trust litigation attorney can review the instrument and determine whether the creditor has a valid route to the assets.
Legal advice is particularly important when the trust creator retained control, a distribution is overdue, or the creditor alleges a fraudulent transfer.
Operational checklist for trustees
Before responding to a creditor demand, a trustee should:
Confirm the identity of the debtor and the nature of the claim.
Review the trust instrument and relevant amendments.
Determine whether the interest is subject to a valid spendthrift provision.
Establish whether the requested funds remain in trust.
Check whether a statutory exception may apply.
Preserve relevant records and comply with valid legal process.
Obtain advice before taking action that could breach fiduciary duties.
This checklist is intended to organize the initial review. It does not replace a legal determination about the particular trust or claim.
13. Hypothetical Situations: What Happens When Creditors Come Knocking?
Trust protection can sound wonderfully reassuring until a creditor comes looking for money. The details matter, though, and a creditor’s determination to get paid does not automatically give them the right to raid a trust. Here is how the rules might play out in everyday situations.
Scenario A: Credit card debt and an inheritance still in trust
Daniel owes $35,000 on his credit cards. His mother leaves him an inheritance through an irrevocable trust with a valid spendthrift provision. The trustee has not released the money, and Daniel has no right to demand an immediate payout.
His credit card companies cannot simply call the trustee and request a transfer. Under Florida Statute § 736.0502, ordinary creditors generally cannot attach a beneficiary’s protected interest before distribution. Certain exceptions and successful legal challenges can change that result.
Daniel’s debts have not vanished, of course. His creditors can still pursue other assets available under collection law.
The takeaway: Knowing someone is due an inheritance does not mean a creditor can collect it on demand. An inheritance still held in a protected trust is a very different proposition from money sitting in Daniel’s checking account.
Scenario B: The inheritance has already hit the bank
Maria receives $80,000 from a spendthrift trust and deposits it into her personal account. Unfortunately, she also has an unpaid judgment against her.
Once the trustee distributes the funds, the spendthrift provision generally stops protecting the money from ordinary collection remedies. Maria’s creditor may pursue the account, subject to applicable exemptions.
Maria might wish the trust’s protection came with the money. Unfortunately, legal protections do not always travel as well as cash.
The takeaway: Before distribution, the money may be protected inside the trust. After distribution, Maria may have to deal with creditors under the ordinary collection rules.
Scenario C: The person who created the trust owes money
Robert transfers $400,000 in investments into a revocable living trust. He remains in control and can take the assets back whenever he revokes the trust. Later, he defaults on a personal loan, and the lender obtains a judgment.
Robert argues that the investments belong to the trust. Florida law has an inconvenient answer for that strategy. Under Florida Statute § 736.0505, assets in a revocable trust are generally available to the creator’s creditors during the creator’s lifetime.
In other words, Robert cannot usually put his money in a legal box, keep the key in his pocket, and expect creditors to forget the box exists.
The takeaway: A revocable trust can serve important estate planning purposes. Shielding the creator’s assets from their own creditors generally is not one of them.
Scenario D: A beneficiary falls behind on child support
Elena receives financial support through an irrevocable trust established by her grandparents. She falls behind on court ordered child support, and the other parent seeks to enforce the obligation against her trust interest.
This is not necessarily treated like an unpaid credit card bill. Florida Statute § 736.0503 recognizes exceptions to spendthrift protection for certain claims, including qualifying child support obligations. The available remedy depends on the legal requirements and the trust’s terms.
Elena cannot assume that the spendthrift provision ends the discussion. The other parent cannot assume they are entitled to the entire trust balance, either.
The takeaway: Spendthrift protection can be powerful without being absolute. Certain support obligations receive special treatment under Florida law.
Scenario E: The trust appears just as a lawsuit looms
Michael learns that a former business partner intends to sue him over an unpaid debt. He transfers an investment property into an irrevocable trust for a relative, hoping the creditor will no longer be able to reach it.
The timing is likely to attract attention. Under Florida’s Uniform Voidable Transactions Act, Chapter 726, a creditor may challenge a transfer that meets the statutory requirements for being voidable. A court may consider when the transfer occurred and whether Michael retained control over the property.
Putting the property in an irrevocable trust does not automatically settle the matter in Michael’s favor. If the transfer violates the law, the creditor may seek remedies against it.
The takeaway: An irrevocable trust is not a legal reset button. Transferring property when a creditor is already on the horizon can leave the debtor fighting over the original debt and the transfer itself.
The common thread
A trust can protect an inheritance from certain creditors, but the protection has boundaries. Money still held in a qualifying spendthrift trust may receive different treatment from funds already paid to a beneficiary. A revocable trust generally offers little protection against the creator’s own creditors.
The useful question is what rights the debtor actually has over the assets. That answer usually matters far more than what the trust is called.
14. Frequently Asked Questions About Trusts and Creditors in Florida
Can credit card companies take money from a trust in Florida?
Generally, a credit card company cannot attach a beneficiary’s undistributed interest in a trust with an enforceable spendthrift provision, subject to statutory exceptions. The result may be different if the debtor created a revocable trust or has already received the funds.
Could creditors take money from an irrevocable trust?
Sometimes. An irrevocable trust can protect certain interests, but the result depends on the identity of the debtor, the trust terms, statutory exceptions, and whether the transfer can be challenged.
Can creditors reach a revocable living trust?
Florida Statute § 736.0505 generally permits creditors to reach the assets of a revocable trust during the settlor’s lifetime. The trust’s estate planning benefits do not automatically create creditor protection.
Does a spendthrift clause prevent every creditor from collecting?
No. Florida law recognizes exceptions to spendthrift protection. Certain support claims may qualify, and other legal doctrines may affect the result.
Can a creditor take money after the trustee distributes it?
Potentially. After distribution, the funds may be subject to ordinary collection procedures. Other exemptions may apply depending on the asset and circumstances.
Could a trustee refuse a distribution because the beneficiary owes money?
Not automatically. The trustee must follow the trust instrument and applicable law. A mandatory distribution may be treated differently from a discretionary one.
Can I put my assets in a trust to avoid paying existing debts?
A transfer made to hinder, delay, or defraud creditors may be challenged under Florida’s voidable transfer laws. Anyone considering a transfer while facing a claim should obtain legal advice before acting.
Are trust assets protected during bankruptcy?
Not automatically. Federal bankruptcy law contains rules concerning trust interests and certain transfers. The outcome depends on the trust arrangement and the bankruptcy circumstances.
Does Florida homestead protection apply to money inherited from a trust?
Not automatically. Homestead protection concerns qualifying property under a separate legal framework. Money received from a trust does not become protected merely because the beneficiary intends to use it to buy a home.
Can a creditor force a trustee to make a discretionary distribution?
Generally, a creditor cannot compel a distribution that remains within the trustee’s discretion, subject to statutory exceptions. The terms of the trust and the applicable law determine the trustee’s obligations.
What should I do if a creditor sends a demand involving my inheritance?
Keep the correspondence and obtain the complete trust document. Determine whether the demand concerns an undistributed interest or money already paid to you. If formal court papers arrive, pay attention to the response deadline and obtain legal advice promptly.
Can a creditor challenge a trust created by a deceased parent?
A creditor may examine whether the trust or a transfer into it is subject to a valid legal challenge. The creditor’s rights depend on the trust structure, the relevant statutes, and the facts of the transaction.
15. Trust Creditor Questions in Coral Springs and Broward County
For families in Coral Springs and Broward County, trust creditor disputes can arise during estate administration or after an inheritance becomes available. The applicable Florida statutes remain central regardless of the beneficiary’s city of residence.
A local review may be useful when a trustee receives a creditor demand, when beneficiaries disagree about a proposed distribution, or when a creditor alleges that assets were transferred to frustrate collection.
The location of the trust assets and the parties may affect procedural questions, but geography alone does not determine whether a creditor can reach a beneficiary’s interest.
Final Thoughts
Florida law distinguishes between assets controlled by the person who created a trust and a beneficiary’s interest in a trust established by someone else. A valid spendthrift provision can protect an undistributed beneficiary interest from many ordinary creditors, but statutory exceptions and the terms of the trust matter.
Revocable trusts generally do not protect a living settlor’s assets from that person’s creditors. Distributions can also change the analysis, and transfers intended to obstruct legitimate claims may be challenged.
A Florida real estate attorney knows the rules that govern property transactions, from contract requirements and title issues to closing procedures and the remedies available when something goes wrong. A buyer or seller generally does not have that knowledge. There is no reason to expect them to.
You know the property. What you want to pay or receive. You know the circumstances that brought you to the transaction. Your attorney brings something different: a working knowledge of Florida real estate law and the experience to recognize legal problems that may not be obvious from the face of a document.
The Florida Bar recommends consulting an experienced Florida licensed real estate lawyer before signing a purchase contract. That timing gives the attorney an opportunity to examine the agreement while its terms can still be negotiated.
For someone buying or selling property in Coral Springs, Broward County, or elsewhere in South Florida, that is often the most useful place to begin.
Who Represents Your Interests?
A property transaction can involve real estate agents, brokers, lenders, title professionals, inspectors, surveyors, insurance professionals, and attorneys.
Each person has a different responsibility.
A closing agent may coordinate documents, funds, title requirements, and the mechanics of completing the transaction. That person may also be a lawyer. The Florida Bar cautions consumers that a closing agent does not necessarily represent the buyer’s personal legal interests.
Your own attorney has a different assignment. The lawyer is there to advise you about your legal position, explain what you are agreeing to, identify problems, and negotiate or respond when necessary.
“A closing can look perfectly organized from the outside while still containing terms that deserve a closer legal review. The question is whether someone is specifically looking at the transaction from your legal point of view.”
That can matter when a contract contains unusual obligations, a title commitment raises questions, a condominium has complicated restrictions, or the parties disagree about what was promised.
Start With the Contract
The purchase agreement establishes the framework for the transaction.
Price is one provision. Deadlines, deposits, financing, inspections, repairs, default provisions, closing conditions, property disclosures, and special agreements can all affect what happens after the contract is signed.
The Florida Bar advises buyers to have a lawyer review the purchase contract before signing. Its consumer guidance also notes that contractual terms may become difficult to change once the agreement has been executed.
Florida Realtors has likewise advised consumers to read contracts carefully, including the particular version being used and provisions dealing with default and disputes. Familiarity with a standard form does not answer every question raised by an individual transaction.
A lawyer reviewing the agreement may examine
Contract issue
Questions legal review can address
Deposit
Where is it held? When can it be released?
Inspection
What rights exist if defects are discovered?
Financing
What deadlines and conditions apply?
Closing date
What happens if either side cannot close on time?
Repairs
Which obligations have actually been agreed to?
Default
What remedies may become available?
Special provisions
Do unusual terms create additional obligations?
Disputes
What procedures or remedies does the agreement provide?
A provision can look harmless when read by itself and have a very different effect when considered alongside the rest of the agreement. An attorney is trained to look for those connections.
Title Problems Can Follow the Property
Title work is another central part of a real estate transaction.
A title examination can involve years of recorded documents, previous transfers, liens, easements, restrictions, and other matters affecting ownership. The title insurance commitment identifies requirements that must be satisfied before the policy is issued as well as exceptions to coverage.
Consider a buyer who discovers an easement affecting part of the property. The existence of an easement does not automatically make the transaction unacceptable. Its location, purpose, language, and effect on the buyer’s intended use of the property are the questions that need attention.
The same applies to liens, restrictions, unresolved ownership questions, and other title matters.
A title commitment may identify an exception. The attorney’s job is to explain what that exception means and whether it creates a legal problem for the client.
Florida’s Department of Financial Services recognizes Florida attorneys in good standing as professionals who may handle real estate closings involving title insurance and escrow.
Negotiating the Terms
Real estate negotiations rarely stop at the number written on the first page.
A buyer may want additional time for financing. A seller may agree to repairs in exchange for a particular closing date. The parties may negotiate responsibility for an existing lien or an issue discovered during inspection. A condominium transaction may involve documents and restrictions that require attention before the buyer proceeds.
The lawyer brings legal knowledge to those negotiations.
That knowledge can be useful when a proposed change sounds reasonable but creates an obligation elsewhere in the contract. It can also help a client understand what is worth negotiating and what may create unnecessary complications.
Florida Realtors has emphasized that contract terms can be negotiated and that parties have a right to seek legal review.
A standard contract form is a starting point. The property, the parties, and the circumstances determine whether its provisions actually work for the transaction at hand.
What Happens at Closing?
Closing is where the contractual decisions, title work, financing, and other requirements come together.
The deed must transfer the property properly. Required documents must be completed. The closing figures must correspond with the transaction. Title requirements must be satisfied or addressed. Funds need to reach the correct destination.
A lawyer handling the transaction understands the legal significance of those documents and requirements. The client does not need to become a temporary expert in Florida property law simply because they are buying a house.
There is also a distinctly modern hazard: wire fraud.
That advice deserves serious attention. Real estate transactions can involve hundreds of thousands of dollars moving electronically. A fraudulent change to wiring instructions can turn an ordinary closing into a serious financial problem.
When a Transaction Starts to Fall Apart
Some legal questions do not appear until the deal is already under pressure.
The inspection may reveal significant damage. Financing may fail. A title defect may appear shortly before closing. The seller may refuse to perform an agreed obligation. The buyer may want to withdraw. The parties may disagree about the deposit.
Once that happens, the contract becomes the starting point for determining what each party is required to do and what remedies may exist.
Florida Realtors notes that a failed closing does not cause the underlying contract to disappear. The circumstances surrounding the failure can determine whether a breach occurred and what consequences follow.
This is where knowing the details of the agreement matters. Deadlines, contingencies, default provisions, notice requirements, and other clauses can determine what a party can do next.
An attorney who has reviewed the transaction from the beginning also has the benefit of knowing how the dispute developed, rather than trying to reconstruct the deal after the parties have reached an impasse.
Florida’s Property Market
Florida’s real estate market gives these transactions considerable financial weight.
By August 2026, the statewide median price was $415,000 for single-family homes and $298,000 for condos and townhouses. Inventory stood at 4.3 months for single-family homes and 7.7 months for condos and townhouses.
Florida residential market, August 2026
Median price
Inventory
Single-family homes
$415,000
4.3 months
Condos and townhouses
$298,000
7.7 months
A transaction involving a property worth several hundred thousand dollars can turn on a few sentences in a contract or a title document. Understanding those sentences is part of the attorney’s job.
Do You Need a Real Estate Attorney in Florida?
Florida does not require an attorney for every real estate transaction.
The Florida Bar nevertheless recommends consulting an experienced Florida licensed real estate lawyer before signing a purchase contract.
There is nothing strange about that distinction. People routinely hire professionals for matters that fall within those professionals’ expertise.
You probably would not expect a title examiner to negotiate your purchase agreement or a real estate agent to give you a complete analysis of Florida contract law. An attorney occupies a different place in the transaction.
The lawyer knows the statutes, regulations, contractual principles, title rules, and legal remedies that can affect the deal. The client brings knowledge of the property and their own objectives. Good representation connects the two.
Questions to Ask a Real Estate Attorney
If you are considering legal representation for a Florida property transaction, useful questions include:
Will you review the purchase contract before I sign it?
Will you review the title commitment and exceptions?
Who will represent my interests during closing?
Can you negotiate changes to the contract?
Will you review condominium or homeowners’ association documents when relevant?
What happens if the other party refuses to close?
What should I do if a title problem appears?
How will you communicate with the title company, lender, broker, or opposing counsel?
The answers can tell you how involved the attorney expects to be and whether the representation fits the transaction.
Why Use a Real Estate Attorney?
You do not need to memorize Florida’s real estate laws to buy a house.
You do need to understand the agreement you are signing and the legal consequences of the transaction. That is where an attorney’s knowledge becomes useful.
A real estate lawyer works with the statutes, contracts, title records, closing requirements, and disputes that surround property transactions. The lawyer can recognize legal issues that an ordinary buyer or seller may never have encountered before.
As he states: “A successful closing depends on documents that accurately reflect the agreement and on careful attention to the client’s legal interests throughout the transaction.”
If you are buying or selling property, refinancing, dealing with a title issue, or facing a disagreement over a real estate contract, contact Reinfeld & Cabrera to discuss your situation.
Frequently Asked Questions
Is a real estate attorney required in Florida?
No. Florida does not require an attorney for every real estate transaction. The Florida Bar recommends consulting an experienced Florida licensed real estate lawyer before signing a purchase contract.
When should I hire a real estate attorney?
Before signing the purchase contract is generally the most useful time. Early review allows potential contractual problems to be addressed while the terms remain open to negotiation.
What does a Florida real estate attorney do?
Depending on the transaction, an attorney may review contracts, investigate title issues, explain closing documents, negotiate terms, advise on property restrictions, and represent a client when a transaction develops into a dispute.
Does the closing agent represent the buyer?
Not necessarily. A closing agent can coordinate the transaction without representing the buyer’s individual legal interests.
Can a real estate attorney resolve title problems?
An attorney can investigate the legal significance of title defects, liens, easements, restrictions, and other title issues and advise the client about available options.
What happens when a Florida real estate transaction does not close?
The answer depends on the contract and the circumstances. The parties may have rights and obligations involving deposits, default, damages, deadlines, or other remedies. The contract and the facts need to be examined before determining what follows.
A real estate closing can look deceptively simple. The buyer signs documents, the seller signs documents, money changes hands, and the property changes ownership.
The legal work behind that moment is considerably less simple.
A Florida real estate attorney can review the purchase contract, examine title issues, address liens and other encumbrances, review the closing documents, and advise a buyer or seller when the transaction does not proceed exactly as expected. That work may begin weeks before the closing date.
For someone who already has a real estate agent, lender, title company, or closing agent, it is reasonable to ask what a separate attorney actually does. The answer depends on the transaction, but the attorney’s role is generally to provide legal advice to the client whose interests the attorney represents.
The Florida Bar recommends consulting a Florida licensed real estate lawyer before signing a purchase contract. It also points out that the closing agent may be an attorney without representing the individual buyer’s or seller’s interests.
The Lawyer’s Work Often Starts Before the Closing
The closing is the final stage of a transaction that began with a contract.
That contract determines the purchase price, deposit, financing arrangements, inspection rights, title requirements, closing date, possession, closing costs, and the obligations of both parties. It can also establish what happens when one side fails to perform.
Those provisions matter when the transaction develops a problem.
Suppose the seller discovers that an old mortgage was never properly released. Or the buyer learns that a title objection has not been resolved. Perhaps the parties disagree about whether a repair was required under the contract, or whether a closing deadline can be extended.
Those questions cannot be answered by looking only at the documents being signed on closing day. The purchase agreement, amendments, correspondence, title documents, and applicable Florida law may all matter.
That is one reason the Florida Bar recommends having a lawyer review the purchase contract before it is signed. Standard forms contain many provisions, but the parties can negotiate terms and add provisions that change their rights and obligations.
What Does a Real Estate Attorney Review?
The attorney may review the purchase agreement and the documents generated during the transaction. Depending on the property and the circumstances, that can include:
The purchase and sale agreement
Addenda and amendments
Title commitments and title evidence
Deeds
Mortgages and other recorded instruments
Liens and judgments
Easements and restrictions
Survey issues and possible encroachments
Closing statements
Tax and other prorations
Repair credits and other concessions
Financing documents
Possession provisions
Documents prepared for signing at closing
The attorney is also looking at how these documents fit together.
For example, a closing statement might contain a credit that was negotiated in an amendment to the purchase contract. A title commitment might identify an exception that needs to be addressed before the buyer can receive the title insurance coverage expected under the transaction. A survey might reveal an encroachment that was not apparent when the contract was signed.
The point is not to read every document in isolation. The documents have to be consistent with the transaction the parties actually agreed to.
Why Title Problems Can Delay a Closing
Title is one of the biggest legal issues in a real estate transaction because ownership is not established simply by the seller saying that the property belongs to them.
A title examination can reveal mortgages, tax liens, judgments, easements, restrictions, probate issues, prior conveyances, or other matters affecting the property. The Florida Bar notes that a title examination may involve records going back many years and that problems can originate in areas such as probate, divorce, foreclosure, inheritance, and previous financing.
Some problems are relatively easy to correct. Others require additional documents, negotiations, or legal proceedings.
The purchase contract also matters because it may give the buyer a specific period to examine the title and notify the seller of objections.
Florida courts have enforced those contractual deadlines. In Davis v. Ivey, 984 So. 2d 571 (Fla. 5th DCA 2008), the buyers had 15 days after receiving title evidence to examine the title and notify the seller of defects. The seller provided the title evidence only one day before the scheduled closing. The appellate court held that the contractual examination period still applied.
That kind of dispute illustrates why a closing date does not tell the entire story. The contract may give the parties rights that continue to operate as the closing approaches.
Is the Closing Agent Your Attorney?
Not necessarily.
A title company or settlement agent may handle many of the practical steps required to complete the transaction. That can include preparing or coordinating documents, receiving and disbursing funds, recording documents, satisfying title requirements, and communicating with the parties.
The closing agent’s role does not automatically create an attorney-client relationship with the buyer or seller.
The Florida Bar specifically warns consumers that a closing agent may be a lawyer but may not represent their individual interests.
This distinction becomes important when the parties have competing interests. If the buyer and seller disagree about a contractual provision, for example, the buyer may need independent legal advice rather than assuming that the person conducting the closing is there to advise the buyer.
What Happens When the Closing Statement Changes?
The money being exchanged at closing has to match the transaction.
The settlement statement can include the purchase price, deposit, loan proceeds, taxes, insurance, title charges, recording fees, commissions, credits, prorations, payoff amounts, and other expenses.
Some of these figures are routine. Others may require explanation.
A repair credit negotiated after the original contract was signed should appear consistently in the closing documents. A mortgage payoff should correspond with the amount required to satisfy the seller’s loan. Property taxes may need to be prorated according to the terms of the transaction and the relevant tax period.
A lawyer reviewing the closing documents can compare them with the contract and identify discrepancies that need to be resolved before signing.
Be Careful With Wire Instructions
Wire fraud deserves particular attention during a real estate transaction because large sums of money are commonly transferred shortly before or at closing.
The Florida Bar advises consumers to independently and personally verify wire instructions rather than relying on an email containing payment information.
That advice is worth taking literally. If someone sends new instructions shortly before closing, call the intended recipient using a telephone number you already know to be legitimate. Do not assume that an email is genuine because it contains familiar names, logos, or details from the transaction.
Florida Homestead Law Can Affect the Documents
Florida’s homestead rules create additional legal considerations for qualifying homestead property.
Section 196.031 of the Florida Statutes addresses the homestead exemption for qualifying permanent residences. Florida law also contains specific rules concerning the conveyance and mortgaging of homestead property. Section 689.111 addresses circumstances involving a married owner’s spouse.
These rules can affect the documents required for a transaction and whether a deed or mortgage has been properly executed.
Homestead status can also intersect with estate planning, ownership, and family circumstances. An attorney therefore needs to look at the property and the people involved rather than assuming that every Florida residential closing follows the same set of rules.
What If Something Goes Wrong at Closing?
A closing does not automatically become a lawsuit because a problem appears.
The parties may be able to correct a document, obtain a lien release, resolve a title objection, amend the contract, adjust the closing figures, or agree on another solution. The appropriate response depends on the nature of the problem and the rights established by the contract.
The legal question may become more serious when one party refuses to perform.
If a seller cannot deliver the title required by the agreement, a buyer may have contractual remedies. Maybe a buyer fails to provide required funds or financing, the seller may have rights under the contract. If the parties disagree about whether a condition has been satisfied, the language of the agreement can become central to the dispute.
This is why the purchase contract deserves attention before closing rather than being treated as paperwork that has already served its purpose.
Do You Need a Real Estate Attorney for a Florida Closing?
There is no single answer for every transaction.
A straightforward residential purchase may involve relatively few legal complications. Other transactions can involve title defects, probate issues, divorces, liens, boundary disputes, unusual financing arrangements, commercial property, seller financing, significant contract amendments, or disagreements between the parties.
Those circumstances can change the legal work required.
The Florida Bar recommends having a qualified Florida real estate lawyer review a purchase contract before it is signed, particularly because standard contracts can be modified and because the consequences of contractual language can be significant.
If you are considering hiring an attorney, ask what the attorney will actually review and what representation includes. You should know whether the lawyer will examine the purchase agreement, communicate with the title company, review title issues, examine the closing documents, and advise you about disputes that arise before closing.
Real Estate Closings in Coral Springs and Broward County
A Coral Springs real estate transaction follows Florida law, but the property itself has its own history.
The relevant records can include prior deeds, mortgages, liens, easements, tax information, surveys, condominium or homeowners’ association documents, and other records affecting the property.
That history matters because two properties in the same neighborhood can have completely different title issues.
For buyers and sellers in Coral Springs and Broward County, a real estate attorney can review the particular property and transaction rather than relying on assumptions about how a typical closing should proceed.
Questions to Ask a Real Estate Attorney
Before hiring a Florida real estate attorney, ask specific questions about the work you need:
Will you review my purchase contract before I sign it?
Will you review the title commitment and identify title problems?
Who will communicate with the title company or closing agent?
Will you review the final closing statement?
What happens if a lien or other title defect appears?
What happens if the other party misses a contractual deadline?
Will you review the documents before I sign them?
Who will handle my matter?
How will the legal fees be calculated?
The answers should give you a clear idea of what the attorney will actually do during the transaction.
Talk With a Coral Springs Real Estate Attorney
Reinfeld & Cabrera, P.A. represents clients in Coral Springs and throughout Broward County in real estate matters.
If you are buying or selling property and want legal advice about the contract, title, closing documents, or another issue affecting the transaction, contact the firm to discuss your circumstances with an attorney.
A legal guide to judicial dissolution, member deadlock, and disputes over business ownership
Yes, you can force an LLC to close in Florida without the other members’ consent, but you must prove that a legal ground for judicial dissolution exists. Under Florida Statutes § 605.0702, a court can dissolve an LLC when, for example, the members are trapped in a management deadlock that threatens irreparable injury, controlling members or managers engage in certain illegal or fraudulent conduct, or company assets are misappropriated or wasted in a way that causes the required injury. Depending on the circumstances, the court may also allow the dispute to end through a buyout of the member seeking dissolution rather than closing the company.
How Can a Florida Court Force an LLC to Close?
The answer depends on why the LLC can no longer function properly and what the evidence shows. A disagreement between business partners is not automatically enough. A serious deadlock, financial misconduct, or an operating structure that can no longer function under the company’s governing documents may create a stronger basis for judicial dissolution.
That distinction matters when a business relationship has become impossible to manage. One owner may control the finances while the other cannot get a satisfactory explanation for missing money. Two equal owners may be unable to approve a decision the company urgently needs to make. An operating agreement that seemed perfectly adequate when everyone got along can become a rather expensive reminder that optimism is not a governance strategy.
Florida law gives members a path through these disputes, but there is no legal button marked “shut it all down.” The court looks at the statutory requirements, the evidence supporting the claim, and the remedies available under the circumstances. In some cases, the better outcome may be a buyout rather than dissolution.
This guide explains when you can force an LLC to close in Florida, what qualifies as an LLC member deadlock, how alleged misconduct can affect a dissolution claim, and what can happen when another member wants to keep the business operating.
1. When can a Florida court dissolve an LLC?
Florida’s Revised Limited Liability Company Act establishes the rules for judicial dissolution in Chapter 605. Under § 605.0702(1)(b), a member or manager can ask a circuit court to dissolve an LLC when at least one of the specified statutory grounds is established. A difficult relationship between owners is not, by itself, enough.
The statute identifies five grounds.
The company’s activities are unlawful. A court may dissolve an LLC when all or substantially all of its activities and affairs are unlawful. This concerns the company’s operations, not simply an unpopular decision or a dispute over how the business should be run.
The business cannot reasonably operate under its governing documents. Dissolution may be available when it is no longer reasonably practicable to carry on the company’s activities in conformity with its articles of organization and operating agreement. This ground can become important when the company’s governance arrangements have broken down.
Controlling members or managers have acted illegally or fraudulently. The statute covers qualifying past conduct, ongoing conduct, and conduct reasonably expected in the future. A member may therefore have grounds to seek relief without waiting for further harm if the evidence supports the statutory requirements.
Company assets are being misappropriated or wasted. The statute addresses misuse or waste that injures the LLC. In a proceeding brought by a member, it also covers qualifying injury to one or more members.
Management has reached a harmful deadlock. Managers or members must reach an unbreakable deadlock over company operations, threatening or causing irreparable injury to the business.. All these requirements matter. A stalemate alone is not enough.
These are separate legal grounds, not five ways of describing a business relationship that has deteriorated. A member alleging fraud needs evidence relevant to the alleged conduct. A member relying on deadlock must establish the particular conditions that the statute requires.
That is why the first question should not be whether a business partner has been unreasonable. It should be which statutory ground fits the facts, and what evidence supports it.
2. Can you force an LLC to close if your business partner refuses?
Yes, potentially. The other members do not have an absolute veto over judicial dissolution. If the petitioner establishes a statutory ground, a court may order dissolution despite their opposition. But a member cannot force closure merely by announcing that the partnership is over.
Consider a consulting company owned equally by two members. One wants to take out a large loan to expand the business. The other refuses. If the operating agreement requires both members to approve the loan, the company may be unable to proceed.
That is a disagreement. Whether it becomes a legally actionable deadlock depends on what happens next.
If the loan is optional and the company can continue operating, the dispute may not justify dissolution. If the members cannot approve essential expenses, the business begins missing obligations, and the impasse threatens irreparable injury, the circumstances may be materially different.
Now suppose the operating agreement gives one member authority to make the decision alone. The other member may be furious about the loan, but the company may still have a functioning decision making process. Disliking a decision is not the same as being unable to make one.
The same caution applies to ownership percentages. A member with a 50 percent interest does not automatically have the right to dissolve the LLC. Equal ownership can create a deadlock, but the court must examine the company’s actual governance arrangements and the consequences of the impasse.
The practical question is whether the business can continue operating under its existing structure, not whether its owners still enjoy each other’s company. The law does not require business partners to be friends. Instead, petitioners must establish all legal requirements for their requested remedy..
3. What counts as a management deadlock?
A management deadlock occurs when the people responsible for running an LLC cannot resolve a decision making impasse. For judicial dissolution under § 605.0702(1)(b)(5), the statute requires more than disagreement. The members must be unable to break the deadlock, and irreparable injury to the company must be threatened or already occurring.
Consider two members who cannot agree on whether to hire another employee. If the operating agreement gives one member final authority over staffing, the company may still be able to function. If both members must approve the hire, the disagreement may be harder to resolve. But the court will still need to examine the consequences.
A company that delays a discretionary hire is in a different position from one that cannot approve essential payments because neither member will authorize them. This situation supports a deadlock claim when you satisfy all other statutory requirements.
Why does irreparable injury matter?
The requirement prevents every internal disagreement from becoming a potential dissolution case. The petitioner must connect the deadlock to serious harm that cannot adequately be addressed through ordinary business decisions or other available remedies.
Evidence could show that the company cannot meet essential obligations because the members cannot authorize payments. A business might also be losing a critical contract because the owners cannot approve a decision before a deadline.
A falling company valuation alone does not necessarily establish irreparable injury. The court will want to understand why the injury is occurring and how it relates to the unresolved impasse.
What does the operating agreement change?
The operating agreement may assign decision making authority to a manager or establish a procedure for breaking a deadlock. Those provisions can determine whether a genuine impasse exists in the first place.
In Kertesz v. Spa Floral, LLC, 994 So. 2d 473 (Fla. 3d DCA 2008), the Third District Court of Appeal rejected a dissolution claim based on alleged deadlock where the majority members had authority to replace the plaintiff as managing member. The decision illustrates the distinction between a management decision made by an authorized majority and a genuine inability to resolve a company’s affairs.
The case predates the current Revised LLC Act, which took effect in 2014. Therefore, treat this case as historical guidance rather than a complete interpretation of current statutory language.
The lesson is straightforward. A member who loses a vote has not necessarily established a deadlock. The court must examine the company’s actual governance arrangements and the harm caused by the alleged impasse.
4. Can you force an LLC to close because a member is taking company money?
Potentially. Section 605.0702 addresses the misappropriation or waste of company assets when the required injury exists. It separately addresses illegal or fraudulent conduct by managers or members who control the company. Depending on the facts, both grounds may be relevant.
Imagine a managing member transferring company money into a personal account without an obvious business purpose. The other member asks for an explanation and receives nothing useful in return. The transaction is suspicious, but the legal analysis cannot end there.
The transfer might be an unauthorized withdrawal. It might instead be a documented loan repayment or a legitimate distribution. Bank records show where the money went, but supporting documents reveal whether the transaction was improper.
What evidence matters?
A member alleging misappropriation should preserve relevant financial records and communications. Bank statements may show the disputed transfers. Accounting records may reveal how they were classified. Written requests for an explanation can help establish what information was sought and how the managing member responded.
The evidence should also explain the injury. Did the company lose money it needed to operate? Was an obligation left unpaid? Did the conduct harm a member in a way covered by the statute?
These questions matter because a court needs evidence supporting the statutory ground, not simply proof that the members distrust each other.
Is dissolution the only remedy for suspected misconduct?
No. Florida law allows a court in a dissolution proceeding to consider an injunction, a receiver or custodian, and other appropriate relief.
That flexibility matters when the business itself remains viable. If the immediate problem is the risk of further unauthorized transfers, preserving the company’s assets may be more urgent than shutting it down. If the misconduct has made continued operation untenable, dissolution may be a more relevant remedy.
A member should not assume that alleging fraud guarantees closure. The court will assess the evidence and the legal basis for the relief requested.
5. Can a court dissolve an LLC that has become impossible to operate?
Yes. Section 605.0702(1)(b)(2) allows judicial dissolution when it is no longer reasonably practicable to carry on the company’s activities and affairs in conformity with its articles of organization and operating agreement. This ground is distinct from the more specific test for management deadlock.
Suppose an operating agreement requires the members to cooperate on essential company functions. Their relationship deteriorates so badly that the arrangement no longer works in practice. One member may technically retain authority over certain decisions, yet the business may still be unable to function as the governing documents contemplate.
Whether that situation justifies dissolution depends on the actual agreement and the evidence. Personal hostility alone does not establish that it is no longer reasonably practicable to operate the company.
A petitioner should identify the provisions that have become unworkable and explain why the company cannot reasonably continue under them. The court needs to understand the operational problem, not simply hear that the owners cannot stand each other.
This ground is important because business disputes do not always fit neatly into a deadlock claim. Sometimes the deeper problem is that the company’s governance structure no longer provides a workable way to conduct its affairs.
6. Can the other members buy you out instead of closing the LLC?
Yes. A member who files for judicial dissolution may find that the company or the other members elect to purchase that member’s entire interest instead. Florida Statutes § 605.0706 establishes this procedure. This process results in a court-supervised ownership transfer rather than business dissolution..
This is one of the most important consequences to understand before filing. A member may enter the case seeking to close the company and leave it after a purchase order that allows the business to continue without them.
How does the statutory buyout work?
Under § 605.0706, the company generally has 90 days after the petition is filed to elect to purchase the petitioner’s interest, unless the court permits a later election. If the company does not elect to purchase, one or more other members may elect to do so. The company must notify other members within 10 days of a filed election. Members who wish to participate generally have 30 days after the notice takes effect to file their intention to join.
If the parties agree on fair value and the purchase terms within 60 days after the first election, the court can enter an order reflecting their agreement, subject to the statute. If they cannot agree, the court can determine fair value. The court may also establish payment terms, including installments where appropriate.
These deadlines are consequential. After filing an election, the petitioner generally cannot discontinue the proceeding or sell their interest without court approval. The statute sets conditions for that approval.
How is the member’s interest valued?
However, fair value does not automatically match a member’s original investment. Furthermore, courts do not calculate this figure by multiplying ownership percentage by gross assets.
The court determines fair value under the statutory framework, generally using the day before the petition was filed as the valuation date unless another date is appropriate under the circumstances. The purchase terms may also require attention to the company’s financial position and the rights attached to the interest.
Valuation can become a substantial dispute in its own right. A company may have valuable intellectual property or recurring revenue even if its tangible assets are modest. Another business may have significant debts that affect what the ownership interest is worth.
The important point is that a buyout is not merely an informal offer that the petitioner can ignore while the dissolution case continues unchanged. It is a statutory process with deadlines and consequences.
Before filing, a member should consider what they actually want. If the main objective is to leave the business at a fair price, a negotiated exit may be preferable to a fight over whether the entire company should close. When facing ongoing misconduct, parties must prioritize protecting company assets while resolving the dispute.
7. Can an operating agreement prevent judicial dissolution?
An operating agreement can significantly affect an LLC dispute, but it cannot simply remove the statutory grounds for judicial dissolution. Section 605.0105(3)(i) prohibits an operating agreement from varying the grounds specified in § 605.0702.
The agreement may still provide a way to resolve a deadlock before the court orders dissolution.
Deadlock sale provisions
Section 605.0702(2) addresses an operating agreement that contains a qualifying deadlock sale provision. Such a provision may provide for the purchase of a member’s interest, a change in governance, or the sale of the company or substantially all its assets. If the statutory conditions are met and the mechanism is initiated before the court determines that the deadlock grounds exist, the provision can apply instead of a judicial dissolution order or a statutory purchase order.
Timing is important. Filing a dissolution petition does not automatically eliminate the right to initiate an available deadlock mechanism. Therefore, attorneys must examine the provision carefully to understand how it operates and whether the case meets all requirements.
What if the agreement requires arbitration?
Therefore, an arbitration clause dictates where parties must resolve a dispute. Its scope and wording matter, and it should not be assumed that every dissolution claim is automatically subject to arbitration.
In Pro Play Games, LLC v. Roger, No. 3D23 1458 (Fla. 3d DCA 2024), the Third District held that a dispute concerning a member’s removal fell within the operating agreement’s arbitration provision. The appellate court reversed the denial of a motion to compel arbitration. Instead, the court reached no final decision on dissolving the LLC.
The case illustrates why the operating agreement should be reviewed before a member chooses a litigation strategy. A party who files in court without considering a binding arbitration clause may face a motion that changes the forum for the dispute.
8. How do you file for judicial dissolution in Florida?
Litigants must file judicial dissolution claims directly in circuit court.. The petition should identify the applicable statutory ground and explain the facts supporting it. General accusations that a partner is dishonest or impossible to work with will not substitute for the legal requirements.
Under § 605.0703, venue generally lies in the circuit court of the county where the LLC’s principal office is or was last located, as shown in the Department of State’s records. If the company has no principal office in Florida, the statute provides for venue in the county where its registered office is or was last located.
Before filing, a member should review the articles of organization and the operating agreement, including any amendments. Those documents help establish who has authority to make decisions and whether a contractual dispute resolution process applies.
Counsel must then align the available evidence with each specific claim.. A deadlock case needs proof of the impasse and the threatened or actual irreparable injury. A claim involving misappropriation needs records showing what happened to the assets and why the conduct caused the injury required by the statute.
What if the company needs protection before the case is decided?
A member might worry that insiders will siphoning off company assets or inflict further damage on the business during the lawsuit.. Section 605.0703 authorizes the court to issue injunctions or appoint a receiver or custodian while the case proceeds. The court can also step in to preserve company assets and keep the business operating until the full hearing.
This relief is not automatic. The requested intervention must be supported by the circumstances. A member seeking emergency relief should be prepared to explain the immediate risk and why waiting for a final hearing may be inadequate.
Can the court choose a different remedy?
Yes. Florida law does not limit the court to either dissolving the LLC or dismissing the case. Where the statutory requirements are met, the court may appoint a receiver or custodian, order a purchase of the petitioner’s interest, or grant another appropriate remedy upon a showing of good cause.
This makes it important to identify the real objective before filing. Someone seeking to stop ongoing asset transfers may need immediate protection. A member seeking an exit may be primarily concerned with valuation. A petitioner who believes the business cannot lawfully continue may need dissolution itself.
There is also a litigation risk. Section 605.0703 provides that § 57.105 applies to a dissolution proceeding. That does not mean attorney fees or sanctions automatically follow whenever a petitioner loses. The petitioner must fulfill every statutory requirement.
Judicial dissolution is therefore a serious step, not a harmless way to get a reluctant business partner to negotiate. As the Florida Bar Journal’s discussion of LLC disputes explains, seeking dissolution can put substantial control of the business in the court’s hands.
9. What happens after an LLC is dissolved?
A court order for dissolution does not make the company disappear overnight. The LLC generally enters a winding up process under Chapter 605, during which its remaining affairs must be concluded.
The company may need to collect money owed to it and address its outstanding obligations.The company must manage its remaining assets under statutory rules before distributing anything to members.
This is where an important misconception arises. Dissolution does not erase company debts. Creditors may still have claims, and the winding up process must account for the company’s liabilities. If the business owes more than it owns, members may receive little or nothing from the remaining assets.
Members should also distinguish the court’s dissolution order from the administrative steps required to update the company’s status with the Florida Department of State. The legal process for winding up and the records maintained by the state serve different purposes.
The details depend on the company’s financial position and the applicable provisions of Chapter 605. A business with significant assets and few liabilities presents different practical questions from one facing insolvency.
10. Common mistakes in LLC dissolution disputes
Assuming equal ownership guarantees dissolution. A 50 percent interest may contribute to deadlock, but it does not establish every element required by the statute.
Treating a bad business decision as fraud. A decision that loses money is not automatically fraudulent or unlawful. The claimant must support each allegation with evidence directly tied to the legal ground.
Ignoring the operating agreement. The agreement may allocate decision making authority or establish a process for resolving deadlock. It may also contain an arbitration clause that affects the proper forum.
Assuming dissolution is the only remedy. The court may consider a buyout or other relief where the statutory requirements are met.
Using dissolution as a negotiating threat. A petition can bring the court into the company’s affairs and create statutory buyout rights. That can change the dispute in ways the petitioner did not anticipate.
Failing to preserve evidence. Financial records and written communications may become harder to obtain as the conflict escalates. Relevant records should be preserved lawfully, especially when a member suspects that assets are being misused.
11. Evidence to gather before seeking dissolution
The documents needed will depend on the legal ground, but a member should start by identifying what the evidence must prove.
Issue
Potentially relevant evidence
Governance and authority
Articles of organization, operating agreement, amendments, voting records
Deadlock
Written communications about unresolved decisions, records of votes, evidence of business harm
Misappropriation
Bank statements, accounting records, invoices, records of disputed transfers
Records of missed obligations, lost contracts, or other consequences of the dispute
This is not a complete list of everything a case may require. Some disputes need expert valuation evidence or testimony about company operations. A lawyer can help determine which documents matter and how to obtain them without violating legal obligations.
12. Frequently asked questions
Could one LLC member dissolve a Florida LLC without the others agreeing?
A member can petition for judicial dissolution without the other members’ consent. The court must still find that a statutory ground has been established.
Can a 50 percent owner force an LLC to close?
Not automatically. Equal ownership may create a deadlock, but the petitioner must establish the additional statutory requirements. For a deadlock claim, the members must be unable to break the impasse, and irreparable injury to the company must be threatened or occurring.
Can I force my business partner out instead of closing the LLC?
Possibly. The operating agreement may provide a way to remove or buy out a member, depending on its terms and the circumstances. Florida’s statutory purchase process may also apply when a member seeks judicial dissolution. The available routes have different legal requirements.
What if my partner is taking money from the LLC?
Misappropriation or waste of company assets may support dissolution if the statutory injury requirement is met. Illegal or fraudulent conduct by controlling members or managers may provide another ground. The evidence must establish the applicable legal requirements rather than merely raise suspicion.
Can an operating agreement prevent a judge from dissolving an LLC?
It cannot simply eliminate the statutory grounds for judicial dissolution. It may establish a deadlock resolution mechanism that affects how a particular dispute is resolved. Arbitration provisions may also affect where related claims must be heard.
How long does judicial dissolution take in Florida?
There is no single timeline for every case. The duration depends on the complexity of the dispute and whether the parties contest the evidence or seek interim relief. A statutory buyout election may introduce additional deadlines and valuation proceedings. The 90 day election period is not a guarantee that the entire case will end within 90 days.
Will I receive my ownership share after dissolution?
Not necessarily in the amount you expect. The company must address its obligations during winding up before remaining assets can be distributed as permitted by law. If the company has substantial liabilities, the amount available to members may be reduced or eliminated.
Can I recover attorney fees if I win?
Section 605.0706 permits the court to award certain expenses to a petitioner who had probable grounds for relief in a qualifying purchase proceeding. Section 57.105 also applies to dissolution proceedings. Neither provision makes attorney fees automatic in every successful case.
Can I seek dissolution if the LLC is profitable?
Potentially. Profitability does not rule out every statutory ground. A profitable company may still face qualifying unlawful conduct or misappropriation. A deadlock may also threaten irreparable injury even if the company remains profitable at the time the petition is filed.
What if the court refuses to dissolve the LLC?
The company may continue operating, depending on the court’s ruling and any other relief granted. A member may still have other claims or remedies if the facts support them. The available options depend on the claims raised and the terms of the decision.
13. The real question is what Florida law allows you to accomplish
A member who wants to force an LLC to close in Florida needs more than proof that the business relationship has failed. The member must establish a statutory ground for judicial dissolution and should understand that the court may consider a different remedy.
The operating agreement is often the best place to begin. It can clarify who has authority to make decisions and whether the members agreed on a way to resolve deadlock. Financial records become particularly important when the dispute involves alleged misuse of company assets. The legal strategy should follow the evidence rather than the other way around.
For business owners in Coral Springs and across Broward County, these distinctions can matter before a dispute reaches court. The same principles apply elsewhere in South Florida, subject to the governing law and the facts of each case.
The goal is not necessarily to win the argument over who was the worse business partner. It is to identify a remedy that Florida law permits and that addresses the actual problem.
Two people can have the same business idea and end up with very different legal problems.
Imagine two friends opening a design company in Coral Springs. They agree to split everything 50/50 and decide to form an LLC. The filing takes care of the immediate problem: the company now exists.
It does not answer what happens if one of them puts in more money. Or stops working. Or wants to sell his share. Perhaps he dies. Or decides that the company should be sold while the other wants to keep it.
Those are business formation questions too.
The Florida Department of State recorded 561,143 new domestic LLC filings in 2025, and its most recent quarterly figures show more than 3 million active Florida LLCs. There are more than 4.1 million active business entities of all types in the state.
There is nothing unusual about forming an LLC in Florida.
The filing itself is usually straightforward. Deciding what the company should look like, who should own it, how it should operate, and what happens when circumstances change can require considerably more thought.
What Do You Need to Decide Before Forming a Business in Florida?
Start with the people involved.
If you are forming a business by yourself, many of the ownership questions are relatively simple. If there are two, three, or ten owners, they become part of the legal structure.
Who owns the company?
Who makes decisions?
Where does the money come from?
Who contributes equipment, intellectual property, or work?
Can one owner sell an interest without the others agreeing?
What happens if an owner wants to leave?
What happens if the business loses money?
Those questions do not appear on a basic Sunbiz filing form.
They still need answers.
The choice of entity comes after some of those questions, not before them.
Florida recognizes several forms of business organization, including corporations, limited liability companies, partnerships, limited partnerships, and limited liability partnerships.
For many small businesses, the main discussion will be whether an LLC or corporation makes sense. That is a legal and tax decision, not a matter of choosing whichever form happens to be most popular.
Should You Form an LLC or a Corporation?
There is no universal answer.
An LLC and a corporation have different rules governing ownership, management, transfers, and other aspects of the business. Their federal tax treatment can also differ.
An LLC with one member is generally treated by the IRS as a disregarded entity for federal income tax purposes unless it elects corporate treatment. A domestic LLC with two or more members is generally treated as a partnership unless it elects to be treated as a corporation.
A corporation is a different legal structure, with shares, directors and officers forming part of its statutory framework.
That does not mean a corporation is inherently more sophisticated or an LLC is inherently better for a small business. The appropriate structure depends on what the owners are trying to accomplish.
An attorney and accountant may also need to look at the same proposed business from different angles. The attorney is concerned with the legal structure and documents. The accountant is concerned with tax treatment and financial consequences. Those questions overlap, but they are not the same question.
What about a partnership?
Partnership structures can also be appropriate in some circumstances. Florida has statutes governing general partnerships, limited partnerships, and limited liability partnerships.
The point is not that every entrepreneur needs a tour through every entity available under Florida law.
It is that “LLC or corporation?” is sometimes too early a question.
First figure out what the ownership and business arrangement actually looks like.
“I like to know what the owners expect the business to look like before we start talking about forms. A company with one owner and a company with four owners may both be called an LLC, but the legal questions can be completely different.”
How Do You Choose a Name for a Florida Business?
The name has to work legally as well as commercially.
For a Florida LLC, the name must be distinguishable on the records of the Department of State and must contain an appropriate designation such as “LLC.” A Florida profit corporation has its own naming requirements and must likewise use a distinguishable name. The state recommends searching its records before filing.
There is an important qualification to the old idea that another business simply cannot have “the exact same name.”
The state’s naming rules concern whether a proposed name is distinguishable on its records. That is a narrower question than whether nobody anywhere has rights in the name.
A Sunbiz search is not a trademark search.
That distinction becomes important if the business will spend substantial money on a brand, website, signs, advertising, packaging, or other intellectual property.
What if the business uses another name?
Florida also allows registration of a fictitious name, commonly called a DBA, when a person or business operates under a name different from its legal name. The registration is intended to tell the public who is conducting business under that name. It does not give the registrant ownership of the name or prevent someone else from registering or using it.
So there are several different concepts that people often lump together:
The legal name of the entity.
A fictitious or DBA name.
Trademark rights.
They are not interchangeable.
How Do You Form an LLC in Florida?
A Florida LLC is formed by filing Articles of Organization with the Division of Corporations.
The filing identifies the LLC and its registered agent and provides other information required by Florida law. The registered agent must have a physical street address in Florida.
The current filing instructions also make something important clear: the Division of Corporations is an administrative filing agency. It does not provide legal, accounting, or tax advice, and it recommends that legal counsel review formation documents when appropriate.
That tells you something about the limits of the filing process.
The state can process your Articles of Organization. It does not decide whether the ownership arrangement between you and your business partner is sensible.
How Do You Form a Corporation in Florida?
A Florida profit corporation is formed by filing Articles of Incorporation.
The document includes the corporation’s name, principal office, registered agent and other required information. A corporation must also identify the number of shares it is authorized to issue.
Again, the terminology matters.
LLC: Articles of Organization.
Corporation: Articles of Incorporation.
The two entities also operate under different statutory frameworks after formation.
The Florida Department of State specifically recommends legal review of Articles of Incorporation when the circumstances call for it.
That can be particularly relevant when the corporation will have several shareholders, unusual ownership arrangements, outside investors, or other provisions that go beyond the minimum filing requirements.
Do You Need an EIN for a Florida Business?
The answer depends on the business.
The IRS treats a single member LLC differently from a multi member LLC for federal income tax purposes. A single member LLC that has not elected corporate treatment is generally disregarded for federal income tax purposes. A multi member domestic LLC is generally treated as a partnership unless it elects otherwise.
That does not mean a single member LLC can simply ignore EINs.
The IRS says an LLC will need an EIN if it has employees or certain excise tax obligations. A single member disregarded LLC that does not have those obligations may not need an EIN for federal income tax purposes, although it may still obtain one for purposes such as opening a bank account or satisfying another requirement.
The old rule that a corporation “definitely” needs an EIN while an LLC simply gets to choose is therefore too crude.
The entity, its tax classification, its employees, and its activities all matter.
What Licenses and Tax Registrations Does a Florida Business Need?
There is no single Florida business license that covers every company.
The requirements depend on what the business actually does.
A business selling taxable goods or services may have to register with the Florida Department of Revenue before beginning those activities. The Department provides an online registration system that determines applicable tax registrations based on information about the business.
Other businesses may have professional licensing requirements, industry specific permits, local requirements, or regulations tied to their location.
A restaurant and a software consultant can both be Florida LLCs. Their regulatory obligations can be very different.
That is why “get your business license” is not much of a checklist.
The useful questions are:
What does the business sell?
Where does it operate?
Does the industry require a professional or occupational license?
Can the business collect a tax that requires registration?
Does the local government impose additional requirements?
Those questions produce a much more accurate answer.
What Documents Should Business Owners Have?
The state filing establishes the entity. It does not necessarily establish the relationship between its owners.
This becomes especially important with a multi member LLC.
Florida law expressly recognizes operating agreements and allows people who intend to become LLC members to make an agreement that will become the company’s operating agreement when the LLC is formed. The operating agreement governs important aspects of the company’s internal relationship.
An operating agreement can address issues such as:
Ownership percentages
Management
Voting
Contributions
Distributions
Transfers of ownership
Admission of new members
Withdrawal of a member
Events affecting the business when a member dies or becomes unable to participate
Procedures for resolving disagreements
Not every LLC needs the same document.
A one person consulting business does not present the same problems as a four person company whose owners are contributing different amounts of money and labor.
A Florida LLC Dispute Shows Why the Agreement Matters
In Dinuro Investments, LLC v. Camacho, a dispute among members of an LLC reached the Third District Court of Appeal. The case concerned when an individual LLC member could bring claims against other members in an individual capacity rather than bringing a derivative action on behalf of the company. The court adopted a framework distinguishing direct injuries from injuries belonging to the LLC itself and also recognized the importance of contractual or statutory duties owed directly to a member.
The case involved a real estate development company, not a hypothetical neighborhood startup.
That is useful precisely because disputes between owners do not stay theoretical for long once money and contractual rights are involved.
The operating agreement can become one of the documents the lawyers have to examine when trying to determine what the members agreed to and what rights they have.
Proposed quote — Stuart Reinfeld: “Two people can be completely comfortable with a 50/50 arrangement when the business is making its first dollar. The harder conversation is what happens when they disagree about the hundred thousandth dollar.”
What Happens After the Business Is Formed?
This is where the old six step checklist stopped too early.
Once the entity exists, the owners still have to run it.
Depending on the business, that can include:
Obtaining an EIN
Opening business banking and accounting systems
Establishing ownership and management records
Adopting an operating agreement or corporate governance documents
Obtaining licenses and permits
Registering for applicable Florida taxes
Preparing contracts
Hiring employees and addressing employment requirements
Maintaining the registered agent
Filing annual reports
Florida LLCs must file annual reports to maintain active status. The filing period runs from January 1 through May 1 of the applicable year, and failure to file can result in administrative dissolution. Corporations have the same basic annual reporting requirement.
The annual report is not a financial statement. It updates the state’s records about the entity.
That is a small administrative obligation with a very concrete consequence if it is ignored.
The company can disappear from the state’s active records even though the owners are still thinking about it as an operating business.
Why Should Business and Personal Finances Be Kept Separate?
Someone forming an LLC or corporation is creating a separate legal entity. The way the business is actually operated should reflect that.
That includes maintaining appropriate financial records and avoiding the casual mixing of company and personal money.
Florida courts have recognized the separate nature of business entities while also addressing circumstances in which members or shareholders seek to impose liability on individuals behind the entity.
In Dinuro, for example, the Third District discussed the limited liability associated with an LLC and the distinction between claims belonging to the company and claims belonging directly to an individual member.
There is no magic bank account that makes an owner immune from personal liability.
There is also no good reason to make the company’s records harder to understand than they need to be.
If the business buys equipment, the records should show who bought it.
Perhaps an owner puts money into the company, the transaction should be documented appropriately.
If the company signs a contract, the correct legal entity should be identified.
These are ordinary business practices. They also become very important when an owner later has to explain what happened to the company’s money or property.
What Can Go Wrong When Business Partners Do Not Plan Ahead?
Consider a common situation.
Two friends form an LLC. One contributes $100,000. The other contributes less money but works full time in the business. They decide to own the company equally because, at the time, that feels fair.
Three years later, the business is profitable.
The working owner believes his contribution should give him greater control. The other owner believes the original 50/50 agreement is still the agreement.
Neither is necessarily behaving irrationally.
They simply reached the point where the assumptions they made at the beginning no longer answer the questions they now have.
That is the sort of problem an operating agreement can address before the dispute exists.
Florida’s appellate courts have dealt with similar questions in actual LLC disputes. In Demir v. Schollmeier, the Third District considered an agreement between LLC members and concluded that the agreement governed their relationship even though it was not titled an “operating agreement” and was not executed at the time the LLC was originally formed.
The case involved a particular dispute and particular contractual language. It does not mean that every informal agreement between business partners will produce the same result.
It does illustrate why the arrangements between owners deserve attention when the company is being created.
When Should You Talk to a Business Attorney?
You can form a Florida business through the state’s online filing system without hiring a lawyer to click the buttons for you.
The harder question is whether the business has legal decisions that deserve advice before those buttons are clicked.
That is particularly true when:
There are multiple owners
Owners are contributing different amounts of money or labor
The business will have investors
Ownership may change
The business involves intellectual property
The company will own significant property
The owners are family members
The business is buying another company
The company will enter substantial contracts
A professional license is involved
The owners want restrictions on transfers
The business may eventually be sold
The owners have different ideas about management or control
In those circumstances, the formation documents are only part of the legal work.
The attorney may need to look at the proposed ownership structure, operating agreement, contracts, licensing requirements, intellectual property, real estate, or other issues before the business begins operating.
“The state filing tells you that the entity exists. It does not tell you whether the arrangement between the people who own it will work. That is usually where the more interesting legal questions begin.”
Frequently Asked Questions
How do I form a business in Florida?
You generally begin by choosing an appropriate legal structure, selecting a name, designating a registered agent, and filing the required formation documents with the Florida Department of State. The business may also need tax registrations, licenses, permits, and internal ownership or governance documents.
Is an LLC or corporation better for a Florida business?
Neither is automatically better. The appropriate structure depends on ownership, management, taxation, financing, liability considerations, and the way the owners expect the business to operate.
What is the difference between Articles of Organization and Articles of Incorporation?
Articles of Organization are used to form a Florida LLC. Articles of Incorporation are used to form a Florida profit corporation.
Do I need an EIN for a Florida LLC?
It depends on the LLC’s circumstances and federal tax classification. A single member LLC that is disregarded for federal income tax purposes may not need an EIN solely for federal income tax reporting if it has no employees and no applicable excise tax obligations, although an EIN may still be needed or useful for other purposes.
Do I need a business license in Florida?
There is no single license required for every Florida business. Requirements depend on the business activity, industry, location, and applicable state or local rules.
What happens after I form an LLC in Florida?
The owners may need to obtain an EIN, establish business banking and accounting procedures, prepare an operating agreement, obtain licenses and permits, register for applicable taxes, and maintain the entity’s state records and annual filings.
Does a Florida LLC need an operating agreement?
Florida law recognizes operating agreements as governing documents for LLCs. Whether a particular business needs a detailed agreement depends on its circumstances, but an operating agreement can establish important rules concerning ownership, management, transfers, and the relationship among members.
Can I use a different name from my company’s legal name?
Yes. A Florida business can generally register a fictitious name, commonly called a DBA, when it operates under a name different from its legal name. The registration does not give the business exclusive ownership of that name.
Starting a Business in Coral Springs or Broward County
Someone opening a business in Coral Springs deals with the same Florida entity laws as someone forming a company elsewhere in the state.
The local details can still matter.
A business may have a physical location, employees, professional licensing requirements, local regulatory issues, or tax and registration obligations connected to where it operates. A company working from a home office can have a different set of practical issues from a restaurant, medical practice, construction company, or retail store.
For business owners in Coral Springs and throughout Broward County, the formation decision should therefore account for the business that actually exists rather than an imaginary generic “Florida business.”
That is also why two businesses that both file as LLCs can need very different legal documents.
Talk With a Florida Business Attorney
If you are forming a business in Coral Springs, Broward County, or elsewhere in Florida, Reinfeld & Cabrera, P.A. can review the proposed structure, ownership arrangement, formation documents, and other legal issues involved in setting up the company.
A consultation can also be useful when the basic filing is straightforward but the relationship between the owners, the company’s contracts, its property, or its future plans raises questions that a state filing form cannot answer.
This article provides general information about Florida business formation and is not a substitute for legal, tax, or accounting advice concerning a particular business.