When a Financial Power of Attorney Goes Wrong: What Can Families Do?

Family discussing a financial power of attorney with an attorney in Coral Springs, Florida

If you believe someone has misused a financial power of attorney in Florida, there are legal ways to challenge what happened. Depending on the circumstances, a court may review the agent’s conduct, require an accounting, remove the agent, terminate the agent’s authority, or order other relief.

Usually, though, nobody starts with a lawsuit.

It starts with a bank statement.

A parent gave a son or daughter power of attorney to handle the bills. An elderly relative needed someone to manage investments. Everything seemed ordinary until a family member noticed a withdrawal that did not make sense.

Then there is another one.

Maybe money went to the agent. Perhaps a house was sold. Maybe someone suddenly has a very good explanation for why several thousand dollars disappeared.

The uncomfortable part is that having power of attorney does give someone real authority. The document may allow an agent to handle bank accounts, investments, real estate, and other financial matters. But that authority comes with legal duties, and the agent has to stay within the authority the principal actually granted.

So what happens when the numbers stop making sense?

The answer usually starts with the power of attorney itself, the agent’s actions, and the financial records showing what happened to the principal’s money.


What Is a Financial Power of Attorney?

A power of attorney allows one person, called the principal, to authorize another person, called the agent, to act on the principal’s behalf.

The authority can be broad or limited. Depending on the document, an agent may be able to handle bank accounts, investments, contracts, real estate, or other financial matters.

Florida law generally limits an agent to the authority actually granted in the power of attorney. A broad statement saying that the agent can perform every act the principal could perform does not automatically create every possible specific power under the statute. Certain powers require separate, signed authorization.

That detail can become extremely important when a family disputes a transaction.

The document itself has to be examined.


What Does Financial Power of Attorney Abuse Look Like?

There is no single transaction that automatically proves abuse.

An agent might legitimately withdraw money to pay the principal’s mortgage. The same type of withdrawal could become a serious problem if the money goes toward the agent’s own mortgage.

Warning signs can include:

  • Unexplained withdrawals from bank or investment accounts
  • Transfers to the agent or the agent’s relatives
  • Personal expenses paid from the principal’s accounts
  • Property transferred or sold for the agent’s benefit
  • Large gifts that do not fit the principal’s history or instructions
  • Financial accounts being changed without a clear explanation
  • Missing receipts or financial records
  • Transactions occurring after the power of attorney was revoked

The records matter.

Florida requires an agent to keep records of transactions made on behalf of the principal, and the Florida Bar notes that an agent may be required to provide an accounting.


As Alan Reinfeld puts it:

“A power of attorney gives someone authority to act for another person. It does not give that person ownership of the principal’s money.”


Can a Power of Attorney Agent Take Money From the Principal?

An agent can use the principal’s money when the transaction is authorized and consistent with the agent’s legal duties.

The agent cannot simply treat the principal’s checking account as a second personal account.

Florida law describes the agent as a fiduciary. The agent generally must act loyally for the sole benefit of the principal, avoid conflicts that interfere with impartial decision-making, and exercise the care, competence, and diligence ordinarily expected in similar circumstances.

Consider a simple example.

A daughter has power of attorney for her father. She uses his account to pay his property taxes, medical bills, insurance, and other expenses. Those transactions may be entirely appropriate.

Then she transfers $50,000 to herself and says, “Dad wanted me to have it.”

That raises a very different set of questions.

  • Was the gift authorized?
  • Did the power of attorney contain the necessary authority?
  • Was the transaction consistent with the father’s known wishes?
  • Did the agent have a conflict of interest?
  • What records exist?

A court looking at a disputed transaction may need to answer those questions rather than simply deciding whether money changed hands.


Can a Power of Attorney Agent Use the Principal’s Property?

Real estate can create especially complicated disputes.

Florida law allows a power of attorney to grant authority to convey or mortgage homestead property, but the applicable formalities and statutory requirements matter. The Florida Bar likewise explains that an agent may sell a principal’s home when the power of attorney satisfies the applicable requirements and grants the necessary authority.

Suppose an agent sells a property and deposits the proceeds into an account belonging to the principal. That may be an ordinary transaction.

Suppose the proceeds instead end up financing the agent’s own house.

Now the transaction deserves serious scrutiny.

The same problem can arise when an agent uses the principal’s money to purchase property that is titled in the agent’s name.


A Broward County case shows how messy this can become

In Sacco-Martin v. Romano, decided by Florida’s Fourth District Court of Appeal in August 2025, elderly parents had granted powers of attorney to their daughter and her husband in 2019 and 2020. They revoked those powers of attorney in May 2021. A subsequent guardian alleged that the former agents had nevertheless exercised control over the parents’ financial accounts and transferred hundreds of thousands of dollars.

The probate court ordered an accounting covering the period during which the agents had acted under the powers of attorney. It reviewed bank statements and testimony and ultimately ordered the former agents to return substantial funds to the guardianship estate.

The Fourth DCA affirmed most of that ruling. It did, however, reverse one $20,000 portion because the particular transfer occurred before the relevant power of attorney period and therefore fell outside the accounting period established by the probate court.

The case also involved two properties purchased with the parents’ money. One was purchased with more than $562,000 transferred from the parents’ account and titled in the parents’ names. The property was later sold. Another property was purchased around the same time, with questions about whether the parents’ money ultimately funded the purchase and why that property was titled in the former agents’ names.

That is a useful lesson in how these disputes actually develop.

The question may begin with, “Where did the money go?”

It can eventually become a dispute involving bank records, property titles, closing statements, accounting periods, alleged gifts, and the scope of the agent’s authority.


Can a Court Remove a Power of Attorney Agent in Florida?

Yes.

Florida Statutes §709.2116 allows a court to construe or enforce a power of attorney, review an agent’s conduct, terminate the agent’s authority, remove the agent, and grant other appropriate relief.

The statute also identifies people who may petition the court. They include the principal or agent, certain fiduciaries, a person authorized to make health care decisions in specified circumstances, and another interested person who can demonstrate an interest in the principal’s welfare and a good-faith belief that court intervention is necessary.

That can matter when the principal is no longer capable of handling the dispute personally.

It also means that a family disagreement does not automatically give every relative the right to take over the situation. Standing, the principal’s circumstances, the agent’s conduct, and the available evidence all matter.


Can You Force a Power of Attorney Agent to Provide an Accounting?

Potentially, yes.

Financial records are often central to a dispute over an agent’s conduct. Florida law requires an agent to maintain records of receipts, disbursements, and transactions made for the principal. The Florida Bar likewise advises agents to maintain careful records and explains that an agent may be required to provide an accounting.

An accounting can help answer basic but important questions:

  • What money came into the account?
  • What money went out?
  • Who received it?
  • What was the payment for?
  • Was the transaction authorized?
  • Was the principal’s money used for the principal’s benefit?

Sometimes the accounting clears things up.

Sometimes it creates several new questions.


What Evidence Can Help Prove Power of Attorney Abuse?

If you suspect that a financial power of attorney has been misused, preserve the records before they disappear into the digital equivalent of a junk drawer.

Useful evidence can include:

  • The original power of attorney and any amendments
  • Bank and investment statements
  • Canceled checks
  • Wire transfer records
  • Deeds
  • Closing statements
  • Tax records
  • Credit card statements
  • Receipts
  • Emails and text messages
  • Communications with banks or financial institutions
  • Records showing the principal’s usual financial practices
  • Documents concerning the principal’s estate plan

The power of attorney itself is especially important.

A transaction can look suspicious until the document reveals that the agent had express authority to perform it. The opposite can also happen: a transaction can look ordinary until the document shows that the agent lacked the authority to make it.


What If the Principal Is Still Capable?

If the principal still has the legal capacity to make financial decisions, the situation may be different from one involving a principal who can no longer manage their affairs.

Florida law provides for revocation of a power of attorney, and a principal who remains capable may be able to revoke the existing authority and appoint another agent. The details depend on the circumstances and the document.

When there are already disputed transactions, however, changing the agent may be only one part of the problem.

There may also be questions about money already transferred, property already sold, or records that have not been provided.
Reviewing financial records for suspected power of attorney misuse in Broward County

What Happens to a Financial Power of Attorney After Death?

A power of attorney generally terminates when the principal dies. Florida’s statute expressly provides that the principal’s death terminates the power of attorney.

That does not erase transactions that happened while the principal was alive.

If family members believe an agent misused the principal’s property before death, those transactions can become relevant to an estate or probate dispute.

The legal framework then shifts. The personal representative or another person with appropriate authority may need to investigate what happened to the deceased person’s assets.

This is one reason a power of attorney dispute can eventually become a probate matter.


How Common Is Financial Exploitation?

Power of attorney abuse sits within a much larger financial exploitation problem.

The Administration for Community Living reported that older Americans lost nearly $2.4 billion to fraud in 2024, up from $1.9 billion in 2023. The agency also cautioned that reported fraud represents only part of the actual harm because many incidents go unreported.

The numbers cover fraud generally, not power of attorney abuse specifically.

But the broader pattern is relevant. Financial exploitation can occur within relationships of trust, including relationships involving family members, caregivers, and other people who have access to an older person’s finances.

A South Florida federal case illustrates how severe one of these situations can become.

In 2025, federal prosecutors sentenced former financier Brett Thomas Graham to seven years in prison after he admitted defrauding an elderly family member of approximately $8.4 million. According to the U.S. Attorney’s Office, Graham later became the woman’s power of attorney and was obligated to act in her best interest while continuing to divert money for his own expenses.

That is an extreme case.

Most power of attorney disputes will not involve $8.4 million, federal wire fraud charges, or a seven-year prison sentence.

The underlying problem can be much smaller and still be devastating to a family.


What Can Families Do About Power of Attorney Abuse?

Start with the document and the records.

Find out what authority the principal actually granted. Identify the transactions that are causing concern. Gather the financial records. Establish when the transactions occurred. Determine whether the power of attorney was still effective.

Then ask the uncomfortable questions.

  • Was the transaction authorized?
  • Was it for the principal’s benefit?
  • Did the agent personally benefit?
  • Was there a gift?
  • Was there a conflict of interest?
  • Can the agent account for the money?

Those questions are far more useful than simply asking whether someone in the family “did something shady.”

And sometimes the records show that the agent acted properly.

That possibility deserves to be taken seriously too.


As Stuart Reinfeld explains:

“Financial disputes between relatives can become emotional very quickly. The documents give everyone something concrete to examine.”
Attorney reviewing a property transfer involving a financial power of attorney in Broward County

Power of Attorney Disputes in Coral Springs and Broward County

For families in Coral Springs and throughout Broward County, a financial power of attorney dispute may overlap with probate, guardianship, estate litigation, real estate, or financial exploitation proceedings.

Broward County’s Probate and Guardianship Division handles probate and guardianship matters through the Seventeenth Judicial Circuit. The county also provides procedures and resources for matters involving vulnerable adult exploitation, guardianship accountings, probate filings, and related proceedings.

That local connection matters when a dispute moves from a family disagreement into a court proceeding.

A court may be asked to review the agent’s conduct, terminate the agent’s authority, remove the agent, order an accounting, or provide another appropriate remedy under Florida law.


Frequently Asked Questions

What is a financial power of attorney in Florida?

  • A financial power of attorney allows a principal to authorize an agent to handle specified financial or property matters. The agent’s authority depends on the language of the document and Florida law.

Can a power of attorney agent take money from the principal?

  • An agent may use the principal’s money when authorized and when acting consistently with the agent’s fiduciary duties. An agent cannot simply treat the principal’s assets as personal property.

How do you prove power of attorney abuse?

  • Evidence can include the power of attorney itself, bank records, transfers, property records, closing documents, receipts, communications, and other evidence showing what authority the agent had and what the agent actually did.

Could a power of attorney agent be removed in Florida?

  • Yes. Florida law allows a court to review an agent’s conduct, terminate the agent’s authority, remove the agent, and grant other appropriate relief.

Can a family member challenge a power of attorney agent?

  • Potentially. Florida law permits certain interested persons to petition the court when they meet the statutory requirements for intervention. A family relationship by itself does not determine whether someone has standing.

Can a power of attorney agent be required to provide an accounting?

  • An agent has a statutory duty to keep records of receipts, disbursements, and transactions made for the principal, and an accounting may be required in appropriate circumstances.

What happens to a power of attorney after the principal dies?

  • The power of attorney terminates when the principal dies. Transactions carried out before death can still become relevant to a later probate or estate dispute.

When a Financial Power of Attorney Goes Wrong

A financial power of attorney is built on a simple arrangement: one person gives another person authority to handle matters the principal cannot or does not want to handle personally.

Most of the time, that arrangement exists because someone needs help.

When the relationship breaks down, the family may be left reconstructing months or years of financial decisions while trying to determine who has the legal authority to do something about them.

That is why the document, the financial records, the agent’s conduct, and the principal’s circumstances all need to be examined together.

If you believe a financial power of attorney has been misused in Coral Springs, Broward County, or elsewhere in South Florida, Reinfeld & Cabrera P.A. can review the circumstances and discuss the legal options available under Florida law.


This article provides general information about Florida law and is not a substitute for legal advice concerning a particular situation.
How to Stop Foreclosure in Florida: Modern Loan Modifications and Legal Rights

Infographic illustrating the Florida judicial foreclosure timeline and loss mitigation milestones under federal servicing rules.

When you walk into your kitchen, grab a cup of coffee, and find a foreclosure notice sitting right next to the toaster, the panic hits you square in the chest.

How on earth did things get this far, and is there any actual, realistic way to save your home before the bank schedules a fire sale on the courthouse steps?


Quick Answer: Under Florida law, a judicial foreclosure typically takes 6 to 14 months to complete, providing homeowners with a vital legal window to pursue loss mitigation options like a Fannie Mae Flex Modification or file a formal defense. Under federal RESPA rules (12 C.F.R. § 1024.41), mortgage servicers are strictly prohibited from dual tracking a foreclosure while a complete loan modification application is under review.


If you wander onto the internet looking for mortgage relief, you will trip over old blog posts, expired federal initiatives from decades past, or blanket quick fixes that vanished years ago. Relying on outdated internet advice or waiting around for a government bailout program that no longer exists is a marvelous way to lose your property while wondering what went wrong.

So what options do Florida homeowners actually have right now when facing default, past due mortgage payments, or a looming court summons in the 17th Judicial Circuit? Let us break down how modern loan modifications, loss mitigation, and active foreclosure defenses work in today’s real estate market without any corporate mumbo jumbo.


Why Modern Loss Mitigation Replaced One Size Fits All Federal Programs

When banks initiate foreclosure proceedings in Florida, they move through a strict, formal judicial process. Older programs like HAMP dictated a rigid federal template, but today mortgage servicing relies on standardized corporate guidelines and portfolio specific workouts.

Modern foreclosure defense requires looking at your current financial snapshot and choosing an active legal path:

  • Standardized Lender Modifications: Major loan servicers and government backed entities like Fannie Mae and Freddie Mac utilize structured programs—such as the Flex Modification—to lower monthly payments by extending loan terms up to 40 years, capitalizing missed arrears, or adjusting interest rates.
  • Chapter 13 Bankruptcy Protection: For homeowners with steady income facing an imminent foreclosure auction, filing a Chapter 13 plan can halt the bank instantly, giving you a court approved safety net to catch up on mortgage arrears over three to five years.
  • Strategic Loss Mitigation & Short Sales: If staying in the home is no longer financially viable, a managed exit strategy protects your overall credit profile and helps avoid a predatory deficiency judgment.

How Modern Loan Modifications Work With Your Lender

Securing a permanent loan modification requires navigating a structured underwriting review with your loan servicer.

Ask yourself: Does my current monthly income realistically support a restructured payment if the bank agrees to stretch out the loan term or lower the interest rate?

To qualify for a modern in-house or agency backed loan modification, your servicer will typically look for three key criteria:

  1. Proof of Stable Income: Verifying that you have sufficient monthly earnings through pay stubs, profit and loss statements, or tax documents to support a modified payment structure.
  2. Primary Residence Verification: Demonstrating that the property is your primary home rather than an unmanaged investment portfolio asset.
  3. Financial Hardship Documentation: Providing a signed hardship affidavit explaining the life event—such as a medical emergency, job change, or temporary income reduction—that caused you to fall behind.

Avoiding Dual Tracking and Protecting Your Rights Under Federal Servicing Rules

When dealing with mortgage default or foreclosure in Florida, many homeowners worry that submitting a loan modification application will cause the bank to quietly move forward with a foreclosure judgment behind their backs.

What safeguards actually prevent lenders from rushing an auction while your loss mitigation paperwork is sitting on an underwriter desk?

Under federal regulations governed by the Consumer Financial Protection Bureau (12 C.F.R. § 1024.41), mortgage servicers are strictly prohibited from engaging in dual tracking. Dual tracking occurs when a lender simultaneously processes a foreclosure lawsuit while a complete loss mitigation or modification application is actively under review.

Critical Protection Milestones for Florida Borrowers

  • The 120 Day Rule: Under federal rules, a mortgage servicer generally cannot officially file a judicial foreclosure complaint in court until a borrower is more than 120 days delinquent on payments. This window gives homeowners ample time to submit an initial loss mitigation package.
  • The Evaluation Freeze: If you submit a complete modification application before the bank makes its first official foreclosure filing or moves for a judgment, the servicer cannot move for foreclosure judgment or conduct a judicial sale until they have formally evaluated your application and provided you with written notice of their decision.
  • The Right to Appeal: If a servicer denies a modification, federal guidelines often provide a 14 day window to appeal the decision if the application was submitted at least 90 days before a scheduled sale date.

If a lender or bank servicer violates these federal protections or mishandles your paperwork while operating in local courts like the 17th Judicial Circuit in Broward County, an experienced foreclosure defense attorney can leverage these violations to halt the lawsuit, challenge the bank’s standing under Fla. Stat. § 702.015, and force the lender back to the negotiating table.


Real-World Case Example: Stopping Dual Tracking in Broward County

Consider a case our firm handled where a Broward County homeowner inherited a residential property after a family member passed away. The mortgage servicer quickly initiated a foreclosure action in the 17th Judicial Circuit. To make matters worse, the bank mishandled the estate transfer documents and loss mitigation paperwork, attempting to rush a foreclosure judgment while the surviving family member was trying to secure a loan modification.

How Our Legal Team Resolved the Case

  • Challenging Standing: We filed formal defenses requiring the bank to prove proper legal standing under Florida law.
  • Stopping Dual Tracking: We enforced federal rules under 12 C.F.R. § 1024.41 to halt the foreclosure sale while the modification paperwork was under review.
  • Securing the Result: The active defense forced the lender to stop the rushed timeline and approve a permanent solution that allowed the family to keep their home.
Florida foreclosure defense attorney reviewing mortgage documents and loan modification options in a South Florida law office.

Frequently Asked Questions About Florida Foreclosures

Can I fight a foreclosure lawsuit while simultaneously applying for a loan modification?

  • Yes. Under Florida law and federal mortgage servicing rules, working with your lender on loss mitigation options does not mean you should ignore a pending lawsuit. Having a defense attorney file a formal answer in court protects you from a default judgment while your modification application is actively being reviewed.

What happens if the bank wrongfully denies my loan modification request?

  • If a servicer improperly denies your modification or violates federal RESPA (Real Estate Settlement Procedures Act) guidelines by dual tracking your file while a complete modification application is pending, a real estate litigation attorney can hold them accountable in court.

How long does the judicial foreclosure process take in Florida?

  • Because Florida is a strict judicial foreclosure state, lenders cannot seize property without filing a formal lawsuit in circuit court. On average, an uncontested or contested foreclosure timeline spans anywhere from 6 to 14 months, providing a critical window to evaluate defense options, pursue loss mitigation, or negotiate with the bank.

What is a Fannie Mae or Freddie Mac Flex Modification?

  • The Flex Modification is a standardized loss mitigation program used for government backed conventional loans. It is designed to achieve a target reduction in monthly principal and interest payments by capitalizing delinquent amounts, lowering interest rates, or extending the loan maturity term up to 480 months.

Does filing for bankruptcy stop a scheduled foreclosure sale in Broward County?

  • Yes. The moment a Chapter 13 or Chapter 7 bankruptcy petition is filed, an automatic stay goes into effect under federal law. This injunction immediately halts all collection efforts, creditor calls, and scheduled foreclosure sales governed by the 17th Judicial Circuit in Broward County, giving you breathing room to reorganize your debts.

Can a lender proceed with foreclosure if I never received a default notice?

  • Lenders must comply with strict contractual notice conditions precedent outlined in standard mortgage agreements, typically requiring a formal notice of default and intent to accelerate thirty days prior to filing a lawsuit. If the bank failed to provide proper statutory or contractual notice, a defense attorney can leverage this error to dismiss or delay the foreclosure action.

The Broward County courthouse in Fort Lauderdale where 17th Judicial Circuit foreclosure litigation is handled.

Protect Your Home and Your Financial Future

Facing foreclosure alone is a risk you should not take. Whether your goal is to restructure your loan, fight the bank standing in court, or execute a graceful exit strategy to preserve your credit, you need a localized game plan.

The foreclosure defense attorneys at Reinfeld & Cabrera P.A. help homeowners across South Florida navigate complex lender disputes, evaluate modification alternatives, and protect their rights.


Schedule a Confidential Foreclosure Consultation

Do not wait until a sale date is scheduled. Speak directly with an attorney today to review your options:

  • Direct Telephone: (954) 866 4878 | Toll Free: (954) 866 HURT
  • Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Website: mypersonalattorneys.com
  • Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all surrounding communities across Broward, Miami Dade, and Palm Beach Counties.

The Hidden Dangers of Joint Ownership with Right of Survivorship in Florida

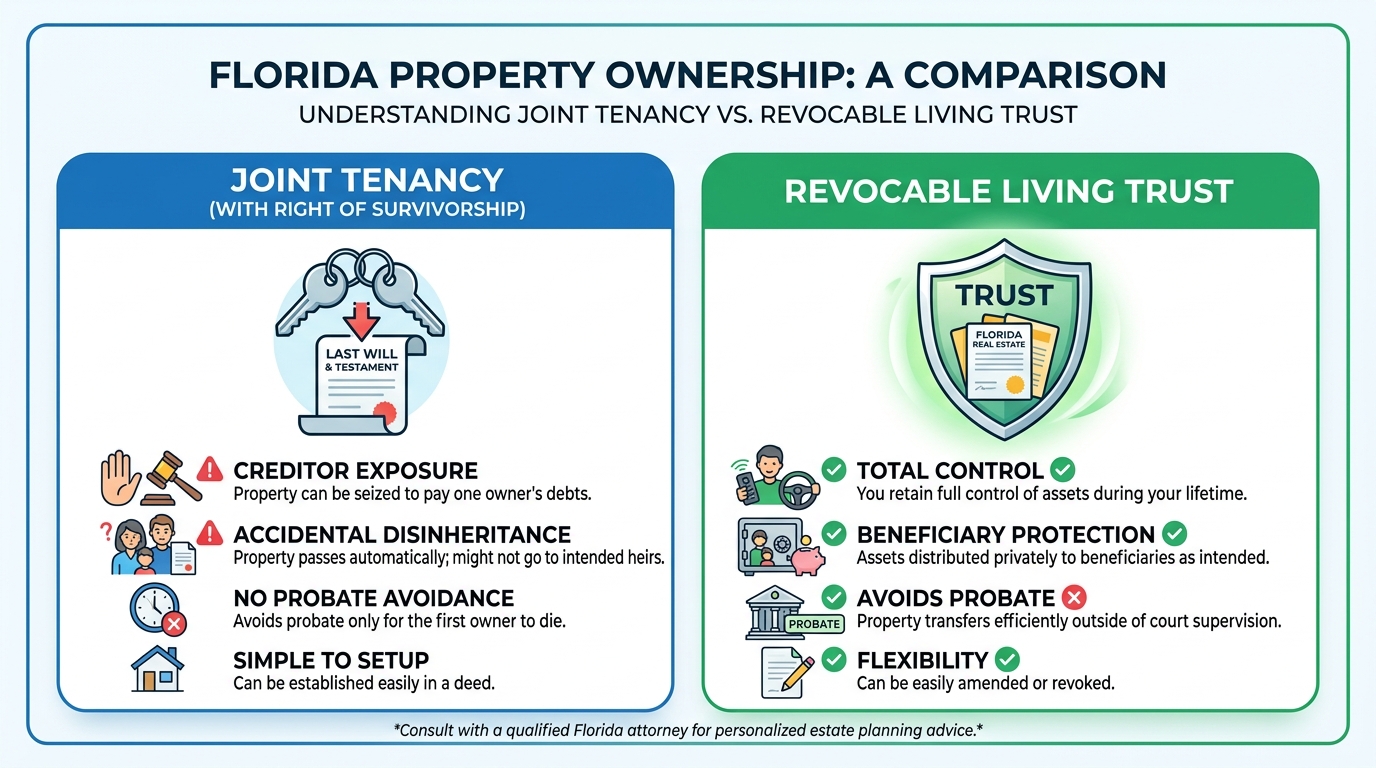
Diagram comparing Joint Tenancy with Right of Survivorship against a Revocable Living Trust under Florida law.

Direct Answer:

Joint Tenancy with Right of Survivorship (JTWROS) in Florida bypasses probate under Fla. Stat. § 689.15, but it completely overrides your Last Will and Testament. Upon the death of one joint owner, title vests immediately and automatically in the surviving owner. This exposes assets to the survivor’s future creditors, potential remarriage claims, and total disinheritance of biological children from prior marriages.


Governed by Will Directives Joint Tenancy completely overrides your Will. A Revocable Trust strictly enforces every distribution instruction in your estate plan.
Co Owner Creditor Protection Joint Tenancy exposes your assets to co owner debts and lawsuits. A Revocable Trust protects assets from third party beneficiary liabilities.

Many South Florida homeowners and account holders add adult children, second spouses, or relatives to bank accounts and real estate deeds as a quick shortcut to avoid formal probate court proceedings.

While adding a joint owner appears convenient on the surface, Joint Tenancy with Right of Survivorship (JTWROS) is one of the most unpredictable, blunt force mechanisms in estate planning. Under Florida property and probate law, joint titling strips away your lifetime financial control, exposes your hard earned assets to outside lawsuits, and routinely triggers accidental family disinheritance.


3 Fatal Vulnerabilities of Joint Ownership Under Florida Estate Law


1. Automatic Property Transfer Overrides Your Will and Intentions

Under Florida Statute § 689.15, when property or financial assets are held as joint tenants with right of survivorship, the deceased co owner’s interest transfers instantly to the surviving co owner upon death by operation of law.

Your Last Will and Testament, Revocable Trust instructions, or verbal promises made to family members carry zero legal weight. If a parent adds one adult child to a Coral Springs real estate deed purely for administrative convenience or convenience check writing, that child becomes the sole legal owner upon the parent’s death, completely cutting out their siblings regardless of what the parent’s Will specifies.

2. Immediate Asset Exposure to Co Owner Liabilities and Creditors

The moment you name a joint owner on a bank account or Broward County real estate deed, that individual gains immediate legal ownership rights. If your co owner faces a divorce proceeding, automobile accident lawsuit, business bankruptcy, or personal tax lien, judgment creditors can attach claims directly to your shared asset. You effectively gamble your lifelong financial security on your co owner’s personal financial discipline and legal stability.

3. The Blended Family Disinheritance Trap

In blended families with children from prior relationships, joint titling regularly causes catastrophic estate outcomes.

When a married couple holds real estate or bank accounts jointly with right of survivorship, all assets vest exclusively in the surviving spouse upon the first spouse’s death. When that surviving spouse eventually passes away, the entire estate passes to their personal biological children or designated heirs. The biological children of the spouse who passed away first receive nothing, creating permanent financial alienation between stepfamilies.


Official Florida real estate deed document highlighting joint tenancy with right of survivorship legal language.

Real World Legal Case Study: In re Estate of Kester

A clear example of how joint titling destroys testamentary intent is illustrated in the official Florida legal precedent In re Estate of Kester, Fla. 4th DCA 1986), decided by the Fourth District Court of Appeal in West Palm Beach.

The Case Background

In this landmark dispute, a mother executed a formal Last Will and Testament directing that her entire estate be divided equally among her children. However, for everyday banking convenience, she established joint bank accounts and credit union shares with right of survivorship naming only one of her daughters as a co owner.

The Legal Conflict

Following the mother’s death, the siblings brought legal action in court, arguing that the funds in the joint accounts were intended for the benefit of all children under the terms of the mother’s Will, and that the joint owner held those funds merely as a fiduciary for the estate.

The Court Ruling

The Fourth District Court of Appeal ruled firmly against the other siblings. The appellate court held that under Florida statutory law governing joint accounts, titling an account as joint tenancy with right of survivorship creates a strong legal presumption of an absolute gift to the surviving joint owner.

Because the disappointed siblings could not provide clear and convincing written evidence proving the mother did not intend to create a survivorship right at the exact moment the accounts were established, the surviving joint daughter kept the entirety of the money. The clear instructions contained inside the mother’s Last Will and Testament were completely ignored and legally powerless.


Superior Florida Legal Alternatives to Joint Ownership

Rather than risking loss of control or accidental disinheritance through joint titling shortcuts, comprehensive estate plans utilize flexible legal structures designed under Florida statutory law:

1. Revocable Living Trust

Establishing a trust under Fla. Stat. Chapter 736 allows you to maintain 100 percent sole authority over your real estate and financial accounts during your lifetime. Upon death, your named successor trustee distributes property to your designated beneficiaries according to your exact written terms, achieving complete probate court avoidance without exposing your assets to co owner debts or disinheriting loved ones.

2. Florida Financial Durable Power of Attorney

If your main objective is allowing a trusted child or relative to assist with bill paying, property maintenance, or financial management during a health crisis, executing a Durable Power of Attorney (Fla. Stat. § 709.2104) grants them legal administrative authority without giving them property ownership rights or subjecting your assets to their personal creditors.

3. Enhanced Life Estate Deed (Lady Bird Deed)

For primary residential property in Coral Springs, Fort Lauderdale, or anywhere in Broward County, an Enhanced Life Estate Deed allows a property owner to retain total lifetime ownership rights, including the right to sell, lease, or mortgage the home without obtaining permission, while designating an automatic transfer on death beneficiary that completely bypasses Florida probate.


Aerial view of residential homes in Coral Springs Broward County Florida illustrating real estate property ownership.

Frequently Asked Questions

Does joint ownership avoid probate in Broward County?

  • Yes, joint tenancy with right of survivorship avoids probate upon the death of the first co owner. However, when the surviving owner eventually passes away without establishing formal trust planning, the property must pass through formal Florida probate administration.

Can I remove a joint owner from my Florida real estate deed without their consent?

  • No. Once an individual is added to a deed as a joint tenant in Florida, you cannot remove them, sell the property, or execute mortgages without their formal notarized signature, even if you originally paid for the entire property yourself.

What is the legal difference between Joint Tenancy and Tenancy by the Entirety in Florida?

  • Tenancy by the Entirety is a specialized form of joint ownership reserved strictly for legally married couples under Florida law. It provides built in creditor protection against individual spouse liabilities that standard Joint Tenancy does not offer.

Can a Last Will override a joint bank account in Florida?

  • No. Under Florida law, joint accounts with right of survivorship transfer automatically upon death. A Last Will carries no legal authority to alter or redistribute funds held in a valid joint survivorship account.

Protect Your Property and Family Autonomy in Coral Springs

Shortcuts like joint ownership frequently create expensive courtroom battles and ruined family relationships later on. The legal team at Reinfeld & Cabrera, P.A. helps South Florida property owners evaluate titles, structure revocable living trusts, and secure family legacies across Broward County.


Schedule a Free Confidential Legal Evaluation

Ensure your assets and real estate remain completely protected under Florida law:

  • Direct Phone: (954) 866-4878 | (954) 334-1520
  • Coral Springs Main Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Online Scheduling: mypersonalattorneys.com
  • Regional Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, Coconut Creek, and surrounding Broward County communities.

Florida Security Deposit Rules: What Landlords Need to Know to Protect Their Rental Investments

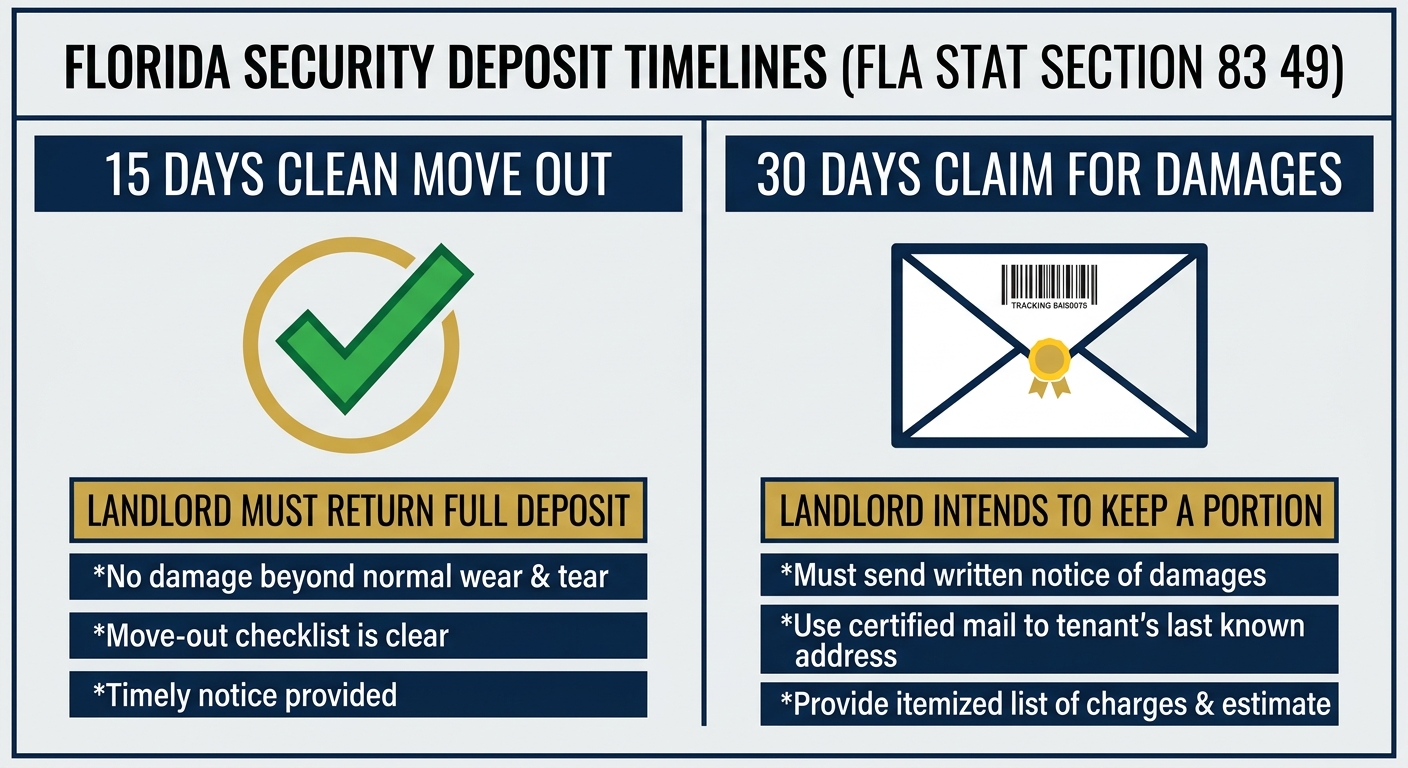
Infographic displaying Florida statutory security deposit return deadlines: 15 days for full refunds and 30 days for Certified Mail damage claims under Fla Stat 83 49.

If you manage or own rental property in South Florida, tenant turnovers and the occasional eviction are bound to happen. But here is the catch: when a lease ends or a tenant vacates under court order, how you handle their security deposit can make or break your legal standing.

Can you simply keep the deposit to cover unpaid rent or property damage? Not without following Florida procedural rules to the letter. Missing a statutory deadline or skipping a certified letter notice can strip away your legal right to hold those funds even if the tenant destroyed your floors or walked out owing months of rent.

So how does Fla. Stat. § 83.49 actually work when you are standing inside an empty unit staring at ruined drywall? What concrete steps must you take right now to protect your bottom line, and how can you keep yourself far away from costly disputes in local South Florida courtrooms? Let us break down everything you need to navigate move outs safely.


What Are Florida Security Deposit Notice Deadlines?

Quick Answer: Under Fla. Stat. § 83.49, Florida landlords have 15 days to return a security deposit in full if no deductions are being made. However, if you are claiming money for property damage, deep cleaning, or unpaid rent, you have 30 days to send an itemized claim via Certified Mail to the tenant last known address. If you fail to send this notice within 30 days, you legally forfeit your right to claim any part of the deposit.


The Core Rule: 15 Days vs 30 Days

Why do so many property owners get tripped up by Florida security deposit timelines? Usually, it comes down to confusing a clean turnover with a damage claim. You might ask yourself: Am I simply handing back their money, or am I preparing to fight for repair costs? The law divides move outs into two distinct paths:

  • No Claim on Deposit (15 Days): Timeline is 15 days from move out. Action requires a full refund plus accrued interest if held in an interest account. Target is clean turnovers.
  • Imposing a Claim (30 Days): Timeline is 30 days from move out. Action requires sending an itemized claim via Certified Mail containing required statutory text. Target covers physical damage, back rent, or unpaid utility fees.

1. The Clean Turnover (15 Day Window)

Suppose your tenant moves out, hands over the keys, and leaves the home in excellent shape with zero unpaid rent. Under Fla. Stat. § 83.49(3)(a), you have exactly 15 days from the date they vacate to return their full deposit along with any accrued interest if kept in an interest bearing account.


2. The Damage or Back Rent Claim (30 Day Window)

Now, what if you walk into the property and find broken drywall, ruined carpets, or an unpaid utility balance? Would a quick text message or an informal email suffice to let them know you are withholding funds? Absolutely not.

In this scenario, you have 30 days to issue a formal written notice detailing your intent to keep part or all of the deposit. Florida law strictly mandates that this notice must be sent by Certified Mail to the tenant forwarding address or last known mailing address. I often tell property owners to treat that certified mail receipt like pure gold because without it, proving you met your 30 day clock becomes nearly impossible.


What Happens if You Skip the Statutory Warning Language?

Here is a detail that continuously catches self managing landlords off guard: it is never enough to write a quick note stating, “I am keeping $500 for carpet repairs.”

Florida statute explicitly mandates that your notice include specific statutory warning language informing the tenant of their right to object within 15 days. What actually happens if you leave this mandatory wording out? Legally, the entire notice becomes invalid. That means you forfeit your right to retain the deposit and could end up paying the tenant legal fees under Fla. Stat. § 83.48 if they retain an attorney to contest your error.

I always think: Why risk losing thousands over a missed paragraph when the statute gives you the exact script to copy?

Florida residential lease agreement and legal consultation documents at the law offices of Reinfeld Cabrera Tison in Coral Springs Florida.

The 15 Day Tenant Objection Clock

Once the tenant receives your certified letter, the ball moves directly into their court:

  • If they do not object within 15 days: You are legally authorized to deduct the claimed amount from the deposit and return any remaining balance to them within 30 days of the original notice date.
  • If they object in writing: You now have a formal legal dispute on your hands. If that disagreement escalates into county court in Broward, Miami Dade, or Palm Beach County, a judge will review whether every single statutory notice rule was meticulously followed.
Rental property move out inspection checklist sitting next to a Certified Mail receipt and tenant keys in a South Florida residential apartment.

What Counts as Legitimate Deductions vs Normal Wear and Tear?

One of the most frequent friction points between landlords and departing tenants is deciding what damage justifies keeping deposit funds.

Before you start writing up your itemized bill, ask yourself: Is this issue the natural result of everyday human living, or does it represent actual property destruction and tenant negligence?

Permissible Deductions (Tenant Damage)

  • Unpaid rent, fees, or utility balances
  • Holes in drywall, broken doors, or cracked floor tiles
  • Pet damage such as scratched doors, carpet stains, or deep odors
  • Trash removal and heavy cleaning charges for abandoned personal property

Impermissible Deductions (Normal Wear and Tear)

  • Faded wall paint or small nail holes from picture frames
  • Minor carpet wear or light scuffs along high traffic hallways
  • Aging, worn door handles or standard cabinet hinges
  • Routine HVAC filter servicing or standard dust accumulation

Frequently Asked Questions for Florida Landlords

What if I completely miss the 30 day Certified Mail deadline?

  • If you miss the 30 day window, you automatically forfeit your right to retain the security deposit under Fla. Stat. § 83.49, meaning you must return 100 percent of the money to the tenant. Does this mean you are completely out of options if they wrecked your rental property? Not entirely. Missing the deposit deadline prevents you from holding onto their deposit money, but it does not prevent you from filing a separate lawsuit against the former tenant in court for breach of contract or physical property damage.

Does winning an eviction judgment mean I can automatically keep the deposit?

  • Surprisingly, no. Even if you secure a writ of possession in the 17th Judicial Circuit Court of Broward County, you remain legally bound to send the 30 day certified claim notice if you intend to apply the security deposit toward back rent or damages caused by the evicted tenant. I see landlords fall into this exact trap all the time assuming an eviction order wipes out their security deposit duties.

Can I include a clause in my lease waiving these notice rules?

  • No. Florida courts treat Fla. Stat. § 83.49 as a mandatory protection statute. Any clause inside a residential rental agreement that attempts to bypass, shorten, or alter these statutory notice timelines is considered legally null and void.

Protect Your Real Estate Investments with Legal Counsel

Whether you manage a single rental home in Coral Springs or an apartment complex in Fort Lauderdale, administrative slip ups during tenant move outs can cost you thousands in lost funds and legal fee awards.

The real estate litigation team at Reinfeld & Cabrera P.A. helps South Florida landlords, investors, and property managers enforce lease agreements, execute formal evictions, and navigate security deposit compliance smoothly.

Schedule a Property Law Consultation

Facing a tenant dispute or need assistance structuring legally compliant lease agreements? Speak directly with a South Florida real estate attorney today:

  • Direct Telephone: (954) 866 4878 | Toll Free: 954 866 HURT
  • Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Website: mypersonalattorneys.com
  • Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and surrounding communities across Broward, Miami Dade, and Palm Beach Counties.

How to Choose an Estate Planning and Probate Attorney in Coral Springs

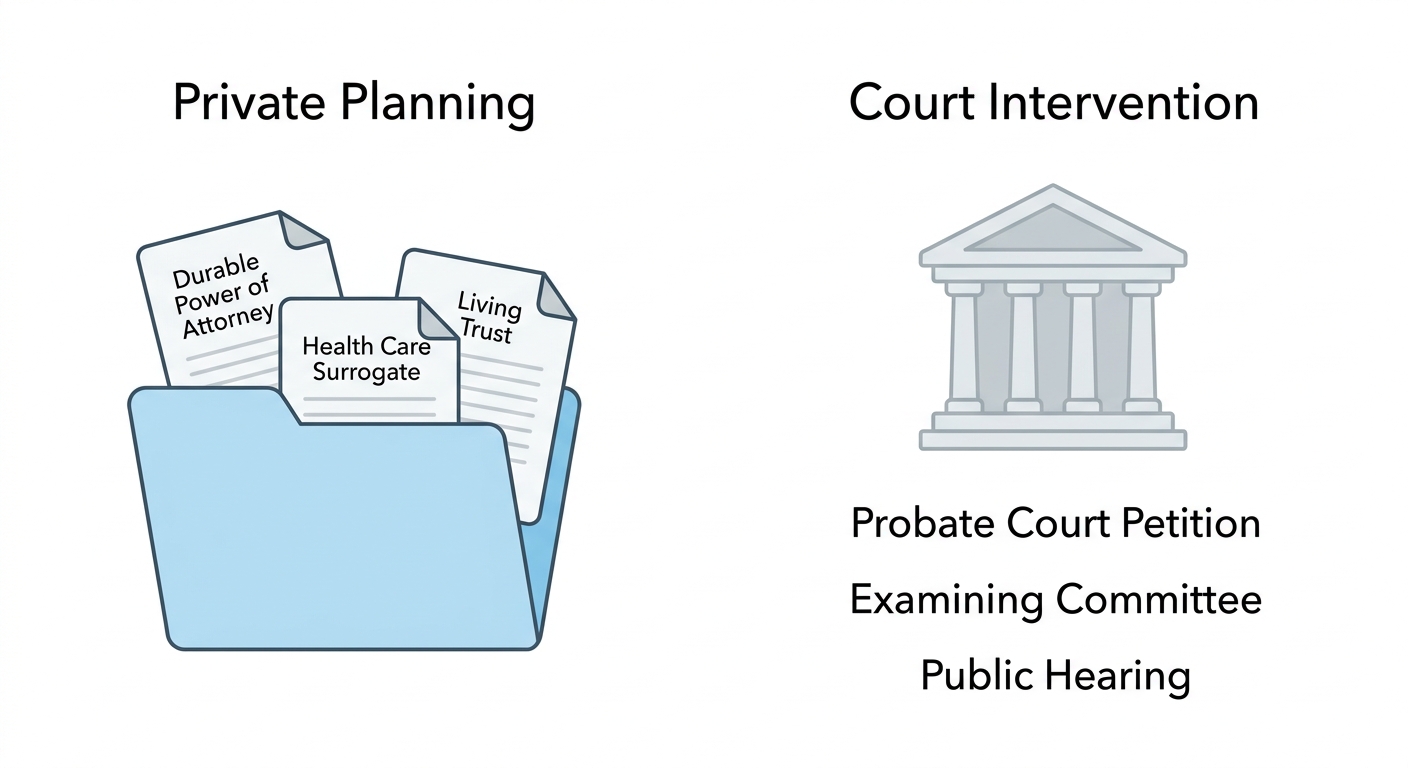
Diagram comparing private Florida incapacity planning documents with judicial probate court guardianship proceedings.

Direct Answer:

Selecting an estate planning and probate attorney in Coral Springs requires evaluating local Broward County courtroom experience, mastery of Florida trust statutes (Fla. Stat. Chapter 736), and integrated knowledge of Florida constitutional homestead laws (Fla. Const. art. X, § 4).

A qualified local attorney ensures wills, revocable trusts, and powers of attorney comply with strict execution requirements while guiding personal representatives through formal or summary probate proceedings in the 17th Judicial Circuit Court of Broward County.


Critical Evaluation Framework for Local Legal Counsel

Florida Statutory Compliance

  • Fla. Stat. Chapter 736 (Trust Code)
  • Fla. Stat. Chapter 709 (Durable Power of Attorney)
  • Fla. Stat. Chapter 765 (Health Care Directives)

Broward Judicial Experience

  • 17th Judicial Circuit Court Rules
  • Local Broward Clerk Filing Protocols
  • Probate Division Judicial Orders
Reinfeld & Cabrera Legal Representation Hub

Securing your family’s financial future, protecting physical property, and ensuring seamless asset distribution requires thoughtful legal strategy. While online document assembly services promise cheap, automated legal templates, generic forms regularly fail under Florida probate court scrutiny.

Florida estate law involves intricate statutory execution rules, unique real estate protections, and strict probate filings across Broward County. Understanding how to choose an experienced local attorney is the single most important step in protecting your life savings and preserving your legacy.


5 Essential Standards When Evaluating Coral Springs Estate Legal Counsel


1. Direct Mastery of Florida Specific Estate and Trust Statutes

Florida law does not follow generic federal templates or out of state legal norms. Your legal counsel must maintain a daily transactional practice grounded in specific Florida legislation:

  • Florida Trust Code (Fla. Stat. Chapter 736): Regulates the creation, amendment, revoking, and administration of revocable and irrevocable trusts. It establishes strict fiduciary standards for named trustees and protects beneficiary distribution rights.
  • Florida Power of Attorney Act (Fla. Stat. Chapter 709): Governs financial durable powers of attorney. Under Florida law, general sweeping clauses are ineffective unless specific statutory superpowers under Fla. Stat. § 709.2114 are explicitly initialed by the principal.
  • Florida Probate Code (Fla. Stat. Chapters 731 through 735): Controls the judicial validation of wills, opening of estates, creditor notification periods, and final asset distribution.
  • Florida Health Care Advance Directives (Fla. Stat. Chapter 765): Outlines the legal appointment of health care surrogates, living wills, and anatomical gifts.

2. Local Courtroom and Judicial Experience in Broward County

Estate planning and probate are deeply localized practice areas. An attorney who regularly represents clients before the 17th Judicial Circuit Court in Fort Lauderdale understands local judicial preferences, divisional filing protocols, and clerk processing workflows.

When a loved one passes away, local judicial experience ensures that petitions for administration, orders appointing personal representatives, and letters of administration move through the Broward County probate court system without administrative rejections or unnecessary delays.


3. Integrated Florida Constitutional Homestead Protection

For the vast majority of Coral Springs and Parkland homeowners, primary residential real estate represents their largest asset. Under Florida Constitution Article X, Section 4, primary residential property enjoys unique protection from forced sale by creditors.

However, Florida homestead devise restrictions strictly limit how a primary home can be left in a Will or Trust if the owner is survived by a spouse or minor children. An experienced Coral Springs attorney knows how to structure deeds, trusts, and spousal waivers to preserve homestead protections while avoiding title clouding or unintended tax consequences.


Florida Constitutional Homestead Advantages
Creditor Exemption Protection Protects primary residential equity from forced sale by judgment creditors under Florida law.
Property Tax Cap Limits Locks annual assessed property value increases under Florida Save Our Homes assessment caps.
Strict Devise Restrictions Protects rights of surviving spouses and minor children regarding real estate transfers.

4. Comprehensive Probate Avoidance and Administration Capabilities

A complete legal counselor does not simply hand you a stack of paper and send you on your way. Your attorney must possess expertise across both proactive planning and reactive administration:

  • Incapacity Avoidance: Structuring financial durable powers of attorney and health care surrogates to prevent involuntary adult guardianship court hearings under Fla. Stat. Chapter 744.
  • Summary Probate Administration: Navigating expedited court proceedings under Fla. Stat. Chapter 735 for estates under $75,000 or where the decedent has been deceased for more than two years.
  • Formal Probate Administration: Managing complex court supervised estates requiring personal representative appointments, formal notice to creditors, estate accounting, and tax releases.

5. Proven Community Reputation and Legal Continuity

Estate planning is an ongoing lifetime relationship. As your family grows, assets change, and Florida tax laws evolve, your estate plan requires periodic reviews.

Recognized over the years by local Coral Springs community awards, Reinfeld & Cabrera, P.A. has established a decade long legacy of personal legal representation across Broward County. Choosing a stable, locally rooted firm ensures that the attorneys who drafted your trust will be available decades later to guide your loved ones through its execution.


Close up photograph of executed Florida Durable Power of Attorney and Designation of Health Care Surrogate legal documents.

Comparing Online DIY Legal Forms vs. Local Attorney Representation

Operational FeatureOnline DIY Document GeneratorLocal Coral Springs Legal Counsel
Florida Execution ComplianceHigh risk of improper witnessing or notarizationStrict compliance with Fla. Stat. § 732.502
Homestead Protection IntegrationGeneric forms ignore Florida constitutional restrictionsCustomized deed drafting and tax cap protection
Local Probate Court KnowledgeZero court presence or regional administrative supportDirect filing experience in 17th Judicial Circuit Court
Fiduciary GuidanceNo legal advice on selecting agents or trusteesProfessional counseling on trustee appointment
Custom Contingency PlanningRigid templates that fail during complex family changesBespoke trust structures adapted to family dynamics

Frequently Asked Questions

Why shouldn’t I use a basic online Will template in Florida?

  • Florida law requires strict execution formalities under Fla. Stat. § 732.502, including execution in the presence of two signing witnesses and a qualifying notary public. Online templates routinely miss unique Florida requirements, such as statutory power of attorney superpowers or constitutional homestead devise limits, rendering documents invalid or triggering expensive probate disputes.

What is the difference between summary administration and formal probate in Broward County?

  • Summary administration is an abbreviated court proceeding available if the total value of probate assets subject to administration is $75,000 or less, or if the decedent has been deceased for over two years. Formal administration is required for larger estates and involves appointing a personal representative to marshal assets, clear creditor claims, and manage distributions.

How often should I review my Coral Springs estate plan with an attorney?

  • You should review your estate plan every three to five years, or immediately following major life events such as marriage, divorce, the birth of a child, purchase of new real estate, significant changes in financial assets, or relocation to Florida from another state.

Can an out of state Will be used in Florida?

  • A Will executed in another state can be valid in Florida if it strictly met the execution laws of the state where it was signed. However, out of state Wills often name non resident personal representatives who may not qualify under Florida eligibility rules (Fla. Stat. § 733.304) or fail to utilize Florida specific probate shortcuts.

Dedicated Estate Planning and Probate Counsel in Coral Springs

At Reinfeld & Cabrera, P.A., lead attorney Alan J. Reinfeld and our legal team deliver tailored estate planning and probate solutions to South Florida families. We take the time to understand your personal goals, protect your real estate assets, and provide clear legal guidance through every stage of life.


Exterior view of the Broward County Judicial Complex in Fort Lauderdale Florida home to the 17th Judicial Circuit probate division.

Schedule a Free Confidential Case Evaluation

Speak directly with an experienced Coral Springs estate attorney today:

  • Direct Phone: (954) 866-4878 | (954) 334-1520
  • Coral Springs Main Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Online Scheduling: mypersonalattorneys.com
  • Regional Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, Coconut Creek, and all surrounding Broward County communities.

Florida Adult Guardianship Avoidance: The Legal Architecture of Lifetime Autonomy

Diagram comparing private Florida incapacity planning documents with judicial probate court guardianship proceedings.

Direct Answer:

In Florida, adult guardianship is avoided by executing three proactive, legally binding instruments while mentally competent: a Durable Power of Attorney (Fla. Stat. § 709.2104), a Designation of Health Care Surrogate (Fla. Stat. § 765.202), and a Revocable Living Trust. Together, these documents grant immediate, private decision-making authority to chosen surrogates, preventing the 17th Judicial Circuit Court of Broward County from declaring incompetence or appointing a court-monitored professional guardian under Fla. Stat. Chapter 744.


Why a Florida Last Will and Testament Fails During a Lifetime Health Crisis

The most pervasive misconception among Florida property owners is the belief that a well-crafted Will protects their business, real estate, and financial accounts if they suffer a debilitating stroke, traumatic brain injury, or severe cognitive decline.

A Will is legally dormant until death. It grants zero authority during your lifetime.

If you lose legal capacity without specific lifetime governance documents, your family cannot simply present your Will to Bank of America, Chase, or a Broward County title company. Instead, your loved ones are forced into a rigid, public, and adversarial legal process known as Involuntary Adult Guardianship.


Path A: Proactive Planning (Private) Path B: Court Intervention (Guardianship)
1. Key Legal Instruments:
  • Durable Power of Attorney
  • Health Care Surrogate
  • Revocable Living Trust
1. Emergency Court Petition:

Filed in the Broward County Circuit Court by family, health care providers, or interested third parties.

2. Immediate Authority:

Your designated agent or trustee steps in immediately without court permission.

2. 3-Member Examining Committee:

Court appoints a physician, medical expert, and layperson to evaluate your mental competency.

3. Privacy & Autonomy:

Financial affairs and health decisions remain strictly private within the family.

3. Public Incompetency Hearing:

Formal court hearing stripping fundamental constitutional rights and declaring legal incapacity.

Final Outcome: Seamless Family Management

Zero court fees, no public record, immediate operational continuity.

Final Outcome: Court Guardian Control

Appointed professional guardian, mandatory annual audits, assets drained by legal fees.


The Financial and Personal Realities of Florida Guardianship Proceedings

When a court petition is filed under Florida Statute Chapter 744, you become the “Alleged Incapacitated Person” (AIP). The judicial process moves quickly, privately stripping personal freedoms through public records:

1. Mandatory 3-Member Examining Committee

Under Fla. Stat. § 744.331, the court appoints an examining committee consisting of three professionals (at least one must be a medical doctor or psychiatrist). These individuals visit your home or hospital room, conduct cognitive testing, and submit written assessments directly to the Broward County judge.

2. Immediate Loss of Fundamental Civil Rights

If the court finds you incapacitated, you do not just lose access to your checking account. You lose the legal right to:

  • Contract, sign deeds, or manage business interests
  • Choose where you live or consent to medical treatment
  • Vote, hold a driver’s license, or marry
  • Retain personal legal counsel of your choice

3. The Financial Strain of Professional Guardianship

A court-appointed guardian is entitled to reasonable compensation paid directly out of your assets. Every financial move—selling a home in Coral Springs, liquidating stock, or paying for specialized memory care—requires formal court petitions, attorney appearances, and annual financial audits overseen by the clerk of court.


Signing a Florida Durable Power of Attorney document with witness and notary signature blocks.

Real World Precedent: How Lack of Planning Triggers Systemic Vulnerability

To understand why Florida courts step in so forcefully, one needs to look no further than the notorious state guardianship cases that led to major legislative reforms across South Florida.

Consider the real life case of Jan Garwood, a Central Florida resident who suffered a sudden medical crisis without a complete, active incapacity plan in place.

┌────────────────────────────────────────────────────────┐
│               THE REALITY OF COURT CONTROL             │
├───────────────────────────┬────────────────────────────┤
│    WITHOUT A DPOA / TRUST │  WITH PROACTIVE R&C PLAN   │
├───────────────────────────┼────────────────────────────┤
│ Forced court petition     │ Private family transition  │
│ 3-person medical panel    │ Designated agent steps in  │
│ Court-appointed guardian  │ Zero court costs or fees   │
│ House sold without consent│ Assets fully protected     │
└───────────────────────────┴────────────────────────────┘

After an emergency hospital admission under the Baker Act, the hospital petitioned the court to appoint a professional guardian. Because Garwood lacked a updated Durable Power of Attorney and Revocable Living Trust specifically naming trusted family members to handle her affairs:

  1. The Court Intervened Immediately: A judge declared her incompetent based on brief examining committee reports, bypassing her family.
  2. Loss of Property: The court appointed professional guardian gained complete control over her finances, eventually selling her home to cover facility care costs.
  3. Loss of Autonomy: Garwood spent three years in a locked assisted living facility before independent attorneys managed to restore her rights, by which time her personal assets had been liquidated.

Cases like Garwood’s—and the widespread Florida state investigations into court appointed guardians that followed—highlight a critical legal reality: If you do not choose your own decision makers through private estate planning documents, a Florida probate court will choose one for you.


The Incapacity Avoidance Triad: 3 Key Documents

To lock out judicial interference, an incapacity strategy must unite three precise legal instruments under Florida law:

1. Florida Financial Durable Power of Attorney (DPOA)

  • Governed by Fla. Stat. § 709.2104, a Florida DPOA must contain specific “superpowers” (explicit initialed clauses under Fla. Stat. § 709.2114) granting your named agent the legal right to manage real estate, conduct banking, handle tax returns, and qualify for governmental benefits without court approval.

2. Florida Designation of Health Care Surrogate

  • Under Fla. Stat. § 765.202, this instrument allows your named surrogate to consult with doctors, review HIPAA-protected medical records, authorise surgeries, and make end-of-life decisions if you become unable to provide informed consent.

3. Revocable Living Trust

  • Holding property, financial accounts, and business equity inside a revocable trust creates an unbroken chain of authority. If you face incapacity, your named Successor Trustee steps in seamlessly to manage trust assets according to your written directives, eliminating the need for court supervision.

Exterior view of the Broward County Judicial Complex in Fort Lauderdale Florida housing the 17th Judicial Circuit probate court.

Frequently Asked Questions

Can my spouse automatically handle my finances if I become incapacitated?

  • No. Spousal status alone does not grant legal authority to sign deeds, alter bank accounts, or manage individually held assets in Florida. Without a valid Durable Power of Attorney or Trust, a spouse must petition the court for guardianship just like any third party.

What is the difference between a Power of Attorney and a Guardian?

  • A Power of Attorney agent is chosen privately by you while you are mentally sound. A Guardian is appointed by a judge after a court determination of incompetence.

Does a Durable Power of Attorney expire upon incapacity in Florida?

  • No. Unlike a standard power of attorney, a Durable Power of Attorney explicitly remains effective during temporary or permanent mental incapacity under Fla. Stat. § 709.2104.

Protect Your Independence with a Coral Springs Estate Planning Attorney

Maintaining total control over your health choices, personal dignity, and financial assets requires clear legal planning before a sudden health crisis occurs.

The estate planning attorneys at Reinfeld & Cabrera, P.A. help individuals and families across Coral Springs, Fort Lauderdale, and Broward County construct airtight incapacity plans that bypass court intervention entirely.


Schedule a Confidential Consultation

Ensure your autonomy remains protected under Florida law:

  • Direct Telephone: (954) 866-4878
  • Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Website: mypersonalattorneys.com
  • Regional Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all surrounding Broward County communities.

How to Name a Guardian for Your Child in Florida (Without Causing a Family Civil War)

Florida parents reviewing and signing a preneed guardian designation in a South Florida estate planning law office.

Quick Answer :

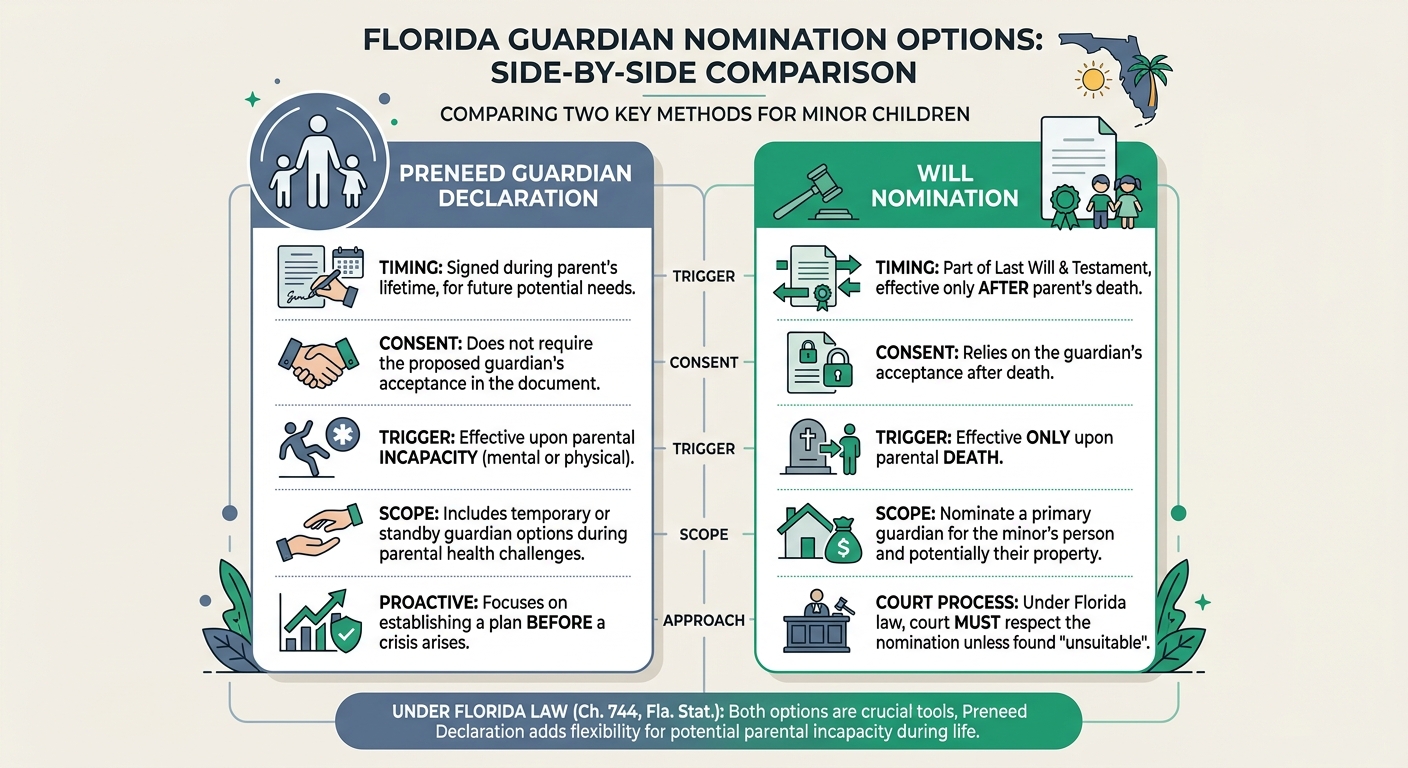
Under Florida law (Fla. Stat. § 744.3046), parents can name a guardian for minor children by executing a formal Preneed Guardian Designation signed in the presence of two simultaneous witnesses. Unlike a will, which only activates upon death, a preneed designation protects your children during parental death or medical incapacity.

The document creates a strong presumption in court favoring your chosen primary and alternate guardians, allowing you to split physical care (Guardian of the Person) from financial management (Guardian of the Property).


Let us be completely honest with each other for a moment. Nobody wakes up on a sunny Saturday, pours a mug of coffee, and cheerfully says, “You know what sounds fun today? Figuring out who raises my children if my spouse and I get eaten by a shark or crushed by a meteor.”

It is uncomfortable. It makes your stomach do little flip flops. And if you are like most parents in South Florida, your default setting is simply to kick the can down the road, assuming your sister or your mother will just step in and figure it out if the unthinkable happens.

Except Florida law does not work on gentle assumptions. If you do not formally put your wishes in writing using proper legal execution rules, a circuit court judge who has never met your family will be forced to make that choice for you.

So how do you actually name a guardian for your minor children in Florida, avoid a holiday dinner feud between the in laws, and make sure your intentions stand up in court? Let us break down how parental designations work without any dry corporate nonsense or confusing legalese.


Why the Internet Gets Child Guardianships Wrong

If you search online late at night while spiraling into panic, you will find plenty of generic advice. Telling you to just type up a short note or throw a sentence into a basic Last Will and Testament.

Nominating a guardian in your will is a very common approach. But relying solely on a will leaves a massive, gaping hole in your legal safety net.

Ask yourself: What happens if you and your spouse are in a serious car accident and end up in a coma for six months?

A will only springs to life after you pass away. If you are incapacitated rather than deceased, a judge cannot use your will to authorize someone to care for your kids or handle their day to day needs. That is why Florida estate planning relies on specialized advance designations that cover both incapacitation and death.


Preneed Guardians vs. Standby Guardians: Decoding the Legal Jargon

Florida law gives parents two primary legal mechanisms to nominate who steps in when disaster strikes. You do not need a law degree to understand them, but you do need to know which one fits your situation.
1. The Preneed Guardian Designation (Fla. Stat. § 744.3046)

Think of this as your official written nomination letter to the local probate court. Under Florida law, parents can sign a formal declaration naming a primary guardian and an alternate guardian.

  • How it works: You sign the document ahead of time with two attesting witnesses present at the exact same time. If both parents pass away or become incapacitated, the document is produced in court. This creates a powerful legal presumption that the judge should honor your chosen person.
  • Why it matters: It covers both death and medical incapacity, seamlessly closing the gap that a standard will leaves behind.

2. Standby Guardianship (Fla. Stat. § 744.304)

A standby guardian is a slightly different tool designed for immediate handoffs.

  • How it works: This involves a pre approved court petition where a designated guardian stands in the wings. He or she is ready to act instantly upon a specific triggering event (like severe medical decline or death). The standby guardian assumes duties immediately and then has 20 days to file a formal petition for court confirmation.


The Person vs. The Property: You Do Not Have to Pick Just One Human

Here is a common dilemma that paralyzes parents: Your brother is incredible with kids, warm, patient, and living in a great school district, but he handles money like a golden retriever with a stolen credit card. Meanwhile, your accountant sister is a financial wizard, but her idea of childcare is handing a toddler a spreadsheet.

Good news: Florida law allows you to split these responsibilities down the middle.

  • Guardian of the Person: This person gets physical custody, decides where the kids live, manages their schooling, signs permission slips, and handles medical decisions.
  • Guardian of the Property: This person manages the financial inheritance, holds onto money left for the children, pays for their expenses out of a trust or court supervised account, and ensures nobody wastes their funds.

You can name the same person for both roles, or you can split them up so your kids get loving care while your financial hawk protects their inheritance.


How to Choose an Alternate (and Avoid In-Law Meltdowns)

Always, always name an alternate guardian. Life happens. Your primary choice might move across the globe, face health challenges of their own, or simply realize that taking on two active toddlers at age fifty five is more than they can physically handle.

When selecting guardians, look beyond raw emotional attachment and evaluate practical realities:

  1. Shared Values and Lifestyle: Do they raise children with similar boundaries, educational goals, and emotional warmth?
  2. Geographic Location: Would your children have to move across the country, switch schools, and leave their support network behind during a time of intense grief?
  3. Financial and Physical Capacity: Do they have the health, energy, and space in their life to raise children through high school and college?

Pro Tip: Talk to the people you want to name before you sign the papers. Finding out after the fact that your prospective guardian never wanted kids in the first place makes for an extremely awkward conversation.


Frequently Asked Questions About Naming a Guardian in Florida

How do I name a guardian for my child in Florida?

  • You can document your intent by executing a formal Preneed Guardian Designation under Fla. Stat. § 744.3046 or by nominating a guardian within your Last Will and Testament. The document must comply strictly with Florida signing formalities, including two simultaneous attesting witnesses.

Can I name a guardian for my minor child in my will?

  • Yes. Florida law allows parents to nominate a guardian inside a will. However, because a will only takes effect upon death, pairing it with a Preneed Guardian Designation ensures your choices are legally documented if you become incapacitated.

What is a preneed guardian for a minor in Florida?

  • A preneed guardian is a person formally nominated by living parents to step in, take custody, or manage property for a minor child if the parents die or lose legal capacity.

Can I name an alternate guardian for my child?

  • Yes. Florida statutes explicitly encourage parents to name an alternate preneed guardian in case your primary choice is unable or unwilling to serve when the time comes.

What happens if both parents die without naming a guardian?

  • If no written designation exists, any interested family member or party can petition the court for guardianship. A judge in the 17th Judicial Circuit will hold hearings and choose a guardian based on what they determine is in the child’s best interests, which may not align with who you would have wanted.

Does the court have to appoint the person named by the parents?

  • While Florida courts give immense weight and priority to a valid preneed designation signed by the parents, the judge retains ultimate authority to verify that the nominee meets statutory qualifications and that the appointment serves the child’s best interests.

Can a guardian be named for a child’s property as well as the child?

  • Yes. Florida law explicitly separates guardianship of the person (physical care and custody) from guardianship of the property (financial management), allowing parents to appoint the same individual or two separate people.

What is the difference between a preneed guardian and a standby guardian?

  • A preneed guardian is nominated in advance on paper and awaits a potential future appointment by the court. A standby guardian is pre approved by court order prior to an emergency and can take physical custody instantly upon a triggering event, with 20 days to get final confirmation from the judge.

Can I change or revoke the guardian I have named for my child?

  • Yes. As long as you are competent, you can revoke, modify, or replace your preneed guardian designation at any time by executing a new written declaration that meets Florida statutory requirements.

Does naming a guardian eliminate the need for a full estate plan?

  • No. Naming a guardian addresses who cares for your children, but it does not manage how your home, bank accounts, or life insurance proceeds are handled. Pairing your guardian designations with a revocable living trust ensures your money is protected and managed smoothly for your kids without ongoing court oversight.

A peaceful Coral Springs community park with tropical palm trees representing family living in Broward County.

Protecting Your Children and Your Peace of Mind

At the end of the day, naming a guardian is not about dwelling on tragic worst case scenarios. It is about taking control, removing uncertainty, and giving yourself total peace of mind knowing that your kids will always be raised by people who love them and share your values.

The estate planning attorneys at Reinfeld & Cabrera P.A. help parents across South Florida establish airtight preneed guardian designations, revocable living trusts, and comprehensive family protection plans.

Schedule a Confidential Consultation

Do not leave your family’s future up to chance or a courtroom schedule. Speak directly with an attorney today to set up your parental designations:

  • Direct Telephone: (954) 866 4878 | Toll Free: (954) 866 HURT
  • Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Website: mypersonalattorneys.com
  • Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all surrounding communities across Broward, Miami Dade, and Palm Beach Counties.

Do You Need a Real Estate Attorney When Buying a House in Florida?

Real estate attorney discussing a home purchase with buyers in Coral Springs, Florida.

Florida does not require every homebuyer to hire an attorney, but legal review can be valuable before signing a purchase contract. A real estate attorney can identify contractual, title, ownership, and closing issues that may affect your rights as a buyer.

For a home purchase in Coral Springs or elsewhere in Broward County, the legal review may involve:

  • Purchase contract: Reviewing financing terms, inspection provisions, deposits, closing deadlines, default provisions, and termination rights.
  • Title: Examining the ownership history and identifying liens, judgments, probate issues, defective deeds, easements, or other recorded interests.
  • Deed and ownership: Determining how the property will be titled and whether the proposed ownership structure fits the buyer’s circumstances.
  • Closing: Reviewing documents and addressing unresolved legal issues before ownership transfers.
  • Florida homestead: Evaluating homestead considerations when the property will be the buyer’s primary residence.
  • Estate planning: Considering how the new property fits into the buyer’s will, trust, and broader estate plan.
  • Probate: Identifying potential probate issues when the property was inherited or when its future transfer may involve an estate.

The timing of the legal review matters. A lawyer who examines the transaction before the purchase contract is signed may be able to identify provisions that become difficult to change later. Title and ownership issues should also be addressed before closing, when resolving them can become more complicated.

For buyers in Coral Springs and Broward County, these questions arise under Florida real estate law, but the appropriate legal strategy depends on the specific property, contract, ownership structure, and family circumstances.


When should you hire a real estate attorney?

Many buyers think about hiring a lawyer when they reach the closing table. By that point, the most important contractual decisions may already have been made.

The purchase contract establishes the legal framework for the transaction. It can determine the buyer’s rights concerning financing, inspections, repairs, deposits, title, closing dates, and termination.

The Florida Bar recommends consulting an experienced Florida real estate lawyer before signing a purchase contract. Its consumer guidance explains that important provisions can become difficult to change once the agreement has been signed.

That timing matters whether you are buying a home in Coral Springs, Fort Lauderdale, Parkland, Coconut Creek, or another Broward County community.

Suppose an inspection later reveals substantial roof damage. The buyer may want the seller to make repairs or provide a credit. Whether the buyer can demand either remedy depends on the contract and the circumstances surrounding the transaction.

The same principle applies to financing problems, delays, title defects, and disputes about property condition.

A lawyer who reviews the agreement before signature can explain what the buyer has agreed to and identify provisions that deserve attention.


What does a real estate attorney do for a homebuyer?

The work depends on the transaction.

A real estate attorney may review the purchase agreement, examine title records, review the deed, address liens and judgments, examine closing documents, advise on ownership, and represent the buyer if a dispute develops.

Some transactions require little legal intervention after the contract and title are reviewed. Others become complicated because of the property’s history.

A house in Broward County may have changed hands several times. A previous owner may have died. A divorce may have affected ownership. An old mortgage may remain in the public record. A judgment may have attached to an owner’s interest. A deed may contain an error.

The current seller may have no knowledge of any of these issues.

That does not necessarily prevent the sale. It does mean that the issue should be identified and resolved before the buyer accepts the property.

For a buyer purchasing a home in Coral Springs, the property’s recorded history deserves the same attention as its current condition.


Why title matters when buying a house

A real estate listing tells you who is selling the property. It does not establish the entire legal history of the property.

A title examination looks at recorded documents affecting ownership. Depending on the property, those records may include deeds, mortgages, liens, judgments, probate documents, and other instruments.

Florida law governs the recording of interests in real property. Florida Statutes Section 695.01 addresses the recording of conveyances, mortgages, and other interests in land and explains when recorded instruments have priority against certain creditors and subsequent purchasers.

For a buyer, the practical issue is whether the seller can deliver the ownership interest required by the purchase contract.

Consider a property that has passed through several generations.

The owner listed on the tax record may have inherited the house from a parent. That parent may have inherited it from someone else. At some point, an estate may have been administered incorrectly or a deed may have failed to include someone whose interest mattered.

The problem can remain hidden until the property is sold.

A title examination can reveal that history.

This is particularly relevant in established Broward County neighborhoods, where some properties have changed ownership several times over many years.


Florida real estate attorney reviewing a property deed and title documents.

What happens when the seller inherited the house?

Inherited property can create title questions that do not appear in an ordinary residential sale.

If the seller acquired the property through an estate, the circumstances surrounding that transfer may need to be examined. The buyer may need documentation showing how ownership passed from the deceased person to the current seller.

Probate can therefore become part of a real estate transaction.

This is one reason real estate law and probate law sometimes meet in the same file.

A buyer does not need to become an expert in probate procedure. The important question is whether the person selling the property has the legal authority to transfer the interest the buyer expects to receive.

If that authority is unclear, the transaction may need additional documentation or court action before closing.

A buyer should not assume that an inherited property has a clean title simply because the seller has lived there for years.


The deed deserves careful attention

The deed is the document that transfers the seller’s interest in the property.

Buyers sometimes give it little attention because the purchase agreement and mortgage receive most of the discussion. The deed deserves its own review.

The buyer should understand what interest is being conveyed and who will receive it.

That second question is particularly important.

A person buying a house alone may have a straightforward ownership arrangement. A married couple may have different estate planning concerns. Two unmarried people purchasing together may need to consider what happens if one owner dies or wants to sell.

Parents sometimes purchase property with adult children. Some buyers consider a trust or another ownership arrangement.

Each situation raises different legal questions.

The answer should be based on the buyer’s circumstances rather than a generic preference about how property should be titled.


How you take title can affect your estate

Buying a house creates an asset that may eventually become part of your estate.

The way that asset is owned can affect what happens after death.

Certain forms of ownership can affect whether an interest passes through probate. Other ownership arrangements may require the property to be addressed through the owner’s estate.

This is why the deed and the estate plan should be considered together.

A person might have a carefully prepared will but never review whether the way the person’s property is titled supports the intended estate plan.

That can create problems later.

The purchase of a home is therefore a useful point to review the larger ownership picture.

For a Coral Springs homeowner purchasing a primary residence, that conversation may also involve Florida homestead law.


Florida homestead creates additional estate planning questions

Florida’s homestead laws deserve special attention when the property will be the buyer’s primary residence.

Florida provides significant legal protections for qualifying homestead property. The state also has specific rules concerning what happens to homestead property after the owner’s death.

Florida Statutes Section 732.401 addresses the descent of homestead property when an owner dies. Section 732.4015 places restrictions on the owner’s ability to devise homestead property when certain family members survive the owner.

These rules can affect surviving spouses and children.

For example, when a Florida homeowner dies while survived by a spouse and descendants, the disposition of the homestead may be governed by statutory rules rather than by whatever result the owner assumed a will would produce.

The details depend on the family and ownership circumstances.

That is why homeowners in Coral Springs and Broward County should not assume that a will alone determines what happens to their Florida homestead.


Can a will control who receives your house?

Sometimes. Florida law can limit what a homeowner may accomplish through a will when the property qualifies as homestead.

The owner’s family situation matters.

The ownership structure matters.

The type of property matters.

The timing of transfers can matter as well.

Florida Statutes Section 732.4015 contains specific restrictions concerning the devise of homestead when a spouse or minor child survives the owner. Section 732.401 also establishes rules concerning descent when a Florida resident dies without a valid disposition controlling the property.

This is one reason estate planning should be based on the actual assets a person owns.

A will should not be viewed in isolation from deeds, trusts, beneficiary arrangements, and Florida’s property laws.


Should you put your house in a trust?

A trust can be useful in some estate plans. It is not the right ownership arrangement for every homeowner.

The decision depends on what the owner wants the estate plan to accomplish.

A revocable living trust, for example, may be considered as part of an incapacity and estate administration plan. Other trusts can serve different purposes.

The important question is whether a particular trust arrangement fits the person’s property, family circumstances, and estate planning objectives.

Florida also has specific rules concerning transfers of homestead property into trusts and other lifetime transfers. Florida Statutes Section 732.4017 addresses certain transfers of homestead property and explains circumstances affecting the way the property is treated under the homestead rules.

That makes professional review useful before changing the title to a Florida home.

A homeowner should understand the consequences of the transfer before signing a new deed.


What if the inspection reveals serious damage?

A home inspection and a legal review serve different purposes.

An inspector examines the physical condition of the house. An attorney examines the legal rights and obligations created by the transaction.

Suppose an inspection reveals structural damage.

The buyer may want the seller to make repairs. A buyer may prefer a price reduction. The buyer may want a credit at closing. The buyer may decide that the property is no longer worth purchasing.

The purchase agreement determines which options are available.

An inspection report does not automatically give the buyer a right to cancel the transaction.

The contract may contain deadlines governing inspection objections. It may establish particular procedures for repairs or termination. Missing those deadlines can affect the buyer’s rights.

A lawyer can explain the relevant provisions before the buyer takes action.


What happens when a title search reveals a lien?

A lien does not always mean the buyer has to abandon the transaction.

The first step is understanding what the lien is and whose obligation created it.

A mortgage may need to be satisfied at closing. A judgment may require resolution. A construction lien may involve a contractor or subcontractor. An estate matter may require additional documentation.

The appropriate solution depends on the problem.

This is where title work becomes practical rather than abstract. The buyer needs to know whether the defect can be resolved before closing and whether the title company will insure the buyer’s intended ownership.

A buyer should also understand any exceptions listed in the title commitment.

Accepting an exception without understanding it can leave the buyer with a title issue that was visible before closing.


Florida real estate attorney reviewing a property deed and title documents

Is title insurance enough?

Title insurance provides protection against covered title risks under the terms of the policy.

It does not perform the same function as an attorney representing the buyer.

The Florida Bar explains that a title examination generally precedes issuance of a title insurance policy. A title commitment identifies requirements that must be satisfied before the policy can be issued and lists exceptions to coverage.

Those exceptions deserve attention.

A buyer should know what the policy covers and what it does not cover.

The buyer should also know who represents the buyer.

A closing attorney may be involved in the transaction without representing the buyer personally. The Florida Bar specifically advises consumers to determine who the closing attorney represents.

If you want independent legal advice, ask that question before closing.


When should a Broward County homebuyer consider legal representation?

Some circumstances call for particular caution.

Consider speaking with a Florida real estate attorney when:

  • The purchase contract contains provisions you do not understand.
  • The seller inherited the property.
  • The property has been involved in probate.
  • The title search identifies a lien or judgment.
  • A previous deed appears defective.
  • A divorce affected ownership.
  • You are buying with someone who is not your spouse.
  • You are considering buying the property through a trust or business entity.
  • The house will be a major part of your estate.
  • The inspection reveals serious defects.
  • The seller disputes a repair obligation.
  • The transaction involves seller financing.
  • The property has unusual easements or restrictions.
  • A dispute develops before closing.
  • You are unsure how the property should be titled.

These circumstances are not limited to any particular Broward County neighborhood. They can arise in a Coral Springs purchase just as they can in a transaction elsewhere in South Florida.

The common factor is uncertainty.

A buyer does not need to wait until a dispute reaches court before asking a lawyer to review the transaction.


What should you bring to the attorney?

The purchase contract is the obvious starting point.

If you have not signed it, bring the proposed agreement.

If you have already signed it, bring the complete version along with any amendments.

Other useful documents can include the title commitment, inspection report, seller disclosures, survey, mortgage documents, homeowners association documents, and written communications about repairs.

If the property was inherited, information about the estate can also be important.

If you are purchasing the property as part of an estate plan, bring the relevant estate planning documents.

The attorney also needs to know what you intend to do with the property.

  • Will it be your primary residence?
  • Will you own it alone?
  • Will someone else share ownership?
  • Do you expect to leave the property to your children?
  • Are you considering a trust?

Those answers can change the legal analysis.


What does this have to do with probate?

A house can become one of the largest assets handled by an estate.

When the owner dies, the legal treatment of that property depends on how it was owned and the circumstances surrounding the owner’s death.

Some properties pass through probate. Others may pass through a different legal mechanism. Homestead can create additional rules.

This is why the deed signed at the time of purchase can become relevant years later in an estate administration.

A buyer may be thinking about a mortgage and a move.

An estate planning attorney may also need to think about incapacity, death, family rights, and the eventual transfer of the property.

Both perspectives concern the same asset.

For families in Coral Springs and throughout Broward County, that connection can be particularly useful when a home is expected to remain in the family.


A house can create legal consequences long after closing

The closing date is only one point in the property’s legal history.

The deed remains part of the public record. The mortgage may remain for decades. The property may become subject to homestead protections. Ownership may change through marriage, divorce, death, or another transfer.

The house may eventually become part of a probate estate.

That is why a home purchase can be a useful time to review an estate plan.

If you live in Coral Springs or elsewhere in Broward County, the attorney reviewing your purchase should understand the Florida laws that govern the property and your ownership interest.

The goal is to understand the legal consequences before they become difficult to correct.


Questions to ask before signing a purchase contract

A buyer does not need a law degree to ask useful questions.

Start with these:

Who owns the property now?

  • The answer should be supported by the title records.

Can the seller deliver the title required by the contract?

  • A title examination can identify issues that need attention.

What happens if the inspection reveals a serious problem?

  • The answer should come from the purchase agreement and applicable law.

What happens if financing is delayed or denied?

  • The contract should establish the buyer’s rights in that situation.

Who will own the property after closing?

  • The deed should reflect the intended ownership arrangement.

What happens to the property if one owner dies?

  • That question can bring estate planning into the discussion.

Does the property qualify as homestead?

  • If it will be the buyer’s primary residence, Florida’s homestead laws deserve attention.

Does my estate plan account for this property?

  • If the house will be a significant asset, the answer should be clear.

The right legal question is often a little earlier

Homebuyers usually have plenty of practical questions.

  • How much will the mortgage cost?
  • When can we move in?
  • Did the inspection find anything serious?
  • Are the repairs finished?

Those questions matter.

There is another question worth asking before signing:

Do I understand the legal rights I am acquiring and the obligations I am accepting?

If the answer is uncertain, a Florida real estate attorney can review the transaction before the buyer becomes committed to terms that may be difficult to change.

For buyers in Coral Springs and throughout Broward County, that conversation can also include estate planning and probate considerations when the property is expected to remain a significant family asset.

A home purchase creates ownership.

The way that ownership is established can matter for years afterward.


Real estate attorney reviewing closing documents with a Broward County homebuyer

Frequently Asked Questions

Do I need a real estate attorney to buy a house in Florida?

  • Florida does not require every residential buyer to hire a lawyer. The Florida Bar recommends that prospective buyers consult an experienced Florida licensed real estate attorney before signing a purchase contract. Legal advice can be particularly useful when the transaction involves title questions, unusual contract terms, probate, ownership concerns, or estate planning.

What does a real estate attorney check when buying a house?

  • A real estate attorney can review the purchase contract, examine title records, review the deed and closing documents, identify liens or other title problems, advise on ownership, and address disputes that arise before closing.

Should I hire an attorney before signing a purchase contract?

  • If you want legal advice about the agreement, reviewing it before signing gives the attorney an opportunity to identify provisions that could affect your rights. The Florida Bar specifically recommends consulting a Florida real estate lawyer before signing a purchase contract.

Can buying a house affect my estate plan?

  • Yes. The way a home is owned can affect what happens to the property during incapacity and after death. Florida also has special rules concerning homestead property.

Does a will determine who receives my Florida home?

  • A will may control some aspects of an estate, but Florida homestead law can restrict how a homestead property may be devised when a surviving spouse or minor child is involved. The ownership structure and family circumstances need to be considered.

Can a house become part of probate?

  • Yes. Real estate can become part of a probate estate when its owner dies, depending on the ownership structure and circumstances. Property that belonged to a deceased owner may therefore require probate administration before it can be transferred or sold.

Is a title search the same as a home inspection?

  • No. A home inspection examines the physical condition of the property. A title examination investigates ownership and recorded interests affecting the property.

Does title insurance replace a real estate attorney?

  • No. Title insurance protects against covered risks under the policy. An attorney can provide legal advice about the contract, title, ownership, closing documents, and other legal issues affecting the buyer.

Should I discuss estate planning when buying a house?

  • It can be useful when the property will be a significant asset or when the buyer has specific plans for its future ownership. The purchase may be a good opportunity to review the relationship between the new property, the deed, and the existing estate plan.

Can I put my Florida home into a trust?

  • A Florida homeowner may be able to transfer a home into a trust, but the consequences depend on the type of trust, the property, the owner’s circumstances, and Florida homestead law. Legal advice should be obtained before changing the title.

Talk with an attorney before signing

A home purchase can involve questions about contracts, title, ownership, homestead, probate, and estate planning.

If you are buying a home in Coral Springs or elsewhere in Broward County and have questions about the legal side of the transaction, My Personal Attorneys can review your circumstances and explain the issues that may affect your property.

The earlier those questions are addressed, the more options a buyer usually has.

Understanding the Florida Probate Process: What Happens After Someone Dies?

Florida probate process documents and estate administration materials on a legal desk

When someone dies, their family may need to go through probate before certain assets can be transferred to the people entitled to receive them. Probate is a court supervised process used to identify and gather probate assets, address valid debts and creditor claims, and distribute the remaining property according to the will or Florida law.

For families in Coral Springs, Broward County, and throughout South Florida, the process can raise practical questions quickly. Which assets have to go through probate? Who handles the estate? How are creditors paid? How long does the process take? And does every estate requi3re the same type of probate administration?

The answers depend on the assets involved, the existence and terms of a will, the value of the estate, creditor issues, and other circumstances.


What Is Probate in Florida?

Probate is a legal process for administering a deceased person’s probate estate. Florida courts describe probate as a court supervised process for identifying and gathering assets, paying debts, and distributing assets to beneficiaries. Probate generally applies only to probate assets, rather than everything the deceased person owned.

A probate asset may include a bank or investment account held solely in the deceased person’s name, or certain real property owned individually by the deceased. Assets with a valid mechanism for passing automatically to another person may not need to be administered through probate.

This distinction matters because a person’s total property does not necessarily equal the property that must be handled through a probate proceeding.


What Are the Steps in the Florida Probate Process?

Although every estate is different, a probate administration commonly involves several stages.

1. The probate case is opened

The proceeding is generally filed with the clerk of the circuit court in the appropriate Florida county. Venue is ordinarily based on the deceased person’s domicile at the time of death.

The documents required at the beginning of the case depend on the circumstances, including whether the deceased person left a will and which type of administration is appropriate.

2. The will is submitted to the court, if there is one

If the deceased left a will, it must be presented to the probate court and admitted according to Florida law.

A will does not, by itself, transfer every asset immediately to the people named in it. Probate may still be necessary to establish the authority to administer probate assets and complete the estate administration.

If there is no valid will governing the property, Florida’s intestacy laws determine who is entitled to inherit.

3. A personal representative is appointed

Florida generally uses the term personal representative for the person appointed to administer a probate estate.

The personal representative’s responsibilities can include identifying estate assets, dealing with creditors, protecting estate property, paying authorized expenses and obligations, and eventually distributing assets to the appropriate beneficiaries or heirs.

The personal representative is a fiduciary. Florida law requires that person to administer and distribute the estate consistently with the will and the law and to act in the best interests of the estate and interested persons.

The person nominated in a will may have priority for appointment, although the court must still apply Florida’s statutory requirements concerning who may serve.

4. The estate’s assets are identified and gathered

The personal representative must determine what property belongs to the probate estate and take the steps necessary to administer those assets.

This can involve locating financial accounts, real property, personal property, business interests, or other assets. It can also require determining whether particular assets pass outside probate because of joint ownership, beneficiary designations, trusts, or other arrangements.

This is one reason a probate case cannot always be understood simply by looking at the deceased person’s will.

5. Creditors are given an opportunity to file claims

An estate may have outstanding debts when someone dies. Florida law provides procedures for notifying creditors and establishing deadlines for claims against the estate.

A creditor’s claim generally must be filed within the applicable statutory period. Under Florida Statutes section 733.702, many claims must be filed no later than the later of three months after the first publication of the notice to creditors or 30 days after service of the notice on a creditor who is required to receive it. Untimely claims can be barred, subject to limited statutory exceptions.

The personal representative may also have to evaluate and respond to claims filed against the estate. A disputed claim can create additional proceedings and delay the administration.

6. Valid expenses and obligations are paid

Not every debt or expense is treated identically.

Florida law establishes an order of priority for paying expenses and obligations of an estate. Administration expenses, certain funeral expenses, specified taxes and debts, certain medical expenses, family allowances, and other obligations fall into statutory classes.

This means that simply finding a debt does not necessarily answer the question of whether, when, or how it will be paid.

7. Remaining assets are distributed

After the estate’s obligations have been addressed and the requirements for distribution have been satisfied, the remaining probate assets can be distributed to the beneficiaries named in the will or to the heirs entitled to receive property under Florida’s intestacy laws.

The personal representative must follow the governing legal documents and Florida law rather than simply distributing property according to informal family agreements.

8. The estate is closed

The final stage involves completing the administration and taking the steps required to close the probate estate.

The timing varies considerably. A straightforward estate with few assets and no disputes can be very different from an estate involving contested claims, difficult-to-value property, creditor disputes, litigation, or disagreements among beneficiaries.


Does Every Florida Estate Go Through the Same Probate Process?

No.

Florida recognizes formal administration and summary administration, along with limited circumstances in which certain personal property can be transferred without a formal administration.

Formal Administration

Formal administration is the more extensive probate procedure. It can involve the appointment of a personal representative, administration of estate assets, creditor procedures, payment of obligations, and distribution of the remaining property.

It is generally used when the circumstances of the estate require a full administration.

Summary Administration

Summary administration is a shorter procedure available when the statutory requirements are met.

Under current Florida law, summary administration may be available when the value of the estate subject to administration, after accounting for property exempt from creditor claims, does not exceed $150,000, or when the deceased person has been dead for more than two years.

The court can enter an order directing distribution of the estate’s assets, but summary administration still involves legal requirements concerning beneficiaries, assets, and creditors.

A smaller estate is therefore not automatically the same thing as an estate that requires no probate.


Documents representing the steps of probate administration in Florida

How Long Does Probate Take in Florida?

There is no single timeline that applies to every Florida probate case.

The length of an estate administration can depend on:

  • The type of probate administration
  • The number and nature of the estate’s assets
  • Whether real estate must be transferred or sold
  • Whether creditors file claims
  • Whether a claim is disputed
  • Whether beneficiaries disagree
  • Whether litigation becomes necessary
  • Whether assets are difficult to locate or value
  • Whether tax or other financial issues require additional work

Creditor procedures can also create important timing requirements. For example, Florida law establishes specific periods for filing and objecting to creditor claims and provides rules governing when certain claims may be paid.

For that reason, estimates based solely on the size of an estate can be misleading.


What Happens If Family Members Disagree During Probate?

Probate does not automatically prevent disputes between beneficiaries, heirs, creditors, or the personal representative.

Disagreements can involve the validity or interpretation of a will, the identification or valuation of assets, creditor claims, the conduct of the personal representative, or the proposed distribution of estate property.

Some issues can be resolved without extended litigation. Others require court intervention.

The personal representative has fiduciary duties during administration, and Florida law provides procedures for addressing problems involving the administration of an estate.


Does Having a Will Avoid Probate in Florida?

Not necessarily.

A will tells the court how the deceased person wants certain property distributed, but having a will does not automatically eliminate the need for probate.

Whether an asset passes through probate depends on how that asset is owned and whether another legal mechanism controls its transfer at death.

This is why estate planning and probate are related but distinct subjects. A person can have a carefully prepared will and still have a probate estate requiring court administration.


Probate attorney workspace serving Coral Springs and Broward County families

When Should You Speak With a Probate Attorney?

Professional advice can be particularly important when an estate includes significant assets, real property, creditor issues, business interests, disputed claims, beneficiary disagreements, or questions about the personal representative’s conduct.

The right approach also depends on whether the estate qualifies for summary administration or requires formal administration.

For families in Coral Springs, Broward County, and South Florida, understanding the type of estate involved is often the first step toward understanding what the probate process will actually require.


Frequently Asked Questions About the Florida Probate Process

What is the first step in probate in Florida?

  • The first step depends on the circumstances of the estate, but probate generally begins with filing the appropriate documents with the circuit court in the proper county. If there is a will, it is submitted to the court as part of the probate process.

How long does probate take in Florida?

  • There is no fixed timeline for every estate. The length depends on the type of administration, the assets involved, creditor issues, disputes, and other circumstances.

What is the difference between formal and summary probate in Florida?

  • Formal administration is the more extensive probate procedure. Summary administration is a shorter procedure available when statutory requirements are satisfied, including the current $150,000 estate value threshold or the alternative two year period after death.

Does every asset have to go through probate?

  • No. Probate generally applies to probate assets. Certain jointly owned assets, beneficiary designated accounts, and other property may pass outside probate depending on how they are structured.

What does a personal representative do?

  • A personal representative administers the estate. Duties can include gathering assets, dealing with creditor claims, paying authorized expenses and obligations, and distributing property according to the will and Florida law. The personal representative also has fiduciary duties to the estate and interested persons.

Can probate become a lawsuit?

  • Yes. Probate is a court proceeding, and disputes concerning wills, assets, creditor claims, beneficiaries, or estate administration can require litigation or other contested proceedings.

Can a Florida estate avoid formal probate?

  • Sometimes. Florida law provides summary administration for qualifying estates and limited procedures for disposing of certain personal property without administration. Whether one of these alternatives applies depends on the specific facts of the estate.

Probate Guidance for Families in Coral Springs and Broward County

Probate is not one identical process for every Florida family. The appropriate procedure depends on the person’s assets, debts, estate planning documents, beneficiaries, and other circumstances.

If you are dealing with an estate in Coral Springs, Broward County, or elsewhere in South Florida, a probate attorney can review the circumstances and explain which type of administration may apply and what steps are likely to follow.

How Do the Pieces of an Estate Plan Work Together?

Infographic illustrating how wills, trusts, and asset titles integrate into a unified estate planning system

Direct Answer:

An estate plan under Florida law is not a single isolated document, but an interlocking system of distinct legal instruments.

To function effectively, it coordinates asset titling (how property is owned), contractual beneficiary designations (such as life insurance and retirement accounts that bypass probate), revocable living trusts (for private asset management), and a Last Will and Testament (which acts as an administrative backstop for stray assets and nominates guardians for minor children under the 17th Judicial Circuit probate framework).


Direct Transfer Instruments Beneficiary designations and trusts that bypass probate to route funds directly to intended recipients.
The Backstop Administration Wills and probate courts acting as the administrative safety net for any leftover or stray assets.

A common misconception among clients entering an attorney’s office is that estate planning is merely a shopping exercise. People assume they need to choose between buying a will or setting up a trust. As if these documents were competing consumer products on a shelf.

In practice, a durable estate plan functions less like a single document and more like an interlocking machine. Each piece: whether it is a deed, a beneficiary designation, a trust agreement, or a last will and testament – answers a different legal question about your property, your care, and your family’s future security under Florida law.


Asset Ownership Sets the Foundation

Every legal instrument relies entirely on the underlying registration of your property.

The name on a title holds more legal authority over where property goes than almost any standard clause you can write down. Consider how differently law treats various holdings. A commercial storefront in Coral Springs tied to a corporate entity, a family home structured with survivorship rights, or an ordinary checking account carrying no payable on death instructions. Each follows its own strict statutory track.

Property registration and testamentary instruments point in opposite directions. The title or contractual beneficiary designation almost always supersedes your written documents. For instance, naming a child in a will has no legal effect on a bank account where a different individual is listed as the sole payable on death recipient. A thorough planning process evaluates these existing ownership titles first. Therefore ensuring that deeds, corporate shares, and financial accounts are adjusted or harmonized before any wills or trusts are finalized.


Different Assets Can Follow Different Paths

When an individual passes away, their property does not automatically flow down one universal river. Different asset classes utilize entirely distinct legal conduits:

  • Contractual Transfers: Life insurance policies, retirement accounts, and payable on death bank accounts bypass both wills and trusts entirely. Thus transferring directly to named beneficiaries by operation of contract law.
  • Trust Administration: Assets properly titled in the name of a revocable living trust flow privately through trustee administration without judicial interference.
  • Probate Administration: Assets left solely in an individual name with no beneficiary designation must be processed through the probate court system.

Understanding that these pathways operate simultaneously is the key to grasping how an estate plan actually functions.


The Operational Reality of Financial Accounts and Institutional Payables

A common blind spot in estate planning is assuming that legal documents command absolute authority over every dollar an individual owns. In practice, financial institutions, such as major banks operating in Coral Springs and regional credit unions, don’t act like this. They do not look to your will or trust first when an account holder passes away.

Instead, financial operations are strictly governed by internal institutional protocols and direct account contracts. When a bank representative reviews an account after a death certificate is presented, they execute whatever binding agreement is physically attached to that specific account file. If a bank ledger lists an individual payable on death designation, or if a brokerage account registers a transfer on death instruction, institutional compliance departments are legally bound to disburse those funds directly to the named individual, bypassing any instructions found in a trust agreement or a court supervised will.

An integrated estate plan accounts for this operational friction by auditing every institutional account agreement during the drafting phase. Therefore ensuring that corporate paperwork matches your overarching legal strategy before a financial institution ever faces a disbursement decision.


Where the Will Fits Into the Plan

Rather than acting as the absolute ruler of your entire estate, a Last Will and Testament serves a specific structural purpose within the broader system.

Within an integrated plan, a will functions primarily as a legal backstop. It catches stray assets that were never retitled into a trust. Names guardians for minor children. It also nominates the personal representative to manage the probate administration process if court intervention becomes necessary.


Where a Trust Fits Into the Plan

A revocable living trust operates as an alternative operating system for asset management and distribution.

When properly funded during your lifetime, the trust holds legal title to your major property holdings. Instead of directing asset distribution through public probate filings, the trust instrument coordinates private management rules. It establishes exact conditions for beneficiaries, and governs how assets are handled if you experience temporary or permanent incapacity.


What Happens When Probate Enters the Picture?

Probate is often misunderstood as an estate planning document or a failure of foresight. In a well-coordinated plan, probate is simply recognized for what it is: a judicial administration route.

If certain assets remain outside your trust or lack beneficiary designations, the probate court becomes the mandatory administrative mechanism required to clear title and transfer ownership. The goal of comprehensive planning is not always to eliminate every possibility of court involvement, but to ensure that probate handles only what is necessary while private mechanisms handle the bulk of your wealth.


What Happens When the Pieces Do Not Match?

The most critical test of an estate plan occurs when its individual instruments conflict with one another.

Consider a scenario where an individual executes a trust directing that their financial account be divided equally among three children, but the underlying bank account form lists only one child as a payable on death beneficiary. Under Florida law, the contractual beneficiary designation on the account typically overrides the instructions in the trust or will.

When beneficiary designations, trust agreements, and asset titles point in opposing directions, family disputes and unintended disinheritances frequently follow. Coordination prevents these friction points.


Estate Planning Also Covers Incapacity

An estate plan is incomplete if it focuses exclusively on death. A truly integrated system addresses the reality of potential lifetime incapacity.

Through durable powers of attorney and healthcare surrogate designations, your plan designates trusted individuals to manage financial transactions, sign documents, and make medical decisions if you are unable to speak for yourself. These instruments integrate seamlessly with your property management framework, ensuring continuity whether you are navigating daily life or managing a medical crisis in Broward County.


Professional law office building exterior in Coral Springs Florida serving Broward County estate planning clients.

Frequently Asked Questions

Does having a revocable living trust mean my estate will completely avoid probate in Florida?

  • Not automatically. A trust only avoids probate for assets that were properly titled in the name of the trust during your lifetime. Any remaining individually owned assets left outside the trust at the time of death will still require a probate administration unless alternative transfer mechanisms apply.

Can a beneficiary designation override the instructions written in my last will and testament?

  • Yes. Contractual arrangements such as life insurance policies, retirement accounts, and payable on death bank accounts operate independently of a will. The financial institution distributes funds directly to the named beneficiary on file, regardless of what your will states.

Why is asset titling just as important as drafting a will or trust?

  • Asset titling dictates the legal pathway property travels upon death or incapacity. If your legal documents specify one distribution plan but your deeds or account titles are registered under a conflicting ownership structure, the ownership title or beneficiary form frequently overrides your written documents.

How does local court jurisdiction in Broward County affect the administration of an estate plan?

  • When an estate plan requires judicial oversight, such as formal or summary administration through the 17th Judicial Circuit Court in Broward County, local procedural rules govern how property titles are cleared and distributed.
  • An integrated estate plan accounts for these local court requirements ahead of time, minimizing administrative delays for real estate located in Coral Springs, Parkland, or Fort Lauderdale by ensuring property deeds and trust funding are properly structured before probate ever becomes necessary.

What happens if instructions in a revocable living trust contradict a financial account beneficiary form?


Coordinate Your Estate Plan in Broward County

The goal of estate planning is not to accumulate the largest stack of legal documents. It is to ensure that your ownership titles, beneficiary forms, trusts, and wills work together as a unified system to protect your family and assets.

The attorneys at Reinfeld & Cabrera, P.A. assist clients across Coral Springs and Broward County in evaluating their complete asset picture and building cohesive, integrated estate plans.


Schedule a Confidential Consultation

Ensure your legal instruments work together seamlessly under Florida law:

  • Direct Phone: (954) 866-4878 | (954) 334-1520
  • Coral Springs Main Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Website: mypersonalattorneys.com