Quick Answer: The Florida Medicaid 5-Year Lookback Rule allows the Department of Children and Families (DCF) to review all financial transactions and asset transfers made within 60 months prior to applying for Nursing Home Medicaid. Gifting real estate or transferring home ownership below fair market value triggers severe penalty periods of Medicaid ineligibility.
However, homeowners can legally shield their residence from long-term care costs and Medicaid Estate Recovery (MERP) through statutory exceptions—such as the Caregiver Child Exemption, spousal transfers, Medicaid Asset Protection Trusts (MAPTs) created outside the 5-year window, or Lady Bird Deeds that bypass probate without violating lookback rules.
1. How the Florida Medicaid 5-Year Lookback Rule Operates
When an individual applies for Institutional Care Program (ICP) Medicaid in Florida, the state evaluates both income and countable assets. To prevent applicants from gifting away assets to qualify for state benefits, Florida enforces a strict 60-month “lookback” period.
Month 60 to Application Date: The window of scrutiny evaluated by the state.
Uncompensated Asset Transfer: Any transfer of property, cash, or real estate for less than fair market value during this 60-month window.
Penalty Period Enforcement: DCF calculates a period of Medicaid ineligibility based on the total value of the uncompensated transfer.
The Penalty Period Calculation
If the Florida Department of Children and Families (DCF) discovers an uncompensated transfer within the 60 months preceding the application date, DCF imposes a penalty period during which the applicant is disqualified from Medicaid coverage.
During this penalty period, the applicant must pay for nursing home care entirely out-of-pocket—often exceeding $10,000 to $12,000 per month in South Florida facilities—before Medicaid coverage can begin.
Is the Primary Residence a Countable Asset?
In Florida, a primary residence homestead is generally considered an exempt asset for initial Medicaid eligibility if the applicant’s equity interest does not exceed the state’s maximum equity limit and the applicant indicates an “intent to return home” on the application.
However, holding a primary residence as an exempt asset during life does not protect it after death. Without proactive legal structuring, the home remains vulnerable to post-death creditor claims by the state.
2. The Threat of Medicaid Estate Recovery (MERP)
Qualifying for Medicaid during life is only half the battle. Under Fla. Stat. § 409.9101, Florida operates the Medicaid Estate Recovery Program (MERP). Upon the Medicaid recipient’s death, the state becomes a creditor against their probate estate to recoup every dollar paid out for long-term care services.
Property Titled in Deceased’s Name Alone: Passes through formal probate administration, allowing MERP to execute claims and attach liens to force a sale.
Property Structured Outside Probate: Passes directly to designated heirs via deed or trust, completely avoiding probate administration and blocking MERP claims.
If the home passes through formal probate administration, the state can attach a lien to the real estate, forcing heirs to sell the property to satisfy the Medicaid debt. Protecting the family home requires strategies that insulate the residence during the lookback analysis while simultaneously ensuring the home bypasses probate court at death.
3. Statutory Exceptions and Exemption Strategies
Florida Medicaid rules contain explicit statutory safe harbors that permit home transfers within the 5-year window without triggering a penalty period.
Transfer Strategy / Exemption
Lookback Penalty Status
Primary Legal Advantage
Transfer to Surviving Spouse
Fully Exempt
Preserves full ownership for the well spouse (Community Spouse) without penalty.
Caregiver Child Exemption
Fully Exempt
Transfers home title directly to an adult child who provided in-home care.
Transfer to Disabled Child
Fully Exempt
Protects property for a child verified as permanently disabled under SSI/SSDI rules.
Lady Bird Deed (Enhanced Life Estate)
Fully Exempt
Retains lifetime control, avoids probate, and blocks MERP claims.
Medicaid Asset Protection Trust (MAPT)
Subject to 5-Year Lookback
Must be executed >60 months prior to application; provides total asset protection.
The Caregiver Child Exemption
Under Florida Medicaid guidelines, an applicant can transfer full title of the homestead to their adult child without incurring a transfer penalty if specific conditions are met:
The adult child lived in the parent’s primary residence for at least two consecutive years immediately prior to the parent’s admission to a nursing home or long-term care facility.
The child provided documented care that permitted the parent to reside safely at home rather than in a medical care facility during those two years.
The care provided is verified through medical records, physician attestations, and detailed care logs.
Spousal Transfers and Community Spouse Resource Allowance (CSRA)
Transferring the primary residence to a Community Spouse (the spouse who remains living in the community) is completely exempt from the 5-year lookback rule. The well spouse can receive full title to the home without impacting the institutionalized spouse’s Medicaid application.
Lady Bird Deeds (Enhanced Life Estate Deeds)
A Florida Lady Bird Deed allows a property owner to retain an enhanced life estate (including full rights to sell, mortgage, or revoke the deed) while designating remainder beneficiaries who inherit the property automatically at death.
Why it passes lookback scrutiny: Because the owner retains full control to revoke the deed during life, recording a Lady Bird Deed is not classified as a completed uncompensated gift by Florida DCF.
Why it blocks MERP: The property transfers automatically upon death outside of probate administration, effectively shielding the homestead from state estate recovery claims under Fla. Stat. § 409.9101.
4. Real-World Execution Scenarios
Scenario A: Proactive Planning (7 Years Before Long-Term Care Needs)
Profile: A 70-year-old homeowner in Broward County with early-stage health concerns wants to protect her home valued at $500,000 for her two adult children.
Strategy: The homeowner executes a Medicaid Asset Protection Trust (MAPT) and deeds her home into the irrevocable trust.
Outcome: Because the transfer occurred more than 60 months before she ever required nursing care, the 5-year lookback window expires cleanly. The home is completely sheltered from long-term care costs, and she retains the right to live in the home for life.
Scenario B: Emergency Crisis Planning (Immediate Nursing Home Admission)
Profile: An 82-year-old widower suffers a severe stroke and requires immediate, permanent placement in a Coral Springs skilled nursing facility. He has lived with his adult daughter for the past three years, during which she managed his daily medical needs.
Strategy: His legal team gathers medical documentation and physician certifications establishing the Caregiver Child Exemption, while simultaneously executing a Lady Bird Deed as a secondary safeguard.
Outcome: The home is transferred directly to the daughter without triggering a Medicaid penalty period, preserving the home from immediate spend-down and future Medicaid estate recovery.
Frequently Asked Questions
Can Medicaid take my home while I am still alive in Florida?
No. Florida law does not allow Medicaid to place a lien on or seize your primary residence while you are alive, provided your equity remains under the state limit and you state an intent to return home. Threat of home loss occurs after death through the Medicaid Estate Recovery Program (MERP) during probate administration.
Does executing a Lady Bird Deed trigger a 5-year lookback penalty?
No. Because a Florida Lady Bird Deed allows you to retain total unilateral control to sell, refinance, or revoke the conveyance during your lifetime, Florida DCF does not treat it as a completed gift or uncompensated transfer. It does not trigger a Medicaid penalty period.
What evidence is required for the Caregiver Child Exemption in Florida?
Florida DCF requires clear written proof, including:
Proof of joint residency (such as tax returns, driver’s licenses, or utility bills) covering the two years prior to facility admission.
A signed written statement from the treating physician confirming that the care provided by the adult child allowed the parent to remain safely at home instead of entering a nursing facility.
Protect Your Family Home and Assets Before a Crisis Strikes
Navigating Florida Medicaid rules and protecting your real estate from long-term care costs requires proactive, highly technical legal planning. A single misstep with uncompensated asset transfers or failing to structure your property outside of probate can expose your family home to devastating out-of-pocket nursing home expenses and Medicaid Estate Recovery liens.
Do not leave your family’s legacy vulnerable to the uncertainties of the 5-year lookback window. Connect directly with our estate planning and elder law team to build a secure, customized asset protection strategy tailored to your circumstances.
Call Our Office Today: Speak with our team directly at 954-866-4878 to discuss your options.
Under Article X, Section 4 of the Florida Constitution, a primary residence (homestead) is subject to strict constitutional inheritance laws that override standard terms written in a Will or Trust. If a Florida homestead owner dies while survived by a spouse or minor child, state law dictates who receives the home, preventing the owner from freely disinheriting their immediate family.
Direct Answer: When a married Florida homestead owner dies with surviving descendants, Florida Statute § 732.401 gives the surviving spouse two choices: a Life Estate (the right to live in the home for life with a vested remainder to descendants) OR an election to take an undivided 50% ownership share as Tenants in Common. The spouse must file this 50% election within 6 months of the owner’s date of death.
Can You Disinherit a Spouse or Child from a Florida Homestead in Your Will?
Florida’s constitutional restrictions prevent homeowners from leaving their primary residence to outside parties if they have a legal spouse or minor children at the time of death.
If you have minor children: You cannot leave the home entirely to your spouse or anyone else in a Will. Any attempt to do so is legally void under Florida law.
If you have a spouse (and no minor children): You can only leave the home outright to your surviving spouse. Leaving it to a friend, charity, or adult child from a previous marriage without spousal waiver is invalid.
If you have no spouse and no minor children: You are free to leave the property to whomever you choose.
If a Will attempts to convey homestead property in violation of these rules, Florida probate courts treat the gift as an invalid devise. The property automatically passes according to Florida’s statutory rules under Fla. Stat. § 732.401.
Life Estate vs. 50% Election: What Are a Surviving Spouse’s Rights Under Fla. Stat. § 732.401?
When a homestead owner dies survived by a spouse and children (adult or minor), Florida Statute § 732.401 governs how ownership splits between them.
Option 1: Default Life Estate
By default, the surviving spouse receives a Life Estate.
Spouse’s Rights: The right to live in, use, and occupy the residence for the remainder of their lifetime.
Children’s Rights: The decedent’s children receive a vested remainder, automatically assuming 100% ownership after the surviving spouse passes away.
Limitations: The surviving spouse cannot sell, mortgage, or transfer the home without the full consent of all children holding the remainder interest.
Option 2: The 50% Tenant-in-Common Election
To prevent friction between surviving spouses and adult stepchildren, Florida law permits the surviving spouse to opt out of the Life Estate.
Spouse’s Rights: The spouse takes an undivided 50% ownership interest as a Tenant in Common.
Children’s Rights: The decedent’s children collectively share the remaining 50% ownership interest.
Benefits: Either side can file a court action to force a sale (partition action) if both sides cannot agree on maintaining or selling the home.
Comparison Table: Florida Homestead Life Estate vs. 50% Tenant-in-Common Election (Fla. Stat. § 732.401)
Ownership Feature
Option 1: Default Life Estate
Option 2: 50% Tenant-in-Common Election
Spousal Control
Exclusive right to live in property for life
50% legal ownership share
Heir Control
Future ownership after spouse dies
Immediate 50% collective ownership share
Routine Costs (Taxes, Insurance)
Spouse pays 100% of property taxes & maintenance
Split 50/50 between spouse and heirs
Mortgage Principal
Split according to statutory interest formulas
Split 50/50 between spouse and heirs
Forced Sale (Partition)
Cannot be forced by heirs or spouse
Either party can initiate partition to sell property
Strict Deadline
None (automatic default)
6 months from owner’s date of death
Is a Florida Homestead Protected From Estate Creditors After Death?
Beyond inheritance rules, Article X, Section 4(b) of the Florida Constitution provides strong creditor protections that pass directly to heirs.
If the primary home passes to an exempt heir (a surviving spouse, child, sibling, niece, or nephew), the home transfers free and clear of most estate debts. Unsecured creditors; such as credit card companies, medical providers, or personal loan lenders, cannot force the sale of a Florida homestead to satisfy the decedent’s unpaid debts during probate.
(Note: Under Florida’s probate framework, homestead property is entirely excluded when calculating eligibility for summary administration.)
Only three specific debt types can attach to a Florida homestead:
Mortgages signed on the property.
Unpaid real estate property taxes or special assessments.
Mechanics’ and contractors’ liens for work performed directly on the home.
How Do You Establish Legal Homestead Status in Florida Probate Court?
Homestead protections do not apply automatically on paper; they must be formally recognized by a probate judge in the local circuit court (such as the 17th Judicial Circuit in Broward County, 15th Circuit in Palm Beach, or 11th Circuit in Miami-Dade).
File a Petition for Order Determining Homestead Status: A probate attorney files an official petition asking the court to confirm that the property meets constitutional homestead qualifications.
Obtain the Judicial Order: Once signed by the probate judge, the Order Determining Homestead removes the residence from the general probate estate, transfers title to the legal heirs, and shields it from general creditors.
Record the Notice of Election (If Applicable): If taking the 50% Tenant-in-Common election, an official Notice of Election containing the property’s legal description must be signed and recorded in county land records within the strict 6-month statutory window.
Resolving Florida Homestead Disputes and Protecting Estate Rights
Florida’s constitutional homestead protections exist to protect families from displacement and unmanageable creditor claims following a loved one’s passing.
However, the strict constitutional mandates surrounding testamentary freedom, paired with the mandatory 6-month statutory window under Fla. Stat. § 732.401, mean that minor procedural errors can result in forfeited spousal rights, clouded property titles, or unexpected co-ownership disputes between spouses and stepchildren.
Navigating a homestead determination requires swift action in the local probate court to secure clear legal title, enforce statutory elections, and shield the home from unauthorized creditor claims.
Whether you are a surviving spouse evaluating a Life Estate vs. 50% Tenant-in-Common Election, an heir seeking to establish homestead creditor protections, or a personal representative executing an estate, the probate team at Reinfeld Cabrera Tison provides experienced guidance throughout the entire judicial process.
Office Address: 9625 W Sample Rd, Coral Springs, FL 33065
Contact Phone: (954) 866-4878 | 954-866-HURT
Local Probate Venues Served: 17th Judicial Circuit (Broward County Courthouse, Fort Lauderdale), 15th Judicial Circuit (Palm Beach County), 11th Judicial Circuit (Miami-Dade County), and 16th Judicial Circuit (Monroe County).
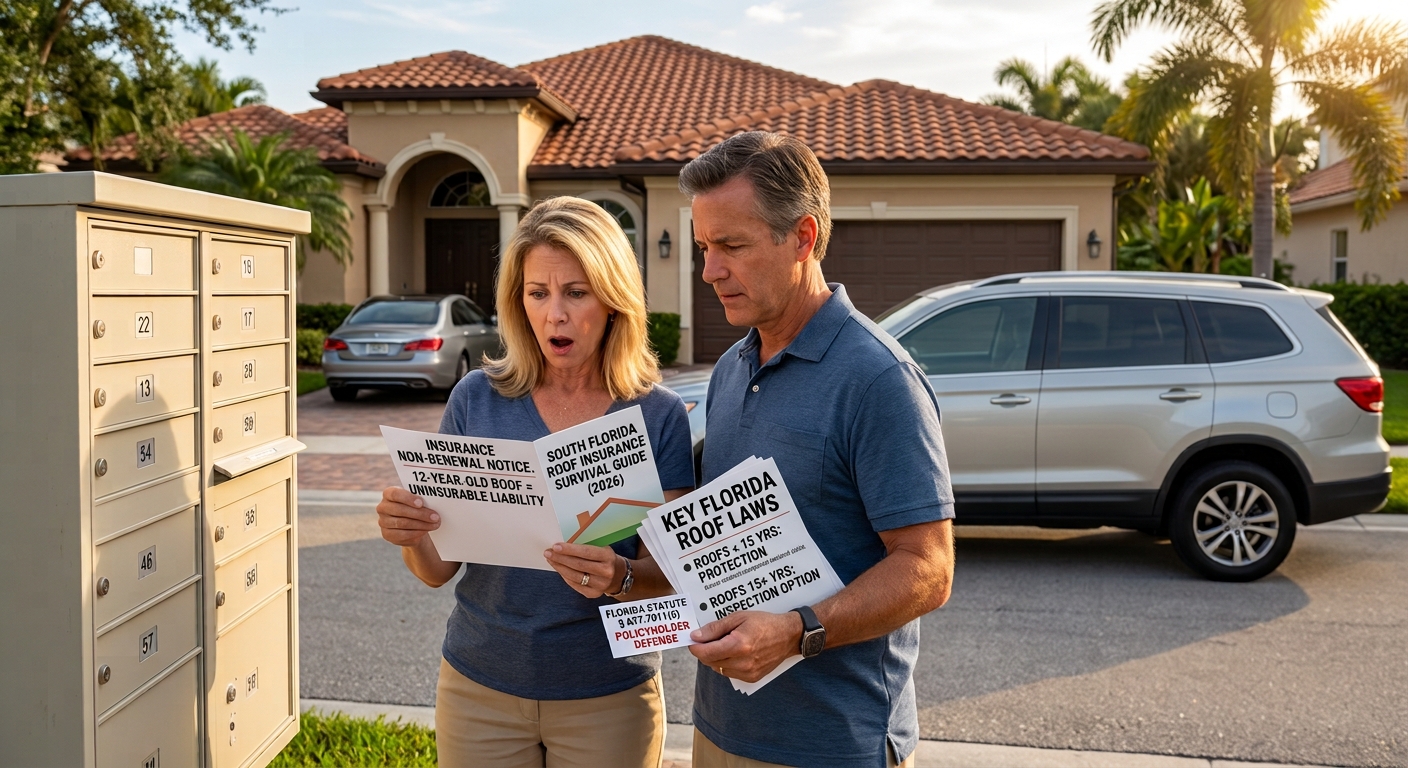
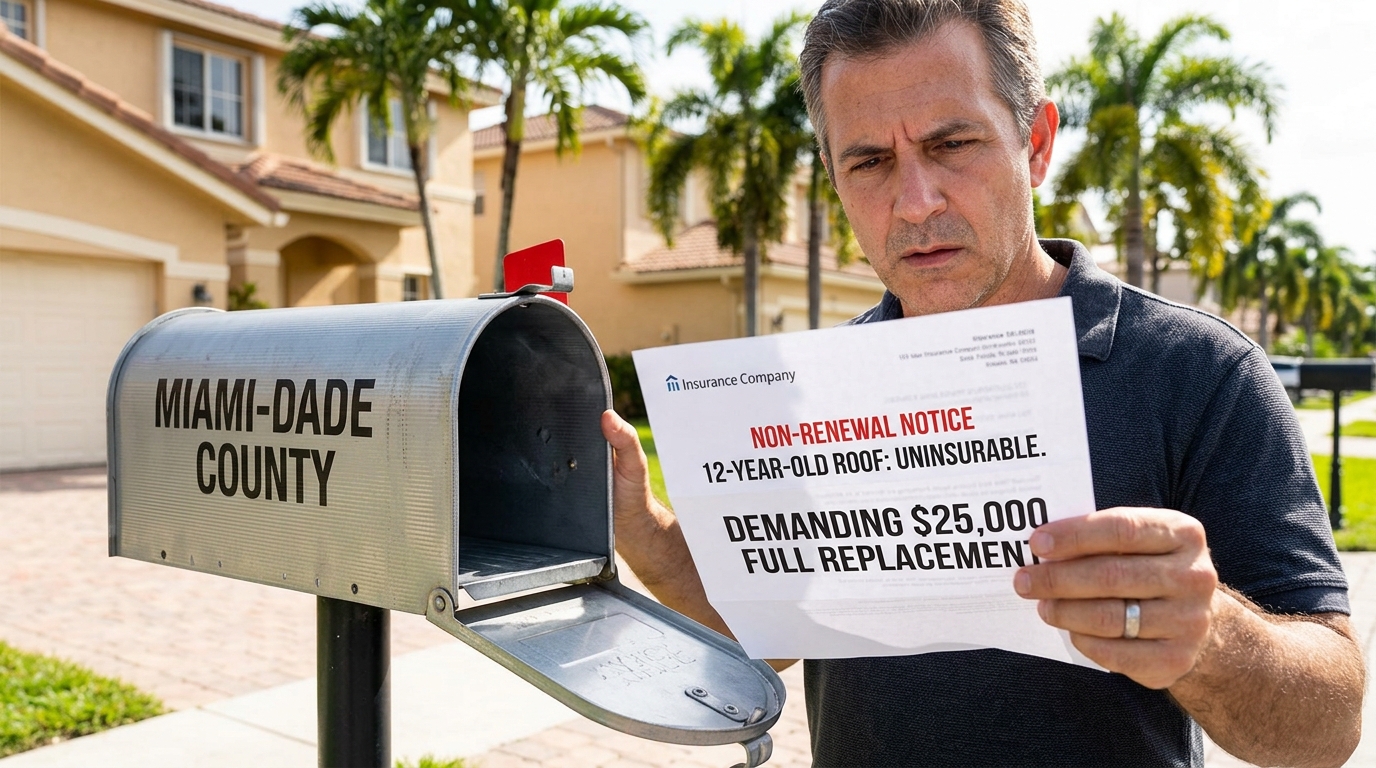
Opening your mailbox in Broward, Miami-Dade, or Palm Beach County often feels like an unpredictable gamble. One afternoon you are enjoying South Florida weather, and the next you are holding a notice from your insurance carrier stating that your 12-year-old roof is suddenly an uninsurable liability—demanding a $25,000 full replacement under threat of immediate non-renewal.
Before panicking or signing a contract with a door-to-door roofer, understand the ground rules. Florida property insurance regulations give homeowners explicit statutory protections that many carriers conveniently omit in their automated non-renewal letters.
Executive Legal Summary: Florida’s Roof Age Laws at a Glance
Roofs Under 15 Years Old: Under Florida Statute § 627.7011(5), property insurance carriers cannot deny coverage or refuse to renew a policy solely based on the age of your roof.
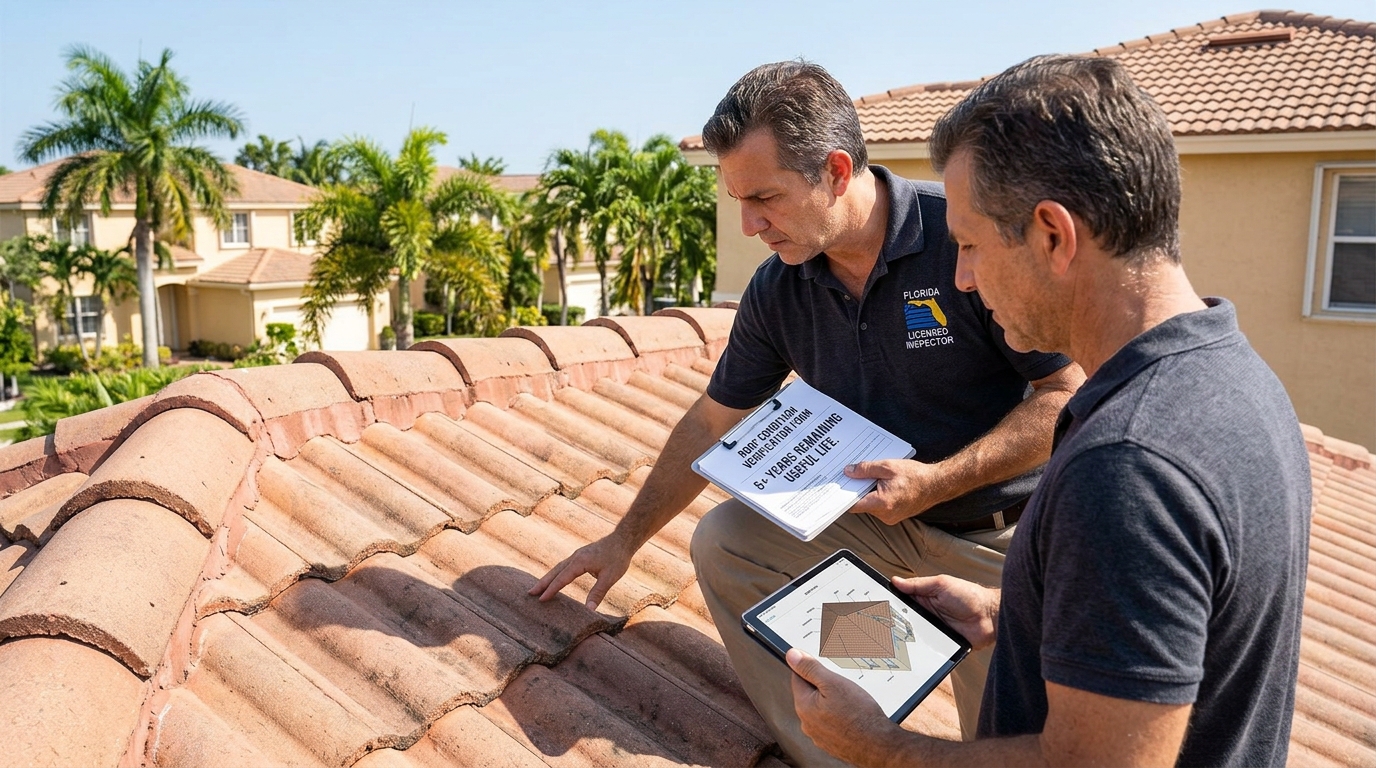
Roofs 15 Years or Older: Insurers can require a roof inspection, but they cannot deny coverage or force a replacement if an authorized inspector certifies that the roof has at least 5 years of remaining useful life.
Authorized Inspector Qualifications: Inspections must be completed by a licensed general contractor, building contractor, residential contractor, professional engineer, professional architect, or certified building code inspector.
Citizens Property Insurance Thresholds: Citizens requires roofs over 25 years old (for shingle) or 50 years old (for tile/metal) to submit a 4-Point or Roof Inspection Form proving 5+ years of useful life.
Many homeowners mistakenly believe that reaching the 10- or 12-year mark on an asphalt shingle roof gives an insurer automatic legal authorization to cancel their policy. That is false.
FLORIDA ROOF AGE STATUTORY TIMELINE
[0 to 14 Years Old] ================================> CANNOT NON-RENEW SOLELY ON AGE
(Fla. Stat. § 627.7011(5))
[15+ Years Old] ================================> INSPECTION REQUIRED
│
├─> 5+ Years Useful Life = COVERAGE MANDATED
└─> <5 Years Useful Life = Replacement/Repair
Protection for Roofs Under 15 Years
Florida Statute § 627.7011(5) explicitly states that an insurance company issuing or renewing a homeowners policy cannot refuse coverage solely because of roof age if the roof surface is less than 15 years old. If your carrier sends a non-renewal notice citing only a 12-year or 14-year roof age, they are violating state insurance guidelines.
The “5-Year Useful Life” Rule for Older Roofs
Once your roof hits or exceeds 15 years of age, the insurer gains the right to demand a professional roof inspection prior to policy renewal. However, the law still protects you: if the inspection proves your roof has at least 5 years of remaining useful life, the insurance company cannot reject your renewal application or force a complete replacement based on age alone.
2. Insurance Company Scare Tactics vs. Florida Statutory Law
Claim Made by Insurance Carrier
Actual Florida Legal & Statutory Standard
Impact on Property Owner
“Your shingle roof is 12 years old, so you must replace it within 30 days to keep your policy.”
Violates Fla. Stat. § 627.7011(5). Insurers cannot drop policies solely for roof age under 15 years.
You do not have to replace a functional 12-year-old roof just because the carrier requests it.
“Your 16-year-old roof failed our satellite image review, so we are non-renewing.”
Insurers must allow you to hire an authorized inspector to perform an in-person evaluation.
Aerial satellite photos cannot override a physical inspection certifying 5+ years of useful life.
“Only our internal adjusters can determine if your roof is acceptable.”
Inspections can be completed by any licensed Florida contractor, engineer, or home inspector.
You have the right to hire your own independent inspector to document your roof’s actual condition.
“You must switch to an Actual Cash Value (ACV) endorsement or face immediate cancellation.”
Policy changes must comply with OIR filings, and insurers must give advance written notice of endorsement alterations.
ACV reduces payouts by factoring in heavy depreciation; understand what rights you give up before signing.
3. RCV vs. ACV: The Hidden Policy Trap
Understanding how your insurance carrier calculates roof damage payouts is essential when navigating renewals and storm damage claims.
Replacement Cost Value (RCV): The insurer covers the actual cost to repair or replace the damaged roof with similar materials at current market prices, without deducting money for age or wear and tear.
Actual Cash Value (ACV): The insurer deducts depreciation based on the age and condition of the roof before issuing a payment.
If a 15-year-old roof with a 20-year lifespan suffers severe storm damage under an ACV policy, the insurer may only pay 25% of the replacement cost, leaving the homeowner responsible for the remaining 75% out-of-pocket. Pay close attention to policy renewal documents—carriers frequently attempt to slip ACV roof endorsements onto older homes during annual renewals.
4. Roof Materials & Expected Insurable Lifespans
The material covering your home dramatically influences underwriting guidelines across private carriers and state-backed insurers like Citizens Property Insurance Corporation.
Asphalt Shingle Roofs: Private carriers scrutinize shingle roofs most heavily starting at year 15. However, high-grade architectural shingles often maintain structural integrity well beyond 15 years if properly maintained.
Tile & Metal Roofs: Concrete tiles, clay tiles, and standing-seam metal roofs regularly handle South Florida wind loads for decades. Citizens Property Insurance allows tile and metal roofs to reach up to 50 years before mandatory age-based useful life documentation is triggered.
5. Step-by-Step Defense Action Plan: Responding to a Non-Renewal Notice
If an insurance company delivers a notice demanding roof replacement or threatening non-renewal in Broward, Miami-Dade, or Palm Beach County, follow this structured response plan:
Check stated reasons Independent 4-Point Provide 5-year cert Enforce statutory
and roof age dates. Roof Inspection. to insurance carrier. rights if denied.
Audit the Non-Renewal Letter: Check the exact reason cited by the carrier. If the only reason listed is that your roof is between 1 and 14 years old, the notice violates Fla. Stat. § 627.7011(5).
Order an Independent Roof Inspection: Contact a licensed Florida general contractor, building inspector, or engineer. Ask specifically for a Florida 4-Point Inspection or Roof Condition Verification Form.
Secure the 5-Year Useful Life Certification: Ensure the inspector documents that the roof has at least 5 years of remaining useful life. This written verification serves as your primary protection under state law.
Submit Formal Documentation via Certified Mail: Send the completed inspection report directly to your insurance agent and carrier. Request formal written confirmation that the non-renewal notice has been rescinded.
Consult Legal Counsel if the Carrier Refuses: If an insurer ignores state statute and refuses to accept a valid 5-year useful life certification, legal intervention may be required to protect your property rights and coverage.
6. Frequently Asked Questions
Can my insurance company drop me if my shingle roof is only 12 years old?
No. Under Florida Statute § 627.7011(5), insurance companies cannot refuse to issue or renew a homeowners insurance policy solely because of roof age if the roof is less than 15 years old.
Who qualifies as an “authorized inspector” in Florida?
Under state law, authorized inspectors include licensed general contractors, building contractors, residential contractors, professional engineers, professional architects, and certified building code inspectors.
What happens if my roof is over 15 years old but in great condition?
If an authorized inspector certifies that your 15+ year old roof has at least 5 years of remaining useful life, Florida law prevents the insurer from denying or non-renewing your coverage solely based on roof age.
Does Citizens Property Insurance follow the same roof rules?
Yes, Citizens Property Insurance must comply with Florida statutory requirements. Citizens requires documentation verifying at least 5 years of remaining useful life for shingle roofs older than 25 years and tile/metal roofs older than 50 years.
Protecting Your Property Rights Across South Florida
When insurance carriers issue arbitrary non-renewal demands, knowing the statutory rules keeps you in control. If your insurance company is threatening improper non-renewal, forcing unnecessary roof replacements, or mishandling a property damage claim, our team can help you enforce your statutory protections.
Disclaimer: The information provided in this guide is for general informational and educational purposes only and does not constitute formal legal advice. Property insurance laws and underwriting rules change frequently. Consult a qualified Florida legal professional regarding your specific situation.
If you believe someone has misused a financial power of attorney in Florida, there are legal ways to challenge what happened. Depending on the circumstances, a court may review the agent’s conduct, require an accounting, remove the agent, terminate the agent’s authority, or order other relief.
Usually, though, nobody starts with a lawsuit.
It starts with a bank statement.
A parent gave a son or daughter power of attorney to handle the bills. An elderly relative needed someone to manage investments. Everything seemed ordinary until a family member noticed a withdrawal that did not make sense.
Then there is another one.
Maybe money went to the agent. Perhaps a house was sold. Maybe someone suddenly has a very good explanation for why several thousand dollars disappeared.
The uncomfortable part is that having power of attorney does give someone real authority. The document may allow an agent to handle bank accounts, investments, real estate, and other financial matters. But that authority comes with legal duties, and the agent has to stay within the authority the principal actually granted.
So what happens when the numbers stop making sense?
The answer usually starts with the power of attorney itself, the agent’s actions, and the financial records showing what happened to the principal’s money.
What Is a Financial Power of Attorney?
A power of attorney allows one person, called the principal, to authorize another person, called the agent, to act on the principal’s behalf.
The authority can be broad or limited. Depending on the document, an agent may be able to handle bank accounts, investments, contracts, real estate, or other financial matters.
Florida law generally limits an agent to the authority actually granted in the power of attorney. A broad statement saying that the agent can perform every act the principal could perform does not automatically create every possible specific power under the statute. Certain powers require separate, signed authorization.
That detail can become extremely important when a family disputes a transaction.
The document itself has to be examined.
What Does Financial Power of Attorney Abuse Look Like?
There is no single transaction that automatically proves abuse.
An agent might legitimately withdraw money to pay the principal’s mortgage. The same type of withdrawal could become a serious problem if the money goes toward the agent’s own mortgage.
Warning signs can include:
Unexplained withdrawals from bank or investment accounts
Transfers to the agent or the agent’s relatives
Personal expenses paid from the principal’s accounts
Property transferred or sold for the agent’s benefit
Large gifts that do not fit the principal’s history or instructions
Financial accounts being changed without a clear explanation
Missing receipts or financial records
Transactions occurring after the power of attorney was revoked
The records matter.
Florida requires an agent to keep records of transactions made on behalf of the principal, and the Florida Bar notes that an agent may be required to provide an accounting.
“A power of attorney gives someone authority to act for another person. It does not give that person ownership of the principal’s money.”
Can a Power of Attorney Agent Take Money From the Principal?
An agent can use the principal’s money when the transaction is authorized and consistent with the agent’s legal duties.
The agent cannot simply treat the principal’s checking account as a second personal account.
Florida law describes the agent as a fiduciary. The agent generally must act loyally for the sole benefit of the principal, avoid conflicts that interfere with impartial decision-making, and exercise the care, competence, and diligence ordinarily expected in similar circumstances.
Consider a simple example.
A daughter has power of attorney for her father. She uses his account to pay his property taxes, medical bills, insurance, and other expenses. Those transactions may be entirely appropriate.
Then she transfers $50,000 to herself and says, “Dad wanted me to have it.”
That raises a very different set of questions.
Was the gift authorized?
Did the power of attorney contain the necessary authority?
Was the transaction consistent with the father’s known wishes?
Did the agent have a conflict of interest?
What records exist?
A court looking at a disputed transaction may need to answer those questions rather than simply deciding whether money changed hands.
Can a Power of Attorney Agent Use the Principal’s Property?
Real estate can create especially complicated disputes.
Florida law allows a power of attorney to grant authority to convey or mortgage homestead property, but the applicable formalities and statutory requirements matter. The Florida Bar likewise explains that an agent may sell a principal’s home when the power of attorney satisfies the applicable requirements and grants the necessary authority.
Suppose an agent sells a property and deposits the proceeds into an account belonging to the principal. That may be an ordinary transaction.
Suppose the proceeds instead end up financing the agent’s own house.
Now the transaction deserves serious scrutiny.
The same problem can arise when an agent uses the principal’s money to purchase property that is titled in the agent’s name.
A Broward County case shows how messy this can become
In Sacco-Martin v. Romano, decided by Florida’s Fourth District Court of Appeal in August 2025, elderly parents had granted powers of attorney to their daughter and her husband in 2019 and 2020. They revoked those powers of attorney in May 2021. A subsequent guardian alleged that the former agents had nevertheless exercised control over the parents’ financial accounts and transferred hundreds of thousands of dollars.
The probate court ordered an accounting covering the period during which the agents had acted under the powers of attorney. It reviewed bank statements and testimony and ultimately ordered the former agents to return substantial funds to the guardianship estate.
The Fourth DCA affirmed most of that ruling. It did, however, reverse one $20,000 portion because the particular transfer occurred before the relevant power of attorney period and therefore fell outside the accounting period established by the probate court.
The case also involved two properties purchased with the parents’ money. One was purchased with more than $562,000 transferred from the parents’ account and titled in the parents’ names. The property was later sold. Another property was purchased around the same time, with questions about whether the parents’ money ultimately funded the purchase and why that property was titled in the former agents’ names.
That is a useful lesson in how these disputes actually develop.
The question may begin with, “Where did the money go?”
It can eventually become a dispute involving bank records, property titles, closing statements, accounting periods, alleged gifts, and the scope of the agent’s authority.
Can a Court Remove a Power of Attorney Agent in Florida?
Yes.
Florida Statutes §709.2116 allows a court to construe or enforce a power of attorney, review an agent’s conduct, terminate the agent’s authority, remove the agent, and grant other appropriate relief.
The statute also identifies people who may petition the court. They include the principal or agent, certain fiduciaries, a person authorized to make health care decisions in specified circumstances, and another interested person who can demonstrate an interest in the principal’s welfare and a good-faith belief that court intervention is necessary.
That can matter when the principal is no longer capable of handling the dispute personally.
It also means that a family disagreement does not automatically give every relative the right to take over the situation. Standing, the principal’s circumstances, the agent’s conduct, and the available evidence all matter.
Can You Force a Power of Attorney Agent to Provide an Accounting?
Potentially, yes.
Financial records are often central to a dispute over an agent’s conduct. Florida law requires an agent to maintain records of receipts, disbursements, and transactions made for the principal. The Florida Bar likewise advises agents to maintain careful records and explains that an agent may be required to provide an accounting.
An accounting can help answer basic but important questions:
What money came into the account?
What money went out?
Who received it?
What was the payment for?
Was the transaction authorized?
Was the principal’s money used for the principal’s benefit?
Sometimes the accounting clears things up.
Sometimes it creates several new questions.
What Evidence Can Help Prove Power of Attorney Abuse?
If you suspect that a financial power of attorney has been misused, preserve the records before they disappear into the digital equivalent of a junk drawer.
Useful evidence can include:
The original power of attorney and any amendments
Bank and investment statements
Canceled checks
Wire transfer records
Deeds
Closing statements
Tax records
Credit card statements
Receipts
Emails and text messages
Communications with banks or financial institutions
Records showing the principal’s usual financial practices
Documents concerning the principal’s estate plan
The power of attorney itself is especially important.
A transaction can look suspicious until the document reveals that the agent had express authority to perform it. The opposite can also happen: a transaction can look ordinary until the document shows that the agent lacked the authority to make it.
What If the Principal Is Still Capable?
If the principal still has the legal capacity to make financial decisions, the situation may be different from one involving a principal who can no longer manage their affairs.
Florida law provides for revocation of a power of attorney, and a principal who remains capable may be able to revoke the existing authority and appoint another agent. The details depend on the circumstances and the document.
When there are already disputed transactions, however, changing the agent may be only one part of the problem.
There may also be questions about money already transferred, property already sold, or records that have not been provided.
What Happens to a Financial Power of Attorney After Death?
A power of attorney generally terminates when the principal dies. Florida’s statute expressly provides that the principal’s death terminates the power of attorney.
That does not erase transactions that happened while the principal was alive.
If family members believe an agent misused the principal’s property before death, those transactions can become relevant to an estate or probate dispute.
The legal framework then shifts. The personal representative or another person with appropriate authority may need to investigate what happened to the deceased person’s assets.
This is one reason a power of attorney dispute can eventually become a probate matter.
How Common Is Financial Exploitation?
Power of attorney abuse sits within a much larger financial exploitation problem.
The Administration for Community Living reported that older Americans lost nearly $2.4 billion to fraud in 2024, up from $1.9 billion in 2023. The agency also cautioned that reported fraud represents only part of the actual harm because many incidents go unreported.
The numbers cover fraud generally, not power of attorney abuse specifically.
But the broader pattern is relevant. Financial exploitation can occur within relationships of trust, including relationships involving family members, caregivers, and other people who have access to an older person’s finances.
A South Florida federal case illustrates how severe one of these situations can become.
In 2025, federal prosecutors sentenced former financier Brett Thomas Graham to seven years in prison after he admitted defrauding an elderly family member of approximately $8.4 million. According to the U.S. Attorney’s Office, Graham later became the woman’s power of attorney and was obligated to act in her best interest while continuing to divert money for his own expenses.
That is an extreme case.
Most power of attorney disputes will not involve $8.4 million, federal wire fraud charges, or a seven-year prison sentence.
The underlying problem can be much smaller and still be devastating to a family.
What Can Families Do About Power of Attorney Abuse?
Start with the document and the records.
Find out what authority the principal actually granted. Identify the transactions that are causing concern. Gather the financial records. Establish when the transactions occurred. Determine whether the power of attorney was still effective.
Then ask the uncomfortable questions.
Was the transaction authorized?
Was it for the principal’s benefit?
Did the agent personally benefit?
Was there a gift?
Was there a conflict of interest?
Can the agent account for the money?
Those questions are far more useful than simply asking whether someone in the family “did something shady.”
And sometimes the records show that the agent acted properly.
That possibility deserves to be taken seriously too.
“Financial disputes between relatives can become emotional very quickly. The documents give everyone something concrete to examine.”
Power of Attorney Disputes in Coral Springs and Broward County
For families in Coral Springs and throughout Broward County, a financial power of attorney dispute may overlap with probate, guardianship, estate litigation, real estate, or financial exploitation proceedings.
Broward County’s Probate and Guardianship Division handles probate and guardianship matters through the Seventeenth Judicial Circuit. The county also provides procedures and resources for matters involving vulnerable adult exploitation, guardianship accountings, probate filings, and related proceedings.
That local connection matters when a dispute moves from a family disagreement into a court proceeding.
A court may be asked to review the agent’s conduct, terminate the agent’s authority, remove the agent, order an accounting, or provide another appropriate remedy under Florida law.
Frequently Asked Questions
What is a financial power of attorney in Florida?
A financial power of attorney allows a principal to authorize an agent to handle specified financial or property matters. The agent’s authority depends on the language of the document and Florida law.
Can a power of attorney agent take money from the principal?
An agent may use the principal’s money when authorized and when acting consistently with the agent’s fiduciary duties. An agent cannot simply treat the principal’s assets as personal property.
How do you prove power of attorney abuse?
Evidence can include the power of attorney itself, bank records, transfers, property records, closing documents, receipts, communications, and other evidence showing what authority the agent had and what the agent actually did.
Could a power of attorney agent be removed in Florida?
Yes. Florida law allows a court to review an agent’s conduct, terminate the agent’s authority, remove the agent, and grant other appropriate relief.
Can a family member challenge a power of attorney agent?
Potentially. Florida law permits certain interested persons to petition the court when they meet the statutory requirements for intervention. A family relationship by itself does not determine whether someone has standing.
Can a power of attorney agent be required to provide an accounting?
An agent has a statutory duty to keep records of receipts, disbursements, and transactions made for the principal, and an accounting may be required in appropriate circumstances.
What happens to a power of attorney after the principal dies?
The power of attorney terminates when the principal dies. Transactions carried out before death can still become relevant to a later probate or estate dispute.
When a Financial Power of Attorney Goes Wrong
A financial power of attorney is built on a simple arrangement: one person gives another person authority to handle matters the principal cannot or does not want to handle personally.
Most of the time, that arrangement exists because someone needs help.
When the relationship breaks down, the family may be left reconstructing months or years of financial decisions while trying to determine who has the legal authority to do something about them.
That is why the document, the financial records, the agent’s conduct, and the principal’s circumstances all need to be examined together.
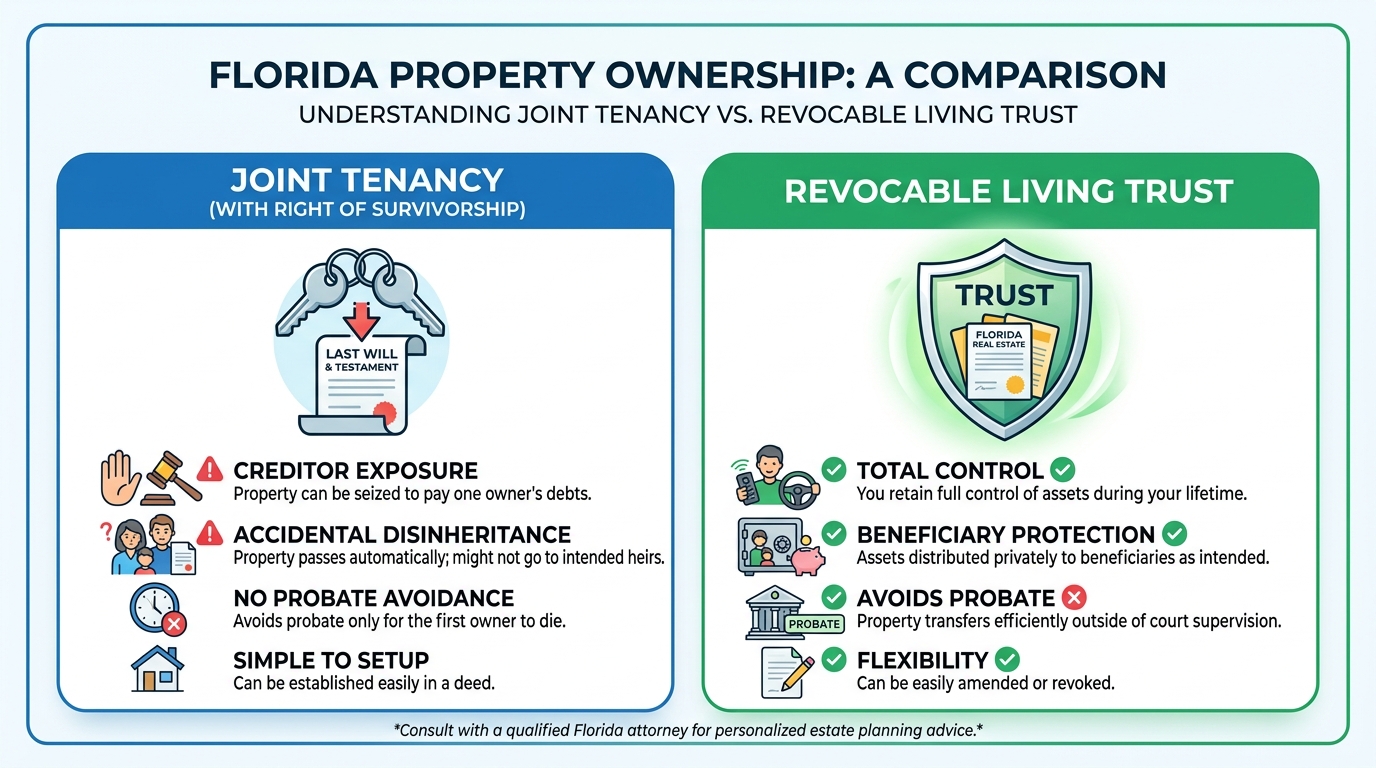
Joint Tenancy with Right of Survivorship (JTWROS) in Florida bypasses probate under Fla. Stat. § 689.15, but it completely overrides your Last Will and Testament. Upon the death of one joint owner, title vests immediately and automatically in the surviving owner. This exposes assets to the survivor’s future creditors, potential remarriage claims, and total disinheritance of biological children from prior marriages.
Governed by Will DirectivesJoint Tenancy completely overrides your Will. A Revocable Trust strictly enforces every distribution instruction in your estate plan.
Co Owner Creditor ProtectionJoint Tenancy exposes your assets to co owner debts and lawsuits. A Revocable Trust protects assets from third party beneficiary liabilities.
Many South Florida homeowners and account holders add adult children, second spouses, or relatives to bank accounts and real estate deeds as a quick shortcut to avoid formal probate court proceedings.
While adding a joint owner appears convenient on the surface, Joint Tenancy with Right of Survivorship (JTWROS) is one of the most unpredictable, blunt force mechanisms in estate planning. Under Florida property and probate law, joint titling strips away your lifetime financial control, exposes your hard earned assets to outside lawsuits, and routinely triggers accidental family disinheritance.
3 Fatal Vulnerabilities of Joint Ownership Under Florida Estate Law
1. Automatic Property Transfer Overrides Your Will and Intentions
Under Florida Statute § 689.15, when property or financial assets are held as joint tenants with right of survivorship, the deceased co owner’s interest transfers instantly to the surviving co owner upon death by operation of law.
Your Last Will and Testament, Revocable Trust instructions, or verbal promises made to family members carry zero legal weight. If a parent adds one adult child to a Coral Springs real estate deed purely for administrative convenience or convenience check writing, that child becomes the sole legal owner upon the parent’s death, completely cutting out their siblings regardless of what the parent’s Will specifies.
2. Immediate Asset Exposure to Co Owner Liabilities and Creditors
The moment you name a joint owner on a bank account or Broward County real estate deed, that individual gains immediate legal ownership rights. If your co owner faces a divorce proceeding, automobile accident lawsuit, business bankruptcy, or personal tax lien, judgment creditors can attach claims directly to your shared asset. You effectively gamble your lifelong financial security on your co owner’s personal financial discipline and legal stability.
3. The Blended Family Disinheritance Trap
In blended families with children from prior relationships, joint titling regularly causes catastrophic estate outcomes.
When a married couple holds real estate or bank accounts jointly with right of survivorship, all assets vest exclusively in the surviving spouse upon the first spouse’s death. When that surviving spouse eventually passes away, the entire estate passes to their personal biological children or designated heirs. The biological children of the spouse who passed away first receive nothing, creating permanent financial alienation between stepfamilies.
Real World Legal Case Study: In re Estate of Kester
A clear example of how joint titling destroys testamentary intent is illustrated in the official Florida legal precedent In re Estate of Kester, Fla. 4th DCA 1986), decided by the Fourth District Court of Appeal in West Palm Beach.
The Case Background
In this landmark dispute, a mother executed a formal Last Will and Testament directing that her entire estate be divided equally among her children. However, for everyday banking convenience, she established joint bank accounts and credit union shares with right of survivorship naming only one of her daughters as a co owner.
The Legal Conflict
Following the mother’s death, the siblings brought legal action in court, arguing that the funds in the joint accounts were intended for the benefit of all children under the terms of the mother’s Will, and that the joint owner held those funds merely as a fiduciary for the estate.
The Court Ruling
The Fourth District Court of Appeal ruled firmly against the other siblings. The appellate court held that under Florida statutory law governing joint accounts, titling an account as joint tenancy with right of survivorship creates a strong legal presumption of an absolute gift to the surviving joint owner.
Because the disappointed siblings could not provide clear and convincing written evidence proving the mother did not intend to create a survivorship right at the exact moment the accounts were established, the surviving joint daughter kept the entirety of the money. The clear instructions contained inside the mother’s Last Will and Testament were completely ignored and legally powerless.
Superior Florida Legal Alternatives to Joint Ownership
Rather than risking loss of control or accidental disinheritance through joint titling shortcuts, comprehensive estate plans utilize flexible legal structures designed under Florida statutory law:
1. Revocable Living Trust
Establishing a trust under Fla. Stat. Chapter 736 allows you to maintain 100 percent sole authority over your real estate and financial accounts during your lifetime. Upon death, your named successor trustee distributes property to your designated beneficiaries according to your exact written terms, achieving complete probate court avoidance without exposing your assets to co owner debts or disinheriting loved ones.
2. Florida Financial Durable Power of Attorney
If your main objective is allowing a trusted child or relative to assist with bill paying, property maintenance, or financial management during a health crisis, executing a Durable Power of Attorney (Fla. Stat. § 709.2104) grants them legal administrative authority without giving them property ownership rights or subjecting your assets to their personal creditors.
3. Enhanced Life Estate Deed (Lady Bird Deed)
For primary residential property in Coral Springs, Fort Lauderdale, or anywhere in Broward County, an Enhanced Life Estate Deed allows a property owner to retain total lifetime ownership rights, including the right to sell, lease, or mortgage the home without obtaining permission, while designating an automatic transfer on death beneficiary that completely bypasses Florida probate.
Frequently Asked Questions
Does joint ownership avoid probate in Broward County?
Yes, joint tenancy with right of survivorship avoids probate upon the death of the first co owner. However, when the surviving owner eventually passes away without establishing formal trust planning, the property must pass through formal Florida probate administration.
Can I remove a joint owner from my Florida real estate deed without their consent?
No. Once an individual is added to a deed as a joint tenant in Florida, you cannot remove them, sell the property, or execute mortgages without their formal notarized signature, even if you originally paid for the entire property yourself.
What is the legal difference between Joint Tenancy and Tenancy by the Entirety in Florida?
Tenancy by the Entirety is a specialized form of joint ownership reserved strictly for legally married couples under Florida law. It provides built in creditor protection against individual spouse liabilities that standard Joint Tenancy does not offer.
Can a Last Will override a joint bank account in Florida?
No. Under Florida law, joint accounts with right of survivorship transfer automatically upon death. A Last Will carries no legal authority to alter or redistribute funds held in a valid joint survivorship account.
Protect Your Property and Family Autonomy in Coral Springs
A Florida guardianship does not automatically take away a person’s gun rights. However, an incapacity adjudication can trigger a separate firearm disability under Florida law, depending on the findings made by the court.
That sounds straightforward until someone actually has to deal with it.
Dad cannot manage his bills anymore. His daughter is considering guardianship. Then somebody remembers the guns.
There is a handgun in the nightstand. Two rifles are in a locked cabinet. Dad insists he is perfectly capable of handling them. His daughter is considerably less convinced.
Now the family has a very different question:
Can Dad still legally own or possess those firearms?
Florida’s guardianship law and firearm law approach that question differently. A guardianship does not automatically erase every legal right an incapacitated person has. At the same time, Florida’s firearm statutes impose restrictions on certain people who have been adjudicated mentally defective, and that definition includes certain judicial findings of incapacity under Florida’s guardianship law.
So the answer may depend on something buried in the court record that the family did not realize mattered.
And that is where things get interesting.
Does Guardianship Automatically Take Away Gun Rights in Florida?
No. Being placed under guardianship does not, by itself, automatically remove a person’s right to own or possess firearms.
Florida’s guardianship statute, §744.3215, lists the rights a person determined incapacitated retains and the rights that a court may remove. The list includes rights involving marriage, voting, driving, contracts, property, health care, residence, and other decisions. Firearm ownership and possession are not listed as rights that §744.3215 specifically gives a guardian authority to remove.
That does not mean an incapacity finding has no effect on firearms.
Florida’s firearm statutes create a separate legal disability. Under §790.065, the statutory definition of a person “adjudicated mentally defective” includes a judicial finding of incapacity under §744.331(6)(a). A person who falls within that definition can be prohibited from purchasing a firearm.
Section 790.064 goes further. A person who has been adjudicated mentally defective, as defined by §790.065, may not own or possess a firearm until relief from the firearm disability is obtained.
So there are two different pieces of law sitting next to each other:
Chapter 744: What rights has the guardianship court removed from the ward?
Chapter 790: Does the person have a separate firearm disability?
The answer to one does not automatically answer the other.
What Does an Incapacity Adjudication Have to Do With Firearms?
This is the part families can easily miss.
A guardianship case begins with a determination of incapacity. Florida law requires the petition to identify the rights the petitioner believes the alleged incapacitated person cannot exercise. The court then determines the nature and scope of the incapacity and the rights affected by its order.
Firearm law uses its own terminology.
Under §790.065, “adjudicated mentally defective” includes certain court determinations involving mental illness, incompetency, conditions, or disease. The statute specifically includes a judicial finding of incapacity under §744.331(6)(a).
That is why the phrase “the person has a guardian” is not enough to determine whether a firearm disability exists.
You have to look at the actual incapacity adjudication and the statutory definition that applies to it.
A limited guardianship involving one set of rights can raise different questions from a broader incapacity adjudication. The court order, the findings supporting it, and the applicable firearm statutes all matter.
What Happens to Guns Someone Already Owns?
Suppose Dad already owns three firearms before the guardianship proceeding.
His daughter becomes his guardian. The guns do not suddenly become the daughter’s property because she was appointed guardian.
But if Dad has been adjudicated mentally defective within the meaning of Florida’s firearm statutes, §790.064 says he may not own or possess a firearm until the firearm disability is removed.
That creates a practical problem the family should not try to solve by improvising.
Someone needs to determine:
What exactly did the court adjudicate?
What rights were removed?
Does the adjudication fall within §790.065?
Is there an existing firearm disability?
Is there a concealed weapons or firearms license?
Does a court order address the firearms?
What legally authorized arrangement should be made for firearms the person already owns?
A guardian does not receive a free-floating power to make every decision for a ward. Florida law limits the rights a guardian may exercise to those removed from the ward and delegated to the guardian.
And if the person is legally prohibited from possessing a firearm, the family should not treat the guns as if this were simply a question of where to put Dad’s property.
Florida Lawyers Were Already Arguing About This in 2013
Then, in February 2014, attorneys Caroline S. A. Zoes and J. Marcos Martinez responded with “Wards and Guns.” Their position was that becoming a ward does not automatically erase constitutional rights.
The exchange is useful today because it identified the exact problem: guardianship law and firearm law were not using the same framework.
Florida’s statutes have since developed firearm-specific restrictions that make the analysis different from the one presented in those 2013 and 2014 articles.
The old debate is still worth reading, though. It explains why the relationship between guardianship, incapacity, and gun rights has never been as simple as “the judge appointed a guardian, so the guns are gone.”
Florida Guardianship Forms Mention Firearms
There is an unusually specific clue in Florida’s guardianship paperwork.
The Florida Supreme Court’s guardianship forms include a question asking whether the respondent may or may not have a license to carry a firearm or possess a weapon or firearm. The form appears in the court’s guardianship rules and forms governing incapacity and guardianship proceedings.
That does not mean the form itself creates a firearm disability.
It does show that firearms are something the guardianship process can require the court to address.
The same form separately identifies the rights that may be delegated to a guardian. Those include contracts, lawsuits, government benefits, property management, residence, health care, and social-environment decisions. Firearm possession does not appear in that list of delegable guardianship rights.
That distinction is worth keeping straight.
Can an Incapacitated Person Still Have a Concealed Weapons License?
Not necessarily. An incapacity-related firearm disability can also affect eligibility for or continued possession of a Florida concealed weapons or firearms license.
Florida’s firearm background-check statute requires the state to consider whether a person has been adjudicated mentally defective or committed to a mental institution. The statute also directs the Department of Law Enforcement to provide relevant information to the Department of Agriculture and Consumer Services when determining eligibility for a concealed weapons or firearms license or whether an existing license should be suspended or revoked.
So a family should not assume that the question ends with the firearms sitting in a gun safe.
There may also be a licensing issue.
Can Someone Regain Gun Rights After an Incapacity Adjudication?
Possibly, but restoration of capacity and restoration of firearm rights are separate legal processes.
Florida law allows a person to seek relief from a firearm disability arising from an adjudication or commitment. Under §790.065, the petition is presented to the appropriate court, the state attorney may object, and the court considers evidence concerning the person’s reputation, mental health record, criminal history when applicable, the circumstances surrounding the firearm disability, and other evidence.
The court must determine that the person is not likely to act in a manner dangerous to public safety and that granting relief would not be contrary to the public interest before granting relief under that statute.
Florida’s guardianship law separately provides a procedure for restoring a ward to capacity when the person can again exercise rights that were previously removed.
Those two procedures should not be treated as interchangeable.
Someone whose capacity has been restored should still determine whether a separate firearm disability remains and whether formal relief under Chapter 790 is required.
What If the Guardian and the Family Disagree About the Guns?
Imagine the Coral Springs family again.
Dad’s daughter is now his guardian. Dad’s son thinks the guns should stay in the house. Dad insists that nothing has changed and wants access to them.
Nobody agrees.
The daughter says, “I’m his guardian.”
The son says, “They’re his guns.”
Dad says, “They’re mine.”
None of those statements, by itself, resolves the legal issue.
The family needs to look at the incapacity order, the guardianship authority actually granted, and the firearm statutes that apply to the adjudication.
If a firearm disability exists under Chapter 790, the possession question becomes very different from a dispute over who owns a piece of ordinary personal property.
And if the family believes the incapacity determination itself should be changed, that is a separate guardianship issue.
This is one of those situations where pulling the actual court file is considerably more useful than arguing around the kitchen table.
What Does This Mean for Families in Coral Springs and Broward County?
For families in Coral Springs and Broward County, guardianship proceedings are handled through Florida’s court system, and the details of the incapacity order can determine what happens next.
A family dealing with an aging parent, dementia, cognitive decline, or another condition affecting decision-making may already be dealing with medical records, financial accounts, powers of attorney, and property issues.
Firearms can add another layer.
If the person owns firearms, the family should identify that issue early in the guardianship process rather than assuming the appointment of a guardian answers it.
The relevant documents may include:
The petition to determine incapacity
The examining committee reports
The order determining incapacity
The order appointing the guardian
Letters of guardianship
Any order addressing firearm possession
Records relating to a firearm or concealed weapons license
Any later order restoring capacity or granting relief from firearm disabilities
The legal analysis is fact specific. A guardianship attorney in Coral Springs or elsewhere in Broward County may need to review the actual orders before giving a definitive answer about a particular person’s firearm rights.
Frequently Asked Questions
Can guardianship take away your gun rights in Florida?
Guardianship alone does not automatically remove gun rights. However, a qualifying incapacity adjudication can trigger a separate firearm disability under Florida’s Chapter 790.
Does an incapacity adjudication prevent someone from buying a gun in Florida?
It can. Florida’s firearm purchase statute includes certain judicial findings of incapacity within the definition of “adjudicated mentally defective,” which can make a person prohibited from purchasing a firearm.
Can an incapacitated person possess a firearm in Florida?
Not if the person is subject to the firearm possession disability in §790.064. That statute prohibits a person covered by its definition from owning or possessing a firearm until relief from the disability is obtained.
Could a guardian take away a ward’s guns?
A guardian does not automatically receive authority over firearms simply because the guardian was appointed. The guardian’s authority depends on the rights removed and powers delegated by the court, while firearm possession may also be governed independently by Chapter 790.
Can someone regain firearm rights after an incapacity adjudication in Florida?
Florida law provides a procedure for seeking relief from a firearm disability. The firearm-relief process is separate from the general procedure for restoring capacity under the guardianship statutes.
Does restoring capacity automatically restore gun rights in Florida?
Do not assume that it does. Restoration of capacity and relief from a firearm disability arise under different statutory procedures. The person’s specific court orders and firearm records should be reviewed.
Can an incapacity adjudication affect a concealed weapons license?
Yes. Florida law directs relevant firearm-disability information to the state agency responsible for determining eligibility for concealed weapons or firearms licenses and for considering suspension or revocation of existing licenses.
Guardianship and Gun Rights in Coral Springs, Broward County, and South Florida
The unusual combination of guardianship and gun rights in Florida creates a legal problem that does not fit neatly into either a standard guardianship checklist or a standard firearm question.
A person can have a guardian without every legal right disappearing. At the same time, a qualifying incapacity adjudication can create a separate firearm disability under Florida law.
For families in Coral Springs, Broward County, and throughout South Florida, the starting point is the actual incapacity order and the firearm statutes that apply to it.
This article provides general information about Florida guardianship and firearm law. It is not legal advice and does not determine whether a particular person may lawfully possess, purchase, or carry a firearm.
Selecting an estate planning and probate attorney in Coral Springs requires evaluating local Broward County courtroom experience, mastery of Florida trust statutes (Fla. Stat. Chapter 736), and integrated knowledge of Florida constitutional homestead laws (Fla. Const. art. X, § 4).
A qualified local attorney ensures wills, revocable trusts, and powers of attorney comply with strict execution requirements while guiding personal representatives through formal or summary probate proceedings in the 17th Judicial Circuit Court of Broward County.
Critical Evaluation Framework for Local Legal Counsel
Florida Statutory Compliance
Fla. Stat. Chapter 736 (Trust Code)
Fla. Stat. Chapter 709 (Durable Power of Attorney)
Fla. Stat. Chapter 765 (Health Care Directives)
Broward Judicial Experience
17th Judicial Circuit Court Rules
Local Broward Clerk Filing Protocols
Probate Division Judicial Orders
Reinfeld & Cabrera Legal Representation Hub
Securing your family’s financial future, protecting physical property, and ensuring seamless asset distribution requires thoughtful legal strategy. While online document assembly services promise cheap, automated legal templates, generic forms regularly fail under Florida probate court scrutiny.
Florida estate law involves intricate statutory execution rules, unique real estate protections, and strict probate filings across Broward County. Understanding how to choose an experienced local attorney is the single most important step in protecting your life savings and preserving your legacy.
5 Essential Standards When Evaluating Coral Springs Estate Legal Counsel
1. Direct Mastery of Florida Specific Estate and Trust Statutes
Florida law does not follow generic federal templates or out of state legal norms. Your legal counsel must maintain a daily transactional practice grounded in specific Florida legislation:
Florida Trust Code (Fla. Stat. Chapter 736): Regulates the creation, amendment, revoking, and administration of revocable and irrevocable trusts. It establishes strict fiduciary standards for named trustees and protects beneficiary distribution rights.
Florida Power of Attorney Act (Fla. Stat. Chapter 709): Governs financial durable powers of attorney. Under Florida law, general sweeping clauses are ineffective unless specific statutory superpowers under Fla. Stat. § 709.2114 are explicitly initialed by the principal.
Florida Probate Code (Fla. Stat. Chapters 731 through 735): Controls the judicial validation of wills, opening of estates, creditor notification periods, and final asset distribution.
Florida Health Care Advance Directives (Fla. Stat. Chapter 765): Outlines the legal appointment of health care surrogates, living wills, and anatomical gifts.
2. Local Courtroom and Judicial Experience in Broward County
Estate planning and probate are deeply localized practice areas. An attorney who regularly represents clients before the 17th Judicial Circuit Court in Fort Lauderdale understands local judicial preferences, divisional filing protocols, and clerk processing workflows.
When a loved one passes away, local judicial experience ensures that petitions for administration, orders appointing personal representatives, and letters of administration move through the Broward County probate court system without administrative rejections or unnecessary delays.
For the vast majority of Coral Springs and Parkland homeowners, primary residential real estate represents their largest asset. Under Florida Constitution Article X, Section 4, primary residential property enjoys unique protection from forced sale by creditors.
However, Florida homestead devise restrictions strictly limit how a primary home can be left in a Will or Trust if the owner is survived by a spouse or minor children. An experienced Coral Springs attorney knows how to structure deeds, trusts, and spousal waivers to preserve homestead protections while avoiding title clouding or unintended tax consequences.
Florida Constitutional Homestead Advantages
Creditor Exemption ProtectionProtects primary residential equity from forced sale by judgment creditors under Florida law.
Property Tax Cap LimitsLocks annual assessed property value increases under Florida Save Our Homes assessment caps.
Strict Devise RestrictionsProtects rights of surviving spouses and minor children regarding real estate transfers.
4. Comprehensive Probate Avoidance and Administration Capabilities
A complete legal counselor does not simply hand you a stack of paper and send you on your way. Your attorney must possess expertise across both proactive planning and reactive administration:
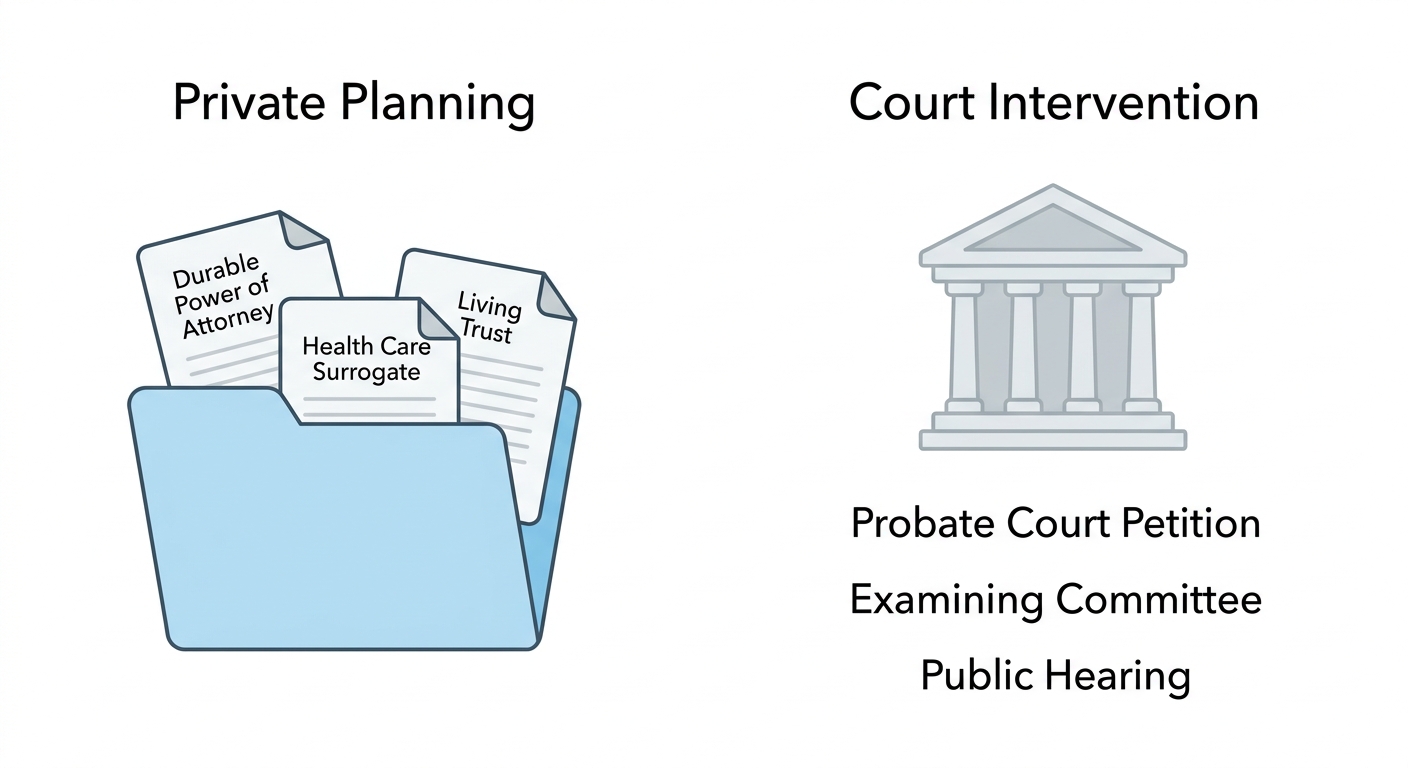
Incapacity Avoidance: Structuring financial durable powers of attorney and health care surrogates to prevent involuntary adult guardianship court hearings under Fla. Stat. Chapter 744.
Summary Probate Administration: Navigating expedited court proceedings under Fla. Stat. Chapter 735 for estates under $75,000 or where the decedent has been deceased for more than two years.
Formal Probate Administration: Managing complex court supervised estates requiring personal representative appointments, formal notice to creditors, estate accounting, and tax releases.
5. Proven Community Reputation and Legal Continuity
Estate planning is an ongoing lifetime relationship. As your family grows, assets change, and Florida tax laws evolve, your estate plan requires periodic reviews.
Recognized over the years by local Coral Springs community awards, Reinfeld & Cabrera, P.A. has established a decade long legacy of personal legal representation across Broward County. Choosing a stable, locally rooted firm ensures that the attorneys who drafted your trust will be available decades later to guide your loved ones through its execution.
Comparing Online DIY Legal Forms vs. Local Attorney Representation
Operational Feature
Online DIY Document Generator
Local Coral Springs Legal Counsel
Florida Execution Compliance
High risk of improper witnessing or notarization
Strict compliance with Fla. Stat. § 732.502
Homestead Protection Integration
Generic forms ignore Florida constitutional restrictions
Customized deed drafting and tax cap protection
Local Probate Court Knowledge
Zero court presence or regional administrative support
Direct filing experience in 17th Judicial Circuit Court
Fiduciary Guidance
No legal advice on selecting agents or trustees
Professional counseling on trustee appointment
Custom Contingency Planning
Rigid templates that fail during complex family changes
Bespoke trust structures adapted to family dynamics
Frequently Asked Questions
Why shouldn’t I use a basic online Will template in Florida?
Florida law requires strict execution formalities under Fla. Stat. § 732.502, including execution in the presence of two signing witnesses and a qualifying notary public. Online templates routinely miss unique Florida requirements, such as statutory power of attorney superpowers or constitutional homestead devise limits, rendering documents invalid or triggering expensive probate disputes.
What is the difference between summary administration and formal probate in Broward County?
Summary administration is an abbreviated court proceeding available if the total value of probate assets subject to administration is $75,000 or less, or if the decedent has been deceased for over two years. Formal administration is required for larger estates and involves appointing a personal representative to marshal assets, clear creditor claims, and manage distributions.
How often should I review my Coral Springs estate plan with an attorney?
You should review your estate plan every three to five years, or immediately following major life events such as marriage, divorce, the birth of a child, purchase of new real estate, significant changes in financial assets, or relocation to Florida from another state.
Can an out of state Will be used in Florida?
A Will executed in another state can be valid in Florida if it strictly met the execution laws of the state where it was signed. However, out of state Wills often name non resident personal representatives who may not qualify under Florida eligibility rules (Fla. Stat. § 733.304) or fail to utilize Florida specific probate shortcuts.
Dedicated Estate Planning and Probate Counsel in Coral Springs
At Reinfeld & Cabrera, P.A., lead attorney Alan J. Reinfeld and our legal team deliver tailored estate planning and probate solutions to South Florida families. We take the time to understand your personal goals, protect your real estate assets, and provide clear legal guidance through every stage of life.
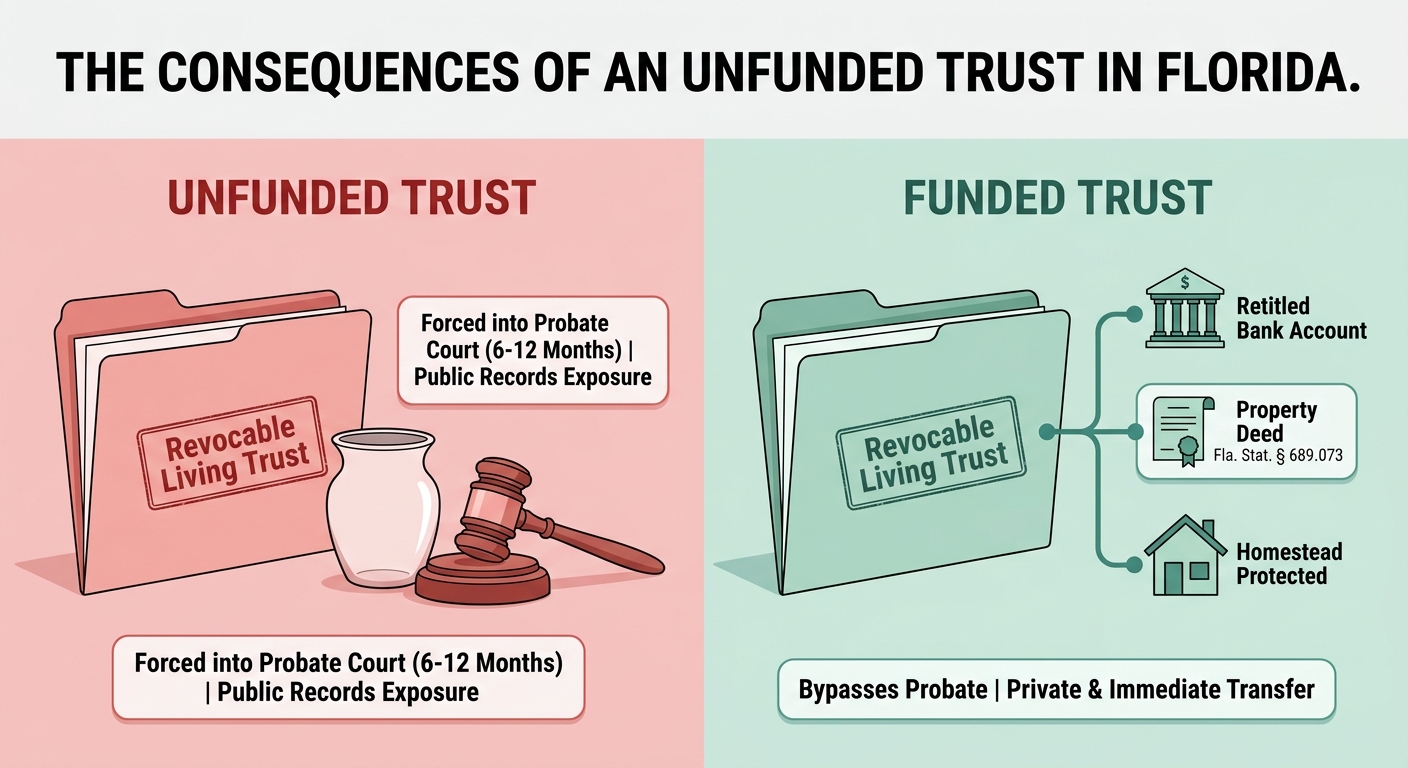
In Florida, a Revocable Living Trust is essentially an empty vessel with written instructions. Signing the trust document creates the legal framework, but if assets are not officially retitled into the name of the trust—a process known as funding—the trust cannot govern or transfer those assets upon your death or incapacity.
Here is an in-depth look at what happens in Florida when a trust remains unfunded, the legal consequences, and how Florida law resolves the gap.
1. The Core Problem: Loss of Probate Avoidance
The primary reason individuals establish revocable living trusts in Florida is to keep their assets out of probate court.
If Funded:Specifically, assets owned by ‘John Doe, as Trustee of the John Doe Revocable Trust’ pass directly to beneficiaries via the successor trustee according to the terms of the trust, bypassing probate court entirely.
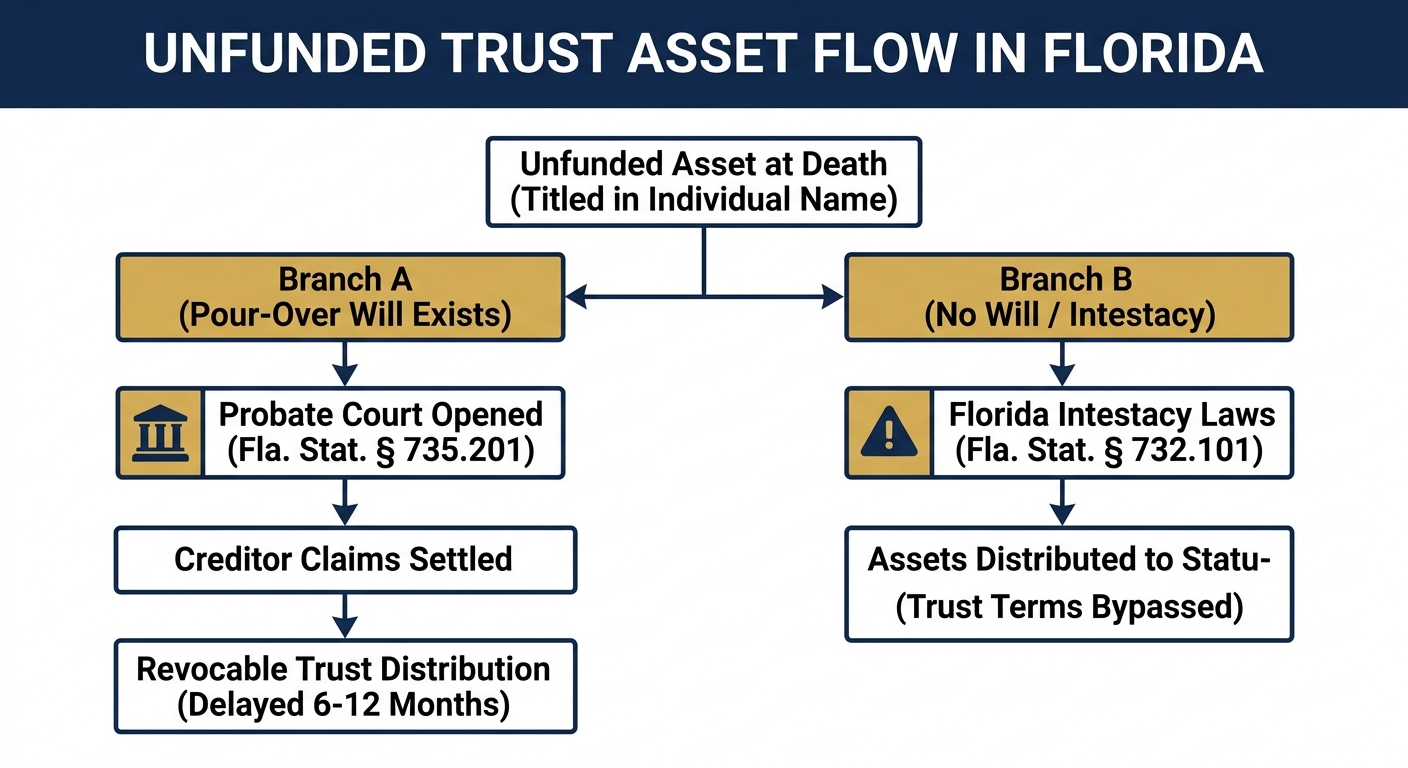
If Unfunded: Any asset that remains in an individual’s personal name at death (e.g., “John Doe”) forms part of the decedent’s probate estate. The trust document holds no legal authority over these individually titled assets.
2. The Legal Safety Net: The Florida “Pour-Over Will”
To protect against unfunded or forgotten assets, a properly executed Florida estate plan includes a Pour-Over Will.
How it works: The Pour-Over Will acts as a catch-all safety net. It states that any asset remaining in the individual’s name at death should be transferred (or “poured over”) into the trust.
The Catch:A Pour-Over Will must go through Florida Probate Court.
The Process:During this process, the court appoints a Personal Representative to collect the unfunded assets, satisfy valid creditor claims under Florida Probate Rules, and then transfer the remaining net assets to the trustee to distribute according to the trust’s instructions.
The Outcome: The wishes outline in the trust are eventually honored, but the estate experiences the exact court delays (6 to 12+ months), public record disclosures, and legal/court costs that the trust was designed to prevent.
3. What Happens If There Is No Pour-Over Will?
If a trust is unfunded and the creator (settlor) dies without executing a Pour-Over Will (or any valid Will):
Intestacy Laws Take Over: The unfunded assets pass according to Florida’s intestate succession laws (Fla. Stat. § 732.101 et seq.), which default to statutory family order (surviving spouse, adult children, parents, siblings).
Accidental Disinheritance:Furthermore, the trust’s provisions, such as leaving equal shares to children, funding charities, or holding money in trust for minors, are bypassed completely for those unfunded assets.
Key Complications Specific to Unfunded Trusts in Florida
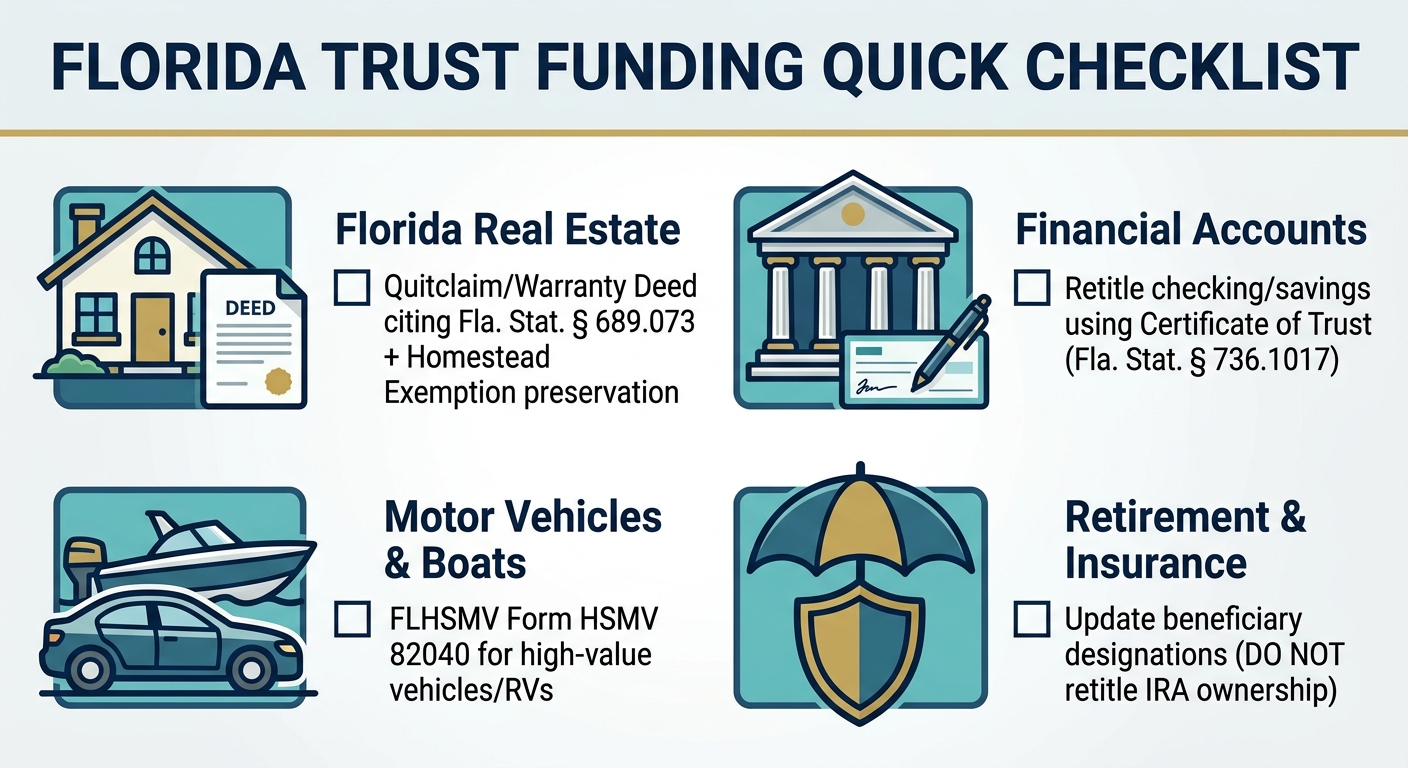
Consequently, if real estate is not deeded to the trust using a properly drafted Quitclaim or Warranty Deed (specifying trust powers under Fla. Stat. § 689.073), the home remains individual property.
Upon death, the homestead therefore requires a court proceeding (a Petition to Determine Homestead) to pass free of claims to legal heirs, regardless of what the trust document outlines.
B. Loss of Incapacity Protection
A key function of a Florida revocable trust is managing assets if the creator becomes incapacitated (e.g., due to dementia or stroke).
Funded Trust: The successor trustee steps in smoothly to manage trust assets without court involvement.
Unfunded Trust: The successor trustee has no authority over individually owned bank accounts or real estate. Family members must instead rely on a Durable Power of Attorney or petition a Florida court for a costly Guardianship proceeding.
C. Exposure of Financial & Personal Privacy
Once probate is opened to catch unfunded assets, the estate inventory, financial balances, names of heirs, and trust references become part of the public court record in the county where the probate is filed.
Summary of Consequences
Scenario
Fully Funded Florida Trust
Unfunded Trust (with Pour-Over Will)
Unfunded Trust (NO Pour-Over Will)
Probate Required?
No (Bypasses court entirely)
Yes (Formal or Summary Administration required)
Yes (Must go through Intestate Probate)
Distribution Time
Immediate or within weeks
6 to 12+ months
6 to 12+ months
Privacy
Private (Kept out of court records)
Public (Will and asset inventories filed with court)
Public (Filed with court)
Who Inherits?
Trust Beneficiaries
Trust Beneficiaries (after probate completion)
Statutory Heirs under Florida Intestacy Laws
How Funding Is Completed in Florida
To fund a trust properly under Florida law:
Real Estate: Draft and record a deed transferring title from the individual to the trust in the county where the property is located.
Financial Accounts: Change account ownership at banks and brokerages to the trust’s name.
Beneficiary Designations: Update primary or contingent beneficiary forms for life insurance policies, retirement accounts (IRAs/401ks), or Pay-on-Death (POD) accounts where appropriate.
Florida Revocable Living Trust Funding Checklist
A Revocable Living Trust cannot avoid probate or manage assets until those assets are retitled into the trust’s name. Follow this streamlined checklist to ensure your trust is properly funded under Florida law.
Essential Prerequisites
Certificate of Trust (Fla. Stat. § 736.1017): Provides banks, brokers, and title companies proof of trustee authority without exposing private beneficiary details.
Standard Trust Titling Format: [Trustee Name(s)], Trustee(s) of the [Trust Name], dated [Execution Date]
Quick-Action Asset Checklist
1. Bank Accounts & Cash Assets
Checking & Savings: Present your Certificate of Trust at your bank to retitle existing accounts or open new trust accounts.
Certificates of Deposit (CDs): Confirm in writing first that the bank will waive early withdrawal penalties for trust transfers before retitling.
Safe Deposit Boxes: Execute a new lease naming the trust or trustee to ensure immediate successor access.
2. Florida Real Estate
Deed Execution: Record a Quitclaim or Special Warranty Deed transferring title to the trustee.
Statutory Protection (Fla. Stat. § 689.073):To be valid under Florida law, the deed must explicitly grant the trustee full power to sell, lease, or encumber property.”
Preserve Homestead Exemptions: Include homestead occupancy rights in the deed/trust to safeguard tax caps (Fla. Admin. Code 12D-7.011) and creditor exemptions (Fla. Const. Art. X, § 4).
3. Motor Vehicles & Vessels (FLHSMV)
Selective Retitling: Under Fla. Stat. § 319.28, Florida allows heirs to transfer simple vehicle titles outside probate. We primarily recommend retitling high-value vehicles, RVs, or boats directly into the trust via FLHSMV Form HSMV 82040.
4. Investment Accounts & Non-Probate Assets
Brokerage Accounts: Submit ownership change forms to custodians (Schwab, Fidelity, Vanguard) along with your Certificate of Trust.
Life Insurance: Assign the trust as the primary or contingent beneficiary to ensure immediate, unencumbered payout administration.
Tax-Deferred Accounts (IRAs/401ks):However, do not retitle ownership, as this triggers immediate tax liabilities. Instead, update beneficiary designations carefully following SECURE Act 2.0 guidelines.
Complete Your Trust Execution with Experienced Counsel
Ensure your real estate, financial accounts, and business assets are properly structured under Florida law. Contact our South Florida estate planning team today:
Direct Telephone: (954) 866-4878 | Toll-Free: 954-866-HURT
Coral Springs Office: 9625 W. Sample Rd, Coral Springs, FL 33065
Fort Lauderdale Office: 2933 W. Cypress Creek Rd, Suite 201, Ft. Lauderdale, FL 33309
Website: mypersonalattorneys.com
Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all surrounding areas of Broward County
Florida does not require every homebuyer to hire an attorney, but legal review can be valuable before signing a purchase contract. A real estate attorney can identify contractual, title, ownership, and closing issues that may affect your rights as a buyer.
For a home purchase in Coral Springs or elsewhere in Broward County, the legal review may involve:
Title: Examining the ownership history and identifying liens, judgments, probate issues, defective deeds, easements, or other recorded interests.
Deed and ownership: Determining how the property will be titled and whether the proposed ownership structure fits the buyer’s circumstances.
Closing: Reviewing documents and addressing unresolved legal issues before ownership transfers.
Florida homestead: Evaluating homestead considerations when the property will be the buyer’s primary residence.
Estate planning: Considering how the new property fits into the buyer’s will, trust, and broader estate plan.
Probate: Identifying potential probate issues when the property was inherited or when its future transfer may involve an estate.
The timing of the legal review matters. A lawyer who examines the transaction before the purchase contract is signed may be able to identify provisions that become difficult to change later. Title and ownership issues should also be addressed before closing, when resolving them can become more complicated.
For buyers in Coral Springs and Broward County, these questions arise under Florida real estate law, but the appropriate legal strategy depends on the specific property, contract, ownership structure, and family circumstances.
When should you hire a real estate attorney?
Many buyers think about hiring a lawyer when they reach the closing table. By that point, the most important contractual decisions may already have been made.
The purchase contract establishes the legal framework for the transaction. It can determine the buyer’s rights concerning financing, inspections, repairs, deposits, title, closing dates, and termination.
The Florida Bar recommends consulting an experienced Florida real estate lawyer before signing a purchase contract. Its consumer guidance explains that important provisions can become difficult to change once the agreement has been signed.
That timing matters whether you are buying a home in Coral Springs, Fort Lauderdale, Parkland, Coconut Creek, or another Broward County community.
Suppose an inspection later reveals substantial roof damage. The buyer may want the seller to make repairs or provide a credit. Whether the buyer can demand either remedy depends on the contract and the circumstances surrounding the transaction.
The same principle applies to financing problems, delays, title defects, and disputes about property condition.
A lawyer who reviews the agreement before signature can explain what the buyer has agreed to and identify provisions that deserve attention.
What does a real estate attorney do for a homebuyer?
The work depends on the transaction.
A real estate attorney may review the purchase agreement, examine title records, review the deed, address liens and judgments, examine closing documents, advise on ownership, and represent the buyer if a dispute develops.
Some transactions require little legal intervention after the contract and title are reviewed. Others become complicated because of the property’s history.
A house in Broward County may have changed hands several times. A previous owner may have died. A divorce may have affected ownership. An old mortgage may remain in the public record. A judgment may have attached to an owner’s interest. A deed may contain an error.
The current seller may have no knowledge of any of these issues.
That does not necessarily prevent the sale. It does mean that the issue should be identified and resolved before the buyer accepts the property.
For a buyer purchasing a home in Coral Springs, the property’s recorded history deserves the same attention as its current condition.
Why title matters when buying a house
A real estate listing tells you who is selling the property. It does not establish the entire legal history of the property.
A title examination looks at recorded documents affecting ownership. Depending on the property, those records may include deeds, mortgages, liens, judgments, probate documents, and other instruments.
Florida law governs the recording of interests in real property. Florida Statutes Section 695.01 addresses the recording of conveyances, mortgages, and other interests in land and explains when recorded instruments have priority against certain creditors and subsequent purchasers.
For a buyer, the practical issue is whether the seller can deliver the ownership interest required by the purchase contract.
Consider a property that has passed through several generations.
The owner listed on the tax record may have inherited the house from a parent. That parent may have inherited it from someone else. At some point, an estate may have been administered incorrectly or a deed may have failed to include someone whose interest mattered.
The problem can remain hidden until the property is sold.
A title examination can reveal that history.
This is particularly relevant in established Broward County neighborhoods, where some properties have changed ownership several times over many years.
What happens when the seller inherited the house?
Inherited property can create title questions that do not appear in an ordinary residential sale.
If the seller acquired the property through an estate, the circumstances surrounding that transfer may need to be examined. The buyer may need documentation showing how ownership passed from the deceased person to the current seller.
Probate can therefore become part of a real estate transaction.
This is one reason real estate law and probate law sometimes meet in the same file.
A buyer does not need to become an expert in probate procedure. The important question is whether the person selling the property has the legal authority to transfer the interest the buyer expects to receive.
If that authority is unclear, the transaction may need additional documentation or court action before closing.
A buyer should not assume that an inherited property has a clean title simply because the seller has lived there for years.
The deed deserves careful attention
The deed is the document that transfers the seller’s interest in the property.
Buyers sometimes give it little attention because the purchase agreement and mortgage receive most of the discussion. The deed deserves its own review.
The buyer should understand what interest is being conveyed and who will receive it.
That second question is particularly important.
A person buying a house alone may have a straightforward ownership arrangement. A married couple may have different estate planning concerns. Two unmarried people purchasing together may need to consider what happens if one owner dies or wants to sell.
Parents sometimes purchase property with adult children. Some buyers consider a trust or another ownership arrangement.
Each situation raises different legal questions.
The answer should be based on the buyer’s circumstances rather than a generic preference about how property should be titled.
How you take title can affect your estate
Buying a house creates an asset that may eventually become part of your estate.
The way that asset is owned can affect what happens after death.
Certain forms of ownership can affect whether an interest passes through probate. Other ownership arrangements may require the property to be addressed through the owner’s estate.
This is why the deed and the estate plan should be considered together.
A person might have a carefully prepared will but never review whether the way the person’s property is titled supports the intended estate plan.
That can create problems later.
The purchase of a home is therefore a useful point to review the larger ownership picture.
For a Coral Springs homeowner purchasing a primary residence, that conversation may also involve Florida homestead law.
Florida’s homestead laws deserve special attention when the property will be the buyer’s primary residence.
Florida provides significant legal protections for qualifying homestead property. The state also has specific rules concerning what happens to homestead property after the owner’s death.
Florida Statutes Section 732.401 addresses the descent of homestead property when an owner dies. Section 732.4015 places restrictions on the owner’s ability to devise homestead property when certain family members survive the owner.
These rules can affect surviving spouses and children.
For example, when a Florida homeowner dies while survived by a spouse and descendants, the disposition of the homestead may be governed by statutory rules rather than by whatever result the owner assumed a will would produce.
The details depend on the family and ownership circumstances.
That is why homeowners in Coral Springs and Broward County should not assume that a will alone determines what happens to their Florida homestead.
Can a will control who receives your house?
Sometimes. Florida law can limit what a homeowner may accomplish through a will when the property qualifies as homestead.
The owner’s family situation matters.
The ownership structure matters.
The type of property matters.
The timing of transfers can matter as well.
Florida Statutes Section 732.4015 contains specific restrictions concerning the devise of homestead when a spouse or minor child survives the owner. Section 732.401 also establishes rules concerning descent when a Florida resident dies without a valid disposition controlling the property.
This is one reason estate planning should be based on the actual assets a person owns.
A will should not be viewed in isolation from deeds, trusts, beneficiary arrangements, and Florida’s property laws.
Should you put your house in a trust?
A trust can be useful in some estate plans. It is not the right ownership arrangement for every homeowner.
The decision depends on what the owner wants the estate plan to accomplish.
A revocable living trust, for example, may be considered as part of an incapacity and estate administration plan. Other trusts can serve different purposes.
The important question is whether a particular trust arrangement fits the person’s property, family circumstances, and estate planning objectives.
Florida also has specific rules concerning transfers of homestead property into trusts and other lifetime transfers. Florida Statutes Section 732.4017 addresses certain transfers of homestead property and explains circumstances affecting the way the property is treated under the homestead rules.
That makes professional review useful before changing the title to a Florida home.
A homeowner should understand the consequences of the transfer before signing a new deed.
What if the inspection reveals serious damage?
A home inspection and a legal review serve different purposes.
An inspector examines the physical condition of the house. An attorney examines the legal rights and obligations created by the transaction.
Suppose an inspection reveals structural damage.
The buyer may want the seller to make repairs. A buyer may prefer a price reduction. The buyer may want a credit at closing. The buyer may decide that the property is no longer worth purchasing.
The purchase agreement determines which options are available.
An inspection report does not automatically give the buyer a right to cancel the transaction.
The contract may contain deadlines governing inspection objections. It may establish particular procedures for repairs or termination. Missing those deadlines can affect the buyer’s rights.
A lawyer can explain the relevant provisions before the buyer takes action.
What happens when a title search reveals a lien?
A lien does not always mean the buyer has to abandon the transaction.
The first step is understanding what the lien is and whose obligation created it.
A mortgage may need to be satisfied at closing. A judgment may require resolution. A construction lien may involve a contractor or subcontractor. An estate matter may require additional documentation.
The appropriate solution depends on the problem.
This is where title work becomes practical rather than abstract. The buyer needs to know whether the defect can be resolved before closing and whether the title company will insure the buyer’s intended ownership.
A buyer should also understand any exceptions listed in the title commitment.
Accepting an exception without understanding it can leave the buyer with a title issue that was visible before closing.
Is title insurance enough?
Title insurance provides protection against covered title risks under the terms of the policy.
It does not perform the same function as an attorney representing the buyer.
The Florida Bar explains that a title examination generally precedes issuance of a title insurance policy. A title commitment identifies requirements that must be satisfied before the policy can be issued and lists exceptions to coverage.
Those exceptions deserve attention.
A buyer should know what the policy covers and what it does not cover.
The buyer should also know who represents the buyer.
A closing attorney may be involved in the transaction without representing the buyer personally. The Florida Bar specifically advises consumers to determine who the closing attorney represents.
If you want independent legal advice, ask that question before closing.
When should a Broward County homebuyer consider legal representation?
Some circumstances call for particular caution.
Consider speaking with a Florida real estate attorney when:
The purchase contract contains provisions you do not understand.
The seller inherited the property.
The property has been involved in probate.
The title search identifies a lien or judgment.
A previous deed appears defective.
A divorce affected ownership.
You are buying with someone who is not your spouse.
You are considering buying the property through a trust or business entity.
The house will be a major part of your estate.
The inspection reveals serious defects.
The seller disputes a repair obligation.
The transaction involves seller financing.
The property has unusual easements or restrictions.
A dispute develops before closing.
You are unsure how the property should be titled.
These circumstances are not limited to any particular Broward County neighborhood. They can arise in a Coral Springs purchase just as they can in a transaction elsewhere in South Florida.
The common factor is uncertainty.
A buyer does not need to wait until a dispute reaches court before asking a lawyer to review the transaction.
What should you bring to the attorney?
The purchase contract is the obvious starting point.
If you have not signed it, bring the proposed agreement.
If you have already signed it, bring the complete version along with any amendments.
Other useful documents can include the title commitment, inspection report, seller disclosures, survey, mortgage documents, homeowners association documents, and written communications about repairs.
If the property was inherited, information about the estate can also be important.
If you are purchasing the property as part of an estate plan, bring the relevant estate planning documents.
The attorney also needs to know what you intend to do with the property.
Will it be your primary residence?
Will you own it alone?
Will someone else share ownership?
Do you expect to leave the property to your children?
Are you considering a trust?
Those answers can change the legal analysis.
What does this have to do with probate?
A house can become one of the largest assets handled by an estate.
When the owner dies, the legal treatment of that property depends on how it was owned and the circumstances surrounding the owner’s death.
Some properties pass through probate. Others may pass through a different legal mechanism. Homestead can create additional rules.
This is why the deed signed at the time of purchase can become relevant years later in an estate administration.
A buyer may be thinking about a mortgage and a move.
An estate planning attorney may also need to think about incapacity, death, family rights, and the eventual transfer of the property.
Both perspectives concern the same asset.
For families in Coral Springs and throughout Broward County, that connection can be particularly useful when a home is expected to remain in the family.
A house can create legal consequences long after closing
The closing date is only one point in the property’s legal history.
The deed remains part of the public record. The mortgage may remain for decades. The property may become subject to homestead protections. Ownership may change through marriage, divorce, death, or another transfer.
The house may eventually become part of a probate estate.
That is why a home purchase can be a useful time to review an estate plan.
If you live in Coral Springs or elsewhere in Broward County, the attorney reviewing your purchase should understand the Florida laws that govern the property and your ownership interest.
The goal is to understand the legal consequences before they become difficult to correct.
Questions to ask before signing a purchase contract
A buyer does not need a law degree to ask useful questions.
Start with these:
Who owns the property now?
The answer should be supported by the title records.
Can the seller deliver the title required by the contract?
A title examination can identify issues that need attention.
What happens if the inspection reveals a serious problem?
The answer should come from the purchase agreement and applicable law.
What happens if financing is delayed or denied?
The contract should establish the buyer’s rights in that situation.
Who will own the property after closing?
The deed should reflect the intended ownership arrangement.
What happens to the property if one owner dies?
That question can bring estate planning into the discussion.
Does the property qualify as homestead?
If it will be the buyer’s primary residence, Florida’s homestead laws deserve attention.
Does my estate plan account for this property?
If the house will be a significant asset, the answer should be clear.
The right legal question is often a little earlier
Homebuyers usually have plenty of practical questions.
How much will the mortgage cost?
When can we move in?
Did the inspection find anything serious?
Are the repairs finished?
Those questions matter.
There is another question worth asking before signing:
Do I understand the legal rights I am acquiring and the obligations I am accepting?
If the answer is uncertain, a Florida real estate attorney can review the transaction before the buyer becomes committed to terms that may be difficult to change.
For buyers in Coral Springs and throughout Broward County, that conversation can also include estate planning and probate considerations when the property is expected to remain a significant family asset.
A home purchase creates ownership.
The way that ownership is established can matter for years afterward.
Frequently Asked Questions
Do I need a real estate attorney to buy a house in Florida?
Florida does not require every residential buyer to hire a lawyer. The Florida Bar recommends that prospective buyers consult an experienced Florida licensed real estate attorney before signing a purchase contract. Legal advice can be particularly useful when the transaction involves title questions, unusual contract terms, probate, ownership concerns, or estate planning.
What does a real estate attorney check when buying a house?
A real estate attorney can review the purchase contract, examine title records, review the deed and closing documents, identify liens or other title problems, advise on ownership, and address disputes that arise before closing.
Should I hire an attorney before signing a purchase contract?
If you want legal advice about the agreement, reviewing it before signing gives the attorney an opportunity to identify provisions that could affect your rights. The Florida Bar specifically recommends consulting a Florida real estate lawyer before signing a purchase contract.
Can buying a house affect my estate plan?
Yes. The way a home is owned can affect what happens to the property during incapacity and after death. Florida also has special rules concerning homestead property.
Does a will determine who receives my Florida home?
A will may control some aspects of an estate, but Florida homestead law can restrict how a homestead property may be devised when a surviving spouse or minor child is involved. The ownership structure and family circumstances need to be considered.
Can a house become part of probate?
Yes. Real estate can become part of a probate estate when its owner dies, depending on the ownership structure and circumstances. Property that belonged to a deceased owner may therefore require probate administration before it can be transferred or sold.
Is a title search the same as a home inspection?
No. A home inspection examines the physical condition of the property. A title examination investigates ownership and recorded interests affecting the property.
Does title insurance replace a real estate attorney?
No. Title insurance protects against covered risks under the policy. An attorney can provide legal advice about the contract, title, ownership, closing documents, and other legal issues affecting the buyer.
Should I discuss estate planning when buying a house?
It can be useful when the property will be a significant asset or when the buyer has specific plans for its future ownership. The purchase may be a good opportunity to review the relationship between the new property, the deed, and the existing estate plan.
Can I put my Florida home into a trust?
A Florida homeowner may be able to transfer a home into a trust, but the consequences depend on the type of trust, the property, the owner’s circumstances, and Florida homestead law. Legal advice should be obtained before changing the title.
Talk with an attorney before signing
A home purchase can involve questions about contracts, title, ownership, homestead, probate, and estate planning.
Estate planning is the process of deciding how your property, financial affairs, and health care decisions should be handled during your lifetime, during periods of incapacity, and after your death.
For families in Coral Springs and throughout Broward County, an estate plan may include a will, revocable trust, durable power of attorney, health care surrogate designation, living will, preneed guardian designation, or other documents depending on the person’s circumstances.
There is no single set of documents that every person needs. The important question is whether the plan addresses the situations that could actually affect you and your family.
What Does an Estate Plan Actually Do?
A basic estate plan addresses two different periods of life.
During your lifetime, it can establish who may manage financial matters or make health care decisions if you become unable to make those decisions yourself.
After your death, it can determine who receives your property, who administers your estate, who manages assets held in trust, and how certain property should be transferred.
Those functions are handled by different documents. A will, for example, does not give someone authority to manage your finances while you are alive. A health care surrogate designation does not determine who inherits your house. A durable power of attorney does not replace a will.
Understanding those distinctions is one of the foundations of effective estate planning.
1. Last Will and Testament
A last will and testament allows you to state how certain property should be distributed after your death and nominate a personal representative to administer your estate.
A will can also address other matters, including the nomination of a guardian for minor children.
But there is an important misconception to avoid:
Having a will does not automatically avoid probate.
A will generally becomes effective through the probate process when it governs probate assets. Property may instead pass outside probate through mechanisms such as joint ownership, beneficiary designations, or a properly funded trust.
Recent Florida litigation illustrates how specific the probate process can become. In Property Solutions Powerhouse, LLC v. Nelson, decided by Florida’s Second District Court of Appeal in 2025, the court addressed a dispute involving a lost will, probate, notice to interested persons, and Florida homestead. The court ultimately upheld the administration and concluded that the decedent, who had no surviving spouse or children, could devise her homestead to the named beneficiary.
The case is a useful reminder that having a will does not mean every question about an estate is automatically settled. The validity of the will, the identity of interested persons, the nature of the property, and Florida’s homestead rules can all matter.
2. Revocable Living Trust
A revocable living trust allows a person to place assets into a trust during life and establish instructions for how those assets should be managed during incapacity and distributed after death.
The person creating the trust can generally retain control while capable and can name a successor trustee to take over management if necessary.
A revocable trust can also help keep properly funded trust assets outside ordinary probate administration. But the trust has to be properly funded. Simply signing a trust agreement does not automatically transfer every asset into it.
The trust is therefore only one part of an estate plan. Its effectiveness depends on how the document is structured, which assets are transferred to it, and how the rest of the estate plan is coordinated.
For a more detailed explanation, see What Is a Revocable Living Trust in Florida?
3. Durable Power of Attorney
A durable power of attorney allows you to authorize another person, called an agent, to act on your behalf within the authority granted by the document.
In Florida, a power of attorney is durable when it contains language showing that the authority continues despite the principal’s subsequent incapacity. Florida law also establishes specific execution requirements, including signing by the principal and two subscribing witnesses and acknowledgment before a notary in the circumstances specified by statute.
The scope of an agent’s authority depends on the powers granted in the document and Florida law.
This is why simply assuming that a spouse or adult child can handle everything for you can create problems. Ownership of a bank account or property does not automatically give another person authority to act on your behalf concerning assets or legal matters that belong to you individually.
A properly prepared power of attorney can be particularly important when someone becomes incapacitated and needs another person to handle financial or legal matters without waiting for a guardianship proceeding.
4. Health Care Surrogate Designation
A health care surrogate designation allows you to name someone to make health care decisions for you if you become unable to make those decisions yourself.
Florida law provides that a designated surrogate may have authority to make health care decisions during the principal’s incapacity, subject to the principal’s instructions and any limitations placed on the surrogate’s authority.
The designation is different from a living will.
A health care surrogate designation identifies who may make health care decisions.
A living will communicates your wishes concerning life prolonging procedures in specified medical circumstances.
Those documents can work together.
Florida law also provides a mechanism for judicial review when an interested person believes, among other things, that a surrogate’s decision conflicts with the patient’s known wishes, that the advance directive is ambiguous, or that the surrogate has abused their authority.
5. Living Will
A Florida living will allows a competent adult to state preferences concerning life prolonging procedures if the person later has a terminal condition, end stage condition, or is in a persistent vegetative state.
Florida law establishes specific execution requirements and provides that a properly executed living will creates a rebuttable presumption of clear and convincing evidence of the person’s wishes.
A living will therefore serves a different purpose from a health care surrogate designation.
The surrogate is the person who may make health care decisions within the authority granted.
The living will communicates your own instructions about life prolonging treatment in the circumstances covered by the document.
6. Preneed Guardian Designation
Florida law also allows a competent adult to name a preferred guardian in advance.
A preneed guardian designation is a written declaration naming the person the individual wants to serve as guardian if a court later determines that the individual is incapacitated. Florida law requires the declaration to be signed in the presence of at least two witnesses. If an incapacity proceeding is later filed, the declaration creates a rebuttable presumption that the designated person should serve, although the court is not required to appoint someone who is unqualified.
The distinction is important: a preneed guardian designation does not eliminate the possibility of a guardianship proceeding. Instead, it allows the individual to express a preference before incapacity occurs.
When Estate Planning Documents Have to Work Together
Estate planning documents are most useful when they form a coordinated plan rather than a collection of unrelated forms.
For example:
A will can address probate assets and nominate a personal representative.
A revocable trust can govern assets properly transferred to the trust.
A durable power of attorney can authorize an agent to handle financial and legal matters during incapacity.
A health care surrogate designation can identify someone to make health care decisions.
A living will can communicate wishes concerning life prolonging procedures.
A preneed guardian designation can identify a preferred guardian if a guardianship proceeding becomes necessary.
The documents can also interact with beneficiary designations, jointly owned property, retirement accounts, insurance policies, business interests, and real estate.
That is why changing one document without reviewing the rest of the plan can create unintended results.
A Florida Case Shows Why Advance Planning Matters
A recent Florida appellate decision provides an unusually clear example of how these documents can operate together.
InFrank v. Frank, decided by Florida’s Fourth District Court of Appeal in 2026, a woman had executed a durable power of attorney, health care surrogate designation, trust, and will before a guardianship dispute arose. The documents named her daughter, Alicia, to manage her affairs and established her intentions concerning the family home and estate.
The trial court later appointed a different person despite those prior designations. The Fourth District Court of Appeal reversed because the lower court had failed to make the specific findings required to overcome the statutory presumption supporting the woman’s previously expressed choice. The appellate court emphasized that the record showed she had repeatedly confirmed her estate planning decisions before the guardianship dispute.
The case does not mean that a person’s chosen agent or guardian can never be replaced. It demonstrates something more practical: advance planning can provide evidence of a person’s wishes before a family dispute reaches court.
An older Florida Fourth District case, Martinez v. The Guardianship of J. Alan Smith, similarly involved a person who had executed a health care surrogate designation, preneed guardian designation, and durable power of attorney before suffering a serious injury.
The appellate court reversed because the trial court had not made the required finding that the person’s chosen representative was contrary to the ward’s best interests.
What Happens If You Do Nothing?
If you die without a valid will, Florida’s intestacy laws determine who inherits property subject to those laws.
If you become incapacitated without appropriate planning, family members may have to rely on whatever legal mechanisms are available under the circumstances. A guardianship proceeding may become necessary for some decisions, although Florida law recognizes advance directives and other planning tools that can sometimes provide alternatives or affect the scope of a guardianship.
The important point is not that everyone needs every available document.
It is that leaving the decisions entirely to default legal rules may produce a result different from the one you would have chosen yourself.
Estate Planning After Marriage, Divorce, or Other Major Changes
An estate plan should not necessarily remain unchanged for decades.
A major life event may require a review of:
Your will
Revocable trust
Beneficiary designations
Durable power of attorney
Health care surrogate
Living will
Preneed guardian designation
Ownership of real estate
Retirement accounts
Life insurance
Business interests
Divorce is a particularly important example. Florida law contains rules affecting fiduciary appointments and certain estate planning documents after dissolution proceedings begin or a final judgment is entered. The Florida Bar has noted that durable powers of attorney and health care surrogate designations require particular attention during divorce planning.
A plan should also be reviewed when a beneficiary or fiduciary dies, a child reaches adulthood, substantial assets are acquired or sold, or the person’s family circumstances change.
“The best estate plan is one that makes the owner’s intentions clear before the family is forced to interpret them under pressure. A trust can provide that structure, but the document and the ownership of the assets need to work together.”
That principle applies beyond trusts. Estate planning works best when the documents, property ownership, beneficiary designations, and the person’s actual wishes are coordinated.
Common Estate Planning Questions
Do I need a will if I have a revocable living trust?
Often, yes. A will can serve purposes that a revocable trust does not, including addressing assets that were never transferred to the trust and nominating a personal representative or guardian where appropriate. The specific documents needed depend on the estate plan.
Does a will avoid probate in Florida?
No. A will generally directs the distribution of probate assets through the probate process. Some property may pass outside probate through trusts, beneficiary designations, joint ownership, or other mechanisms.
What is the difference between a living will and a health care surrogate?
A health care surrogate designation identifies someone who can make health care decisions within the authority granted when you cannot make them yourself. A living will communicates your wishes concerning life prolonging procedures in the circumstances covered by Florida law.
Does my spouse automatically have authority to manage everything if I become incapacitated?
Not necessarily. Marriage and joint ownership do not automatically give one spouse every legal authority that a properly executed power of attorney or health care designation can provide.
Can I choose who I want as my guardian?
Florida allows a competent adult to designate a preferred preneed guardian. The designation creates a rebuttable presumption in favor of the named person, but the court can decline to appoint someone who is unqualified or whose appointment is otherwise contrary to the applicable legal standard.
When should I review my estate plan?
Reviewing an estate plan after marriage, divorce, a death in the family, the birth or maturation of children, a major change in assets, a change in beneficiaries, or a significant change in your circumstances can help keep the plan consistent with your current wishes.
Estate Planning for Families in Coral Springs and Broward County
Estate planning is not limited to deciding who receives your property after death. For families in Coral Springs, Broward County, and surrounding South Florida communities, an effective plan can also address incapacity, health care decisions, financial management, real estate, beneficiary designations, trusts, and the administration of an estate.
The appropriate documents depend on the person’s family circumstances, property, financial affairs, and wishes.
A review of an existing plan can also be useful when the documents were prepared years ago or when major changes have occurred in the family or the assets involved.