Most people think of an estate plan as a set of documents: a will, perhaps a trust, powers of attorney, and other papers kept somewhere safe.
But there is another part of estate planning that matters just as much: how each asset is actually owned and what happens to it when you die.
A bank account can pass directly to a named beneficiary. A retirement account can do the same. Property owned with rights of survivorship may pass to the surviving owner. Assets properly transferred to a revocable trust can pass through the trust rather than through probate.
Other property may still become part of the probate estate.
So avoiding probate is not usually about finding one document or legal trick that makes the entire estate disappear from court supervision. It is about deciding, asset by asset, how ownership should change when you die.
Probate Is Not One Destination for Everything You Own
Imagine someone dies owning a house, a checking account, a retirement account, an investment account, and a life insurance policy.
It would be easy to think of all of these as “the estate” and assume they follow the same process.
They do not.
The legal mechanism attached to each asset can determine what happens next.
Asset or arrangement
Possible transfer mechanism
May avoid probate?
Main consideration
Life insurance with beneficiary
Beneficiary designation
Yes
Keep the designation current
Retirement account
Beneficiary designation
Yes
The account designation matters
Bank account with POD designation
Pay on death designation
Yes
Florida law governs the transfer
Securities registered in beneficiary form
Transfer on death registration
Yes
Registration must comply with applicable requirements
Joint property with survivorship
Survivorship rights
Yes
The form of ownership matters
Properly funded revocable trust
Trust administration
Yes
Assets must actually be transferred to the trust
Solely owned property without another mechanism
Probate administration
Generally no
Probate may be required
Florida homestead
Special rules
Depends
Family and ownership circumstances matter
Florida law specifically provides for pay on death accounts and allows qualifying securities registered in beneficiary form to pass to surviving beneficiaries rather than becoming part of the deceased owner’s estate.
That is why estate planning is better understood as a system of ownership and transfer than simply a collection of documents.
Start With the Asset, Not the Will
A will is important, but it does not necessarily control every asset you own.
If a retirement account names a beneficiary, that designation can determine who receives it. A valid pay on death designation can cause funds in a qualifying account to pass directly to the surviving beneficiary. Securities registered in beneficiary form can likewise pass according to that registration.
The more useful question is therefore:
Does the way this asset is titled or designated actually match the estate plan?
A will can say one thing while an outdated beneficiary designation says another.
Marriage, divorce, the birth of children, the death of a beneficiary, remarriage, or a major change in financial circumstances can all be reasons to review these arrangements.
Beneficiary Designations: Simple, but Worth Reviewing
Beneficiary designations are among the most straightforward ways to arrange for certain assets to pass outside probate.
Florida’s pay on death statute covers deposit accounts including checking accounts, savings accounts, certificates of deposit, and similar accounts. When the relevant account owner dies, the funds generally pass according to the valid designation.
Florida also has a separate statutory system for securities registered in beneficiary form. Under §711.507, ownership passes to beneficiaries who survive the owner or owners, subject to the statutory requirements.
Similar arrangements are common with:
Life insurance
Retirement accounts
Annuities
Certain investment accounts
Pay on death bank accounts
The important word is designation.
An estate plan may have been carefully prepared years ago, but the financial institution generally follows the designation governing the account or policy.
That makes beneficiary review an important part of estate planning.
A Revocable Trust Can Avoid Probate, but It Has to Be Funded
A revocable living trust is one of the best-known probate avoidance tools.
During the owner’s lifetime, assets are transferred to the trust and managed by the trustee. After death, the successor trustee can administer trust property without requiring a probate appointment for those particular assets.
But signing the trust is only part of the process.
The Florida Bar puts it plainly: “The ‘funding’ of a revocable trust is critical to successfully avoid probate.”
A trust document does not automatically place every asset you own into the trust.
If assets remain titled solely in the deceased person’s name, those assets may still require probate. The Florida Bar notes that an incompletely funded trust can result in both probate administration for assets outside the trust and trust administration for assets held by the trust.
The documents and the ownership records therefore need to agree.
Joint Ownership Can Avoid Probate. It Can Also Change Your Rights Now.
Joint ownership with survivorship rights can allow property to pass automatically to the surviving owner.
That can be useful. It is also more consequential than simply naming someone as a beneficiary.
Adding another person as a joint owner can give that person legal rights during your lifetime. Depending on the asset and ownership arrangement, joint ownership can also create complications involving creditors, taxes, estate expenses, simultaneous deaths, or unequal treatment among heirs.
The Florida Bar warns that joint ownership can sometimes “cause more problems than it solves.”
The point is not that joint ownership is inherently problematic. It is that avoiding probate should not be the only consideration when deciding who should own an asset.
“People often think avoiding probate requires something complicated. In many cases, it starts with a few simple decisions about how your property is owned and who should receive it. A little planning can make things much easier for the people you leave behind.”
Florida Homestead Is Different
A Florida home deserves special attention because homestead does not always follow the same rules as an ordinary investment account.
Florida law establishes specific rules governing the descent of homestead. When a decedent is survived by a spouse and descendants, for example, §732.401 provides for a life estate in the surviving spouse with a vested remainder in the descendants, while also giving the spouse an option to elect an undivided one-half interest instead. That election generally must be made within six months and is irrevocable.
The statute also expressly excludes certain property owned as tenancy by the entireties or joint tenancy with rights of survivorship from its operation.
Florida also has separate rules governing lifetime transfers of homestead, including transfers involving trusts.
In other words, the family home should not simply be treated as another asset on a generic probate avoidance checklist.
Giving Property Away Is Not the Same as Avoiding Probate
The simplest version of this strategy is also the most misleading: give property away before you die and it cannot enter your probate estate.
Technically, transferring ownership during life can accomplish that.
But it also means giving up ownership during life.
That can affect control over the property, creditors, taxes, family relationships, eligibility for certain benefits, and what happens if the recipient later dies, divorces, becomes incapacitated, or experiences financial problems.
Sometimes a lifetime gift makes sense. Sometimes another estate planning mechanism accomplishes the intended result without transferring ownership immediately.
“Avoids probate” is therefore not enough reason, by itself, to give something away.
The Real Problem: When the Plan and the Assets Disagree
Consider an estate with:
A house titled individually
A retirement account naming a former spouse
A bank account with a current beneficiary
An investment account owned jointly with one child
A revocable trust that was signed but never funded
A will dividing the estate equally among three children
The documents may all look reasonable in isolation.
Together, they could produce a very different result.
The former spouse may still receive the retirement account. The joint account may pass to one child. The bank account may pass to another beneficiary. The unfunded trust may not control the assets its creator expected it to control. The house may require a separate analysis because of Florida’s homestead rules.
The will may ultimately govern only the property that remains subject to probate.
This is why estate planning is not simply a question of:
“Do I have a will?”
It is also:
“Do my assets actually pass the way I think they will?”
A Practical Probate Avoidance Review
A useful review begins with the assets themselves.
For each significant asset, ask:
Who owns it now?
How is it titled?
Does it have a beneficiary designation?
Does it have survivorship rights?
Is it owned by a trust?
What happens if the named beneficiary dies first?
Does the arrangement conflict with the will or trust?
Are there special Florida rules governing the asset?
That review can reveal that an estate plan needs only a few updates.
It can also reveal several different transfer mechanisms working against one another.
Avoiding Probate Does Not Mean Avoiding Every Legal Process
Probate is not inherently a failure of estate planning. It is a legal mechanism for administering property that falls within the probate estate.
Avoiding probate can reduce court involvement for particular assets, and trust planning can sometimes prevent additional probate proceedings in another state when someone owns property outside Florida.
But a trust does not make administration disappear.
A successor trustee still has responsibilities involving assets, debts, beneficiaries, and distribution. The Florida Bar notes that many of the practical tasks performed by a personal representative must also be performed by a trustee administering a revocable trust.
The goal, then, is not simply less paperwork.
It is a transfer plan that matches the person’s wishes, family circumstances, assets, and Florida law.
Probate Avoidance in Coral Springs and Broward County
For families in Coral Springs and Broward County, probate planning ultimately comes down to the relationship between Florida law and the way the family’s assets are actually owned.
A homeowner may have very different planning considerations from someone whose estate consists primarily of retirement and investment accounts. A married couple may face different issues from an unmarried person. Someone with children from a previous relationship may need to coordinate beneficiary designations and ownership structures particularly carefully.
There is no single “avoid probate” document that produces the same result for every Florida estate.
The better question is which legal mechanism should govern each significant asset and whether those mechanisms work together.
When an Estate Planning Attorney Can Help
If you are planning your estate in Coral Springs, Broward County, or elsewhere in South Florida, an estate planning attorney can review more than whether you have a will.
The review can include how assets are titled, whether beneficiary designations match your wishes, whether a revocable trust is appropriate and properly funded, and whether Florida’s homestead rules affect the plan.
The objective is not to avoid probate at all costs.
It is to understand which assets will pass through probate, which can pass outside it, and whether the overall plan produces the result you actually intend.
Reinfeld & Cabrera P.A. assists clients with estate planning, trusts, probate, and related matters in Coral Springs, Broward County, and throughout South Florida.
If you are reviewing an existing estate plan or creating one for the first time, contact Reinfeld & Cabrera P.A. to discuss how your assets are owned and how Florida law may affect their transfer after death.
Questions People Often Ask
Can I avoid probate completely in Florida?
Some estates can be structured so that significant assets pass outside probate. Whether that is appropriate depends on the assets, ownership structures, beneficiary designations, family circumstances, and Florida law.
Does having a will avoid probate?
No. A will generally directs the distribution of property that remains subject to probate. It does not, by itself, remove those assets from the probate process.
Does a revocable trust avoid probate in Florida?
It can, but the relevant assets must be properly transferred to the trust or otherwise coordinated with it. An unfunded trust may leave assets subject to probate.
Can a beneficiary designation avoid probate?
A valid beneficiary designation can allow certain assets to pass outside probate. Florida law specifically recognizes pay on death accounts and beneficiary registrations for qualifying securities.
Can I put my Florida home in a trust to avoid probate?
Florida homestead is subject to special constitutional and statutory rules. A trust may be appropriate in some circumstances, but homestead should not be treated like an ordinary investment asset.
Is avoiding probate always the best option?
Not necessarily. Probate serves legitimate purposes, including administration of assets that fall within the probate estate. The appropriate estate plan depends on the circumstances rather than on avoiding court involvement as an end in itself.
Yes, creditors can sometimes take money from a trust in Florida, but their rights depend on who owes the debt and how the trust is structured. Florida law generally allows creditors to reach assets in a revocable trust during the creator’s lifetime. A valid spendthrift provision in an irrevocable trust can protect a beneficiary’s undistributed interest from many ordinary creditors, although statutory exceptions apply.
When can creditors reach trust assets in Florida?
Revocable trusts: Creditors can generally pursue assets in a revocable trust when the person who created it owes the debt.
Spendthrift trusts: A valid spendthrift provision can protect a beneficiary’s undistributed interest from many ordinary creditors.
Distributed inheritances: Once the trustee pays the beneficiary, the funds may become subject to ordinary collection procedures.
Exceptions: Certain support claims and other legally recognized circumstances can permit creditors to reach otherwise protected interests.
Fraudulent transfers: Florida law allows qualifying transfers intended to hinder, delay, or defraud creditors to be challenged.
These rules are governed primarily by Part V of Florida’s Trust Code, including the provisions addressing spendthrift trusts and claims against revocable trust assets. The sections below explain how each rule works and what it means for beneficiaries and trustees in Coral Springs and Broward County.
Key points for Florida residents:
A creditor generally has broader access to assets in a revocable trust while its creator is alive.
A valid spendthrift provision can restrict a beneficiary’s creditors from reaching an undistributed trust interest.
Certain claims, including qualifying support obligations, may fall within statutory exceptions.
Money distributed to a beneficiary may lose some or all of its protection under trust law.
Transfers designed to hinder existing creditors can be challenged under Florida’s voidable transfer laws.
These rules matter when someone is planning an inheritance, administering a deceased relative’s estate, or responding to a creditor claim in Coral Springs or elsewhere in Broward County.
1. Can Creditors Reach Assets in a Florida Trust?
The first step is identifying whose debt is involved. Florida law does not treat the trust creator and the beneficiary as interchangeable.
When the person who created the trust owes the debt
A revocable living trust generally does not protect its assets from the creator’s creditors during the creator’s lifetime. Under Florida Statute § 736.0505, property in a revocable trust remains available to satisfy the claims of the settlor’s creditors.
A settlor is the person who creates and funds a trust. If that person can revoke the trust and recover its assets, the trust ordinarily does not place those assets beyond the reach of legitimate creditor claims.
Example: A Coral Springs homeowner transfers investment accounts into a revocable living trust. The homeowner later defaults on a substantial personal loan. The transfer alone does not prevent the lender from pursuing trust assets that remain subject to the homeowner’s control.
The analysis can change after the creator dies or when a trust is genuinely irrevocable. Even then, the specific statutory rules and the circumstances surrounding the transfer must be examined.
When a beneficiary owes the debt
The rules can be considerably more protective when the debtor is a beneficiary of an irrevocable trust created by someone else.
Under Florida Statute § 736.0502, a valid spendthrift provision can prevent a beneficiary from voluntarily transferring the protected interest. It can also prevent most creditors from attaching that interest before the trustee distributes the money.
Example: A father establishes an irrevocable trust for his adult daughter. The trust contains an enforceable spendthrift provision. The daughter later falls behind on credit card payments. A card issuer generally cannot seize her undistributed beneficial interest merely because she owes money.
That does not mean the trust is immune from every claim. Florida law recognizes exceptions, and a creditor may have other remedies depending on the facts.
2. What Is a Spendthrift Trust in Florida?
A spendthrift trust contains language restricting a beneficiary’s ability to transfer the beneficiary’s interest. The restriction also limits the ability of creditors to reach that interest before the trustee distributes it.
Florida Statute § 736.0502 establishes the requirements for an enforceable spendthrift provision. The provision must restrain both voluntary and involuntary transfers of the beneficiary’s interest.
This distinction matters. A clause that merely expresses the creator’s hope that a beneficiary will manage money responsibly does not necessarily establish the statutory protection.
How spendthrift protection works
Suppose a trust holds $400,000 for a beneficiary who has accumulated substantial unsecured debt. The trustee must follow the trust’s terms when deciding whether and when to distribute funds.
If the trust contains an enforceable spendthrift provision, the beneficiary generally cannot assign the protected interest to a creditor. The creditor ordinarily cannot attach that undistributed interest either, subject to the exceptions established by law.
The trustee must still administer the trust according to its terms and applicable fiduciary duties. Spendthrift language does not give a trustee unlimited discretion to disregard the beneficiary’s rights.
Does every irrevocable trust provide creditor protection?
No. Irrevocability alone does not guarantee that trust assets are protected from every creditor.
The trust’s language matters. So does the identity of the debtor. A trust created by a third party for a beneficiary presents a different legal situation from a trust a debtor creates for personal benefit.
A transfer into an irrevocable trust can also be challenged if it violates Florida’s voidable transfer laws. The relevant provisions appear in Florida Statutes Chapter 726.
The source of the money matters as well. A court will examine the actual arrangement rather than rely exclusively on the label attached to the trust.
3. Revocable Trusts vs. Irrevocable Trusts
The difference between revocable and irrevocable trusts is central to creditor protection.
Feature
Revocable trust
Irrevocable trust
Can the creator generally revoke it?
Yes, subject to the instrument and law
Generally not unilaterally, although some arrangements permit modification
Creditor access to the creator’s assets
Generally available during the creator’s lifetime
Depends on the creator’s retained rights and applicable law
Protection for a beneficiary
Depends on the arrangement and stage of administration
A valid spendthrift provision can protect an undistributed interest from many creditors
Can every creditor claim be blocked?
No
No
Can the transfer be challenged?
Depending on the circumstances
Yes, including under voidable transfer laws
Revocable Living Trusts
Revocable living trusts are popular for good reason. They let people decide how their property will be handled after death without necessarily putting their families through probate. They can also make things easier if the person who created the trust becomes unable to manage their own affairs.
But there’s an important limitation when creditors are involved. Under Florida Statute § 736.0505, assets in a revocable trust are generally available to the creator’s creditors during their lifetime. The creator can still revoke the trust and take the property back, so the transfer does little to separate those assets from their personal financial obligations.
This is where people can get caught out. A revocable trust may be perfectly suitable for managing an estate, yet do very little to protect the creator’s property from a creditor pursuing an unpaid debt. Those are two different goals, and a trust designed for one should not be mistaken for a solution to the other.
Irrevocable Trusts
Irrevocable trusts work differently because the person who creates one generally gives up the ability to take the assets back whenever they want. Depending on the trust’s terms, the property may be managed for beneficiaries who cannot demand an immediate distribution. That separation can make it harder for certain creditors to reach the assets.
Of course, the details matter. A trust does not become immune to creditors simply because its creator calls it irrevocable. The rights retained by the creator can affect the protection available, and Florida law allows creditors to challenge certain transfers.
Consider someone who moves valuable property into an irrevocable trust after learning that a lawsuit may be coming. Under Florida’s Uniform Voidable Transactions Act, Chapter 726, a creditor may challenge the transfer if the legal requirements are satisfied. A court can look at the circumstances and determine whether the arrangement was used to put assets beyond a creditor’s reach.
For anyone planning an estate, the distinction matters. An irrevocable trust may provide stronger creditor protection, but that protection comes with restrictions on what the creator can do with the property later. It is worth understanding those restrictions before transferring assets that may be difficult or impossible to recover.
4. Which Creditors Can Reach a Beneficiary’s Trust Interest?
Florida law provides meaningful protection for many trust beneficiaries, but it does not make every trust interest unreachable.
Ordinary unsecured creditors
Credit card companies and personal loan lenders generally cannot attach a beneficiary’s interest before distribution when an enforceable spendthrift provision applies.
That protection is not a blanket defense against every legal action. A creditor may still investigate whether an exception applies or whether the trust arrangement can be challenged.
Child support and spousal support
Florida Statute § 736.0503 establishes exceptions to spendthrift protection for certain claims. These include qualifying claims for support or maintenance of a beneficiary’s child, spouse, or former spouse.
The statute also addresses certain services that protect the beneficiary’s interest in the trust.
The precise claim and the statutory requirements matter. A creditor cannot assume that every family law judgment automatically overrides a spendthrift provision.
Government claims
Government claims require separate analysis. The availability of trust assets depends on the governing statute, the type of obligation, and the beneficiary’s rights under the trust.
For example, a claim involving taxes should not be analyzed as though it were an ordinary credit card debt. Federal collection rules may also be relevant.
Judgments and lawsuits
A creditor with a judgment does not automatically gain unrestricted access to every trust asset. The judgment establishes a legal claim, but collection still depends on the property involved and the law governing that property.
A court may need to determine whether the debtor has a present right to receive money or only a protected interest in future distributions.
5. What Happens When the Trustee Distributes the Money?
Distribution can change the analysis significantly.
Spendthrift protection generally applies to the beneficiary’s interest before the trustee transfers the money. Once funds reach the beneficiary, the creditor may be able to pursue them under ordinary collection law.
The outcome depends on where the money goes and whether another legal protection applies.
Money deposited into a personal bank account
Suppose a trustee distributes $50,000 to a beneficiary with outstanding credit card debt. The beneficiary deposits the money into a personal checking account.
The beneficiary should not assume that the original trust provision continues to protect the funds indefinitely. A judgment creditor may be able to pursue money in the account through lawful collection procedures.
Florida law provides exemptions for certain property and income. Those exemptions must be evaluated independently from the trust’s spendthrift clause.
Money used to buy another asset
Converting a distribution into another asset does not automatically preserve trust protection.
The result depends on the asset purchased and any applicable exemption. For example, Florida’s homestead protections may be relevant to a qualifying primary residence, but those rules have specific requirements and exceptions.
A beneficiary should not assume that purchasing a home with trust money makes the funds untouchable. The source of the money, the property’s use, and the applicable legal requirements all matter.
Money retained by the trustee
When the trustee has not distributed the money, the beneficiary’s creditors may have fewer collection options. The creditor must account for the trust terms and any applicable statutory exceptions.
The trustee should not make an improper distribution simply because a beneficiary is facing collection pressure. The trustee must follow the instrument and applicable law.
6. Can a Trustee Refuse to Distribute Money Because of a Creditor?
The answer depends on the trust’s distribution terms and the trustee’s legal duties.
Some trusts require distributions when specified conditions are met. Others give the trustee discretion to decide when distributions are appropriate.
A trustee cannot automatically withhold a mandatory distribution merely because the beneficiary has creditors. The trust instrument and Florida law determine what the trustee must do.
Discretionary distributions
Under Florida Statute § 736.0504, a creditor generally cannot compel a distribution that remains within the trustee’s discretion, subject to statutory exceptions.
For example, a trust may authorize distributions for a beneficiary’s health or education. The trustee must exercise that discretion according to the trust’s terms and fiduciary obligations.
A creditor generally cannot force the trustee to exercise discretion in the creditor’s favor simply because the beneficiary owes money.
Mandatory distributions
A trust may require a trustee to distribute a fixed amount at a specified age or on a defined date.
When a distribution becomes due, the legal position can differ from a situation in which the trustee has discretion. Florida Statute § 736.0506 addresses creditor claims involving certain overdue mandatory distributions.
The timing and wording of the trust are important. A beneficiary should not assume that an enforceable right to a distribution receives the same treatment as a purely discretionary interest.
What trustees should avoid
A trustee should not invent new restrictions simply to prevent a beneficiary’s creditor from collecting. The trustee should also avoid making an unauthorized distribution based on informal pressure from a beneficiary or creditor.
When a demand arrives, the trustee should review the instrument and determine whether the claimant has a legally enforceable right to the funds.
7. Can Creditors Challenge a Transfer Into an Irrevocable Trust?
Yes. Florida law permits certain transfers to be challenged when the transfer meets the legal requirements for a voidable transaction.
Under Florida Statutes Chapter 726, a court may examine the circumstances surrounding a transfer to determine whether it was made with actual intent to hinder, delay, or defraud a creditor. The statute also addresses certain transfers made without reasonably equivalent value when the debtor meets specified financial conditions.
A transfer made before financial trouble
A person who creates an irrevocable trust as part of a legitimate estate plan before any creditor dispute arises may present a different case from someone who transfers assets after receiving a lawsuit or collection demand.
Timing is relevant, but timing alone does not decide the outcome. The court may examine the debtor’s financial condition and other evidence surrounding the transaction.
A transfer made after a lawsuit begins
Suppose a business owner faces a substantial judgment and then transfers most personal assets into a trust for a family member.
The creditor may investigate whether the transfer was designed to obstruct collection. If the evidence supports a claim under Chapter 726, the creditor may seek a remedy through the court.
The trust’s irrevocable status does not automatically defeat that challenge.
A debtor who transfers property while concealing assets or giving misleading information may create additional legal exposure. The precise consequences depend on the conduct and the applicable law.
Anyone considering a trust transfer during an existing creditor dispute should obtain legal advice before moving property. A transfer that appears protective at first can become the basis of further litigation.
8. Florida Court Decisions That Help Explain Creditor Access
Statutory language establishes the basic rules, while court decisions illustrate how those rules operate in actual disputes.
Miller v. Kresser: Practical control did not defeat spendthrift protection
In Miller v. Kresser, 34 So. 3d 172 (Fla. 4th DCA 2010), Gary Kresser obtained a judgment of approximately $1.02 million against James Miller and his construction company. Unable to collect, Kresser pursued assets held in an irrevocable trust established for James by his mother. The trust contained a spendthrift clause and named James’s brother, Jerry, as trustee.
Although Jerry held formal authority over distributions, the trial court found that James effectively controlled the trust’s investments and operations. It invalidated the spendthrift protection and allowed Kresser to pursue trust assets, including the trust’s interest in property in Islamorada.
The Fourth District Court of Appeal reversed. It found that Jerry retained the legal authority to decide whether to distribute trust property. James could influence decisions, but he could not compel distributions. His practical involvement therefore did not, by itself, make the undistributed assets available to his creditor.
Why it matters: A creditor cannot necessarily seize trust assets because a beneficiary appears to control their management. The trust’s terms and the beneficiary’s enforceable rights are central to determining whether assets remain protected.
Zlatkiss v. All America Team Concepts: A valid judgment does not guarantee access to trust funds
In Zlatkiss v. All America Team Concepts, LLC, 116 So. 3d 525 (Fla. 5th DCA 2013), Robert and Linda Zlatkiss lent $350,000 to a company whose principal, Louis Steinmetz, personally guaranteed the loan. Steinmetz had represented that he had approximately $6.85 million available through a trust. When the loan went unpaid, the Zlatkisses sought recovery and challenged the constitutionality of Florida’s spendthrift trust protections after the trustee refused to release funds to satisfy the debt.
The Fifth District Court of Appeal upheld the protections. It explained that the constitutional right to access the courts allows creditors to pursue legal claims, but does not guarantee collection from every asset belonging to a debtor. Florida’s recognition of valid spendthrift trusts also predated the statutes challenged in the case.
Why it matters: A creditor may obtain a judgment against a debtor without gaining access to the debtor’s trust interest. For lenders, the case underscores the importance of determining whether a borrower can actually access trust assets before relying on them as a source of repayment.
In re Brown: A debtor could not shield an income interest in a trust she created
In In re Brown, 303 F.3d 1261 (11th Cir. 2002), Jane McLean Brown used an inheritance of approximately $250,000 to establish an irrevocable charitable remainder unitrust. She retained the right to receive annual payments equal to 7% of the trust’s value, while the remaining assets were designated for charitable beneficiaries. The trust included a spendthrift clause.
When Brown filed for Chapter 7 bankruptcy, she argued that the clause protected her interest from creditors. The Eleventh Circuit rejected that argument. Because Brown had created the trust for her own benefit and retained a right to income, she could not use the spendthrift provision to shield that interest in bankruptcy. Her retained income rights were available to the bankruptcy estate, although the trust principal itself was not available to satisfy her personal debts.
Why it matters: An irrevocable trust does not automatically protect every interest held by the person who created it. Courts may distinguish between property transferred irrevocably to others and income rights the creator retained for personal benefit.
What these decisions mean for Florida creditors and beneficiaries
These cases illustrate different limits on creditor access to trust assets. Miller examines practical control over a discretionary trust. Zlatkiss addresses the limits of collecting a judgment from protected trust interests. In re Brown concerns a debtor who created a trust while retaining an income interest.
The outcome depends on the trust agreement, the debtor’s legal rights, and the applicable law. Bankruptcy can introduce additional rules, so a decision arising under federal bankruptcy law should not automatically be treated as controlling every Florida collection dispute.
9. Household Debt and the Risk to Inheritances
An inheritance can arrive at an awkward time: a beneficiary may be dealing with unpaid debts just as money or property passes into their hands. The scale of household debt in the United States helps explain why this issue matters.
According to the Federal Reserve Bank of New York’s February 2026 household debt report, Americans owed approximately $18.8 trillion in household debt at the end of 2025. That balance grew by roughly $191 billion in a single quarter. The report also found that 4.8% of outstanding household debt was in some stage of delinquency.
These figures show the scale of the debt burden facing American households. They do not tell us how many Florida beneficiaries face collection claims, or how often creditors successfully reach trust assets. They do, however, provide context for a practical concern: when someone with unpaid debts inherits money, the legal protection surrounding that inheritance can make a substantial difference.
What these numbers mean for trust beneficiaries
A debt does not automatically give a creditor the right to seize trust assets. Florida law distinguishes between assets held in a trust and property a debtor owns or has the legal right to receive. A properly drafted spendthrift provision may protect a beneficiary’s undistributed interest from many creditors, subject to statutory exceptions.
That protection can change when a trustee distributes the funds. Once the inheritance reaches the beneficiary, it may become available to creditors under ordinary collection rules, depending on the circumstances and any applicable exemptions.
The figures above establish the financial context, not the legal outcome. Whether a creditor can reach an inheritance ultimately depends on the trust’s terms, the beneficiary’s rights, and the protections Florida law provides.
10. Common Misconceptions About Trusts and Creditors in Florida
Misconception 1: An irrevocable trust is immune from every creditor
Reality: Irrevocability does not eliminate all creditor rights. The creator’s retained interests, statutory exceptions, and potential challenges to the original transfer can affect the outcome.
Misconception 2: A revocable living trust protects the creator’s assets from personal debts
Reality: Florida Statute § 736.0505 generally allows creditors to reach assets in a revocable trust during the settlor’s lifetime.
A revocable trust may serve important estate planning purposes, but it should not be treated as a substitute for a valid creditor protection strategy.
Misconception 3: A beneficiary’s inheritance is protected forever
Reality: Spendthrift protection generally concerns the beneficiary’s interest before distribution. After receiving money, the beneficiary may face ordinary collection proceedings unless another protection applies.
Misconception 4: A creditor with a judgment can seize anything connected to the debtor
Reality: A judgment does not eliminate statutory protections. The creditor must still identify property that can legally be reached.
Misconception 5: A trustee can always refuse payment to keep creditors away
Reality: The trustee must follow the trust instrument. A mandatory distribution cannot automatically be withheld because the beneficiary has debts.
Misconception 6: Moving money into a trust after a lawsuit begins solves the problem
Reality: A creditor may challenge a transfer under Florida’s voidable transfer laws. The transaction can create further legal disputes rather than resolve the original debt.
Misconception 7: Trust protection and Florida homestead protection are the same
Reality: They are separate legal concepts. Florida’s homestead protections are governed by distinct constitutional and statutory rules, and the requirements depend on the property and circumstances.
11. Florida Homestead, Exemptions, and Other Protections
Trust law is only one part of the creditor analysis. Other Florida laws may protect particular assets or income, but those protections should not be assumed to apply automatically to inherited money.
Florida Homestead: When a Home Gets Special Protection
Florida’s homestead exemption is one of the state’s strongest forms of asset protection. Under the Florida Constitution, qualifying primary residences receive substantial protection against forced sale by many creditors. That can make a significant difference when someone faces a judgment and owns a home.
The protection has specific requirements and exceptions. In Havoco of America, Ltd. v. Hill (2001), a creditor argued that a debtor had used funds to acquire a homestead with the intent to keep those assets beyond creditors’ reach. The Florida Supreme Court concluded that the homestead exemption still applied under the circumstances, even though the purchase was allegedly motivated by creditor avoidance. The court explained that the constitutional protection could not be denied on that basis alone when the transaction did not fall within an established exception.
That ruling is powerful, but it is not a blanket permission to move any asset into a home and declare it untouchable. The property must qualify as homestead, and the legal circumstances matter. Nor does the decision mean that money held in a trust automatically receives homestead protection. The rules governing trust assets and those governing a qualifying residence are distinct.
Wage Exemptions: Your Paycheck May Have Protection of Its Own
Florida law also protects certain earnings from creditors. Under Florida Statute § 222.11, qualifying head of family earnings receive specific protections, subject to the statute’s requirements and exceptions.
These rules matter when a creditor seeks to garnish wages. They do not automatically extend to every dollar that later enters the same bank account. A beneficiary who receives a trust distribution should not assume that the payment qualifies as protected earnings simply because it will be used to cover ordinary living expenses.
The source of the money and the legal requirements for the exemption both matter. When wages and other funds are mixed together, identifying the protected portion may become more complicated.
Bankruptcy: A Different Set of Rules Can Change the Outcome
When a debtor files for bankruptcy, the analysis moves beyond ordinary state court collection procedures. Federal bankruptcy law determines what enters the bankruptcy estate and provides mechanisms for challenging certain transfers made before filing.
A trust that limits a creditor’s access under Florida law does not necessarily produce the same result in bankruptcy. The outcome depends on the debtor’s interest in the trust and the applicable bankruptcy rules. Transfers made before filing may also face scrutiny under federal law.
This is particularly important when someone creates a trust, transfers property into it, or retains rights to receive payments before seeking bankruptcy protection. The word irrevocable does not settle the question. The actual arrangement and the timing of the transactions must be examined.
Debt Collection Rights: Creditors Have Rules to Follow Too
Trust disputes are not the only legal issue a beneficiary may face. Collection communications can raise separate questions about what a debt collector is allowed to say or do.
However, rules governing collection conduct do not determine whether a creditor can legally reach a particular trust interest. A collector may be restricted in how it pursues a debt while still having a valid claim against assets available under applicable law. Conversely, a creditor’s right to collect a debt does not give it unlimited authority to seize protected property.
The important distinction: Asset protection and debt collection conduct are separate questions. A beneficiary needs to understand both the legal status of the assets and the limits on the creditor’s collection methods.
12. Practical Procedures When a Creditor Targets Trust Assets
A creditor demand involving a trust should be handled carefully. The trustee and beneficiary may have different rights and obligations, so each should understand their own position before responding.
Step 1: Identify the debtor
Determine whether the debt belongs to the trust creator, the beneficiary, or another person.
This is the first legal distinction to establish. A creditor pursuing the settlor may have rights that would not apply to an ordinary creditor of a beneficiary.
Step 2: Obtain and review the trust instrument
Locate the complete trust document and any amendments. Identify whether the trust is revocable or irrevocable and whether it contains a spendthrift provision.
Review the distribution terms as well. The trustee’s authority may differ depending on whether distributions are mandatory or discretionary.
Step 3: Determine whether the money has been distributed
Establish whether the assets remain in the trust or have already been transferred to the beneficiary.
This distinction may determine which creditor remedies are available. Keep records of the distribution date and the destination of the funds.
Step 4: Identify the creditor’s legal claim
Review the demand letter, judgment, court order, or other documents identifying the debt.
Determine whether the claim involves ordinary consumer debt, a support obligation, a tax liability, or another category that may trigger different rules. Do not assume every creditor has the same collection rights.
Step 5: Preserve relevant records
Keep copies of the trust instrument, account statements, distribution records, creditor correspondence, and any relevant court filings.
Do not destroy or alter records in response to a collection demand. Accurate documentation can help establish the nature and timing of the trust arrangement.
Step 6: Avoid informal promises or unauthorized distributions
A beneficiary should not promise a creditor access to trust money without understanding the legal position. A trustee should not make a distribution that conflicts with the trust instrument or applicable law.
If the creditor has served formal legal papers, observe the stated deadlines. Ignoring a court order or legal notice can create additional problems.
Step 7: Obtain legal advice when the claim is disputed
A Florida estate planning or trust litigation attorney can review the instrument and determine whether the creditor has a valid route to the assets.
Legal advice is particularly important when the trust creator retained control, a distribution is overdue, or the creditor alleges a fraudulent transfer.
Operational checklist for trustees
Before responding to a creditor demand, a trustee should:
Confirm the identity of the debtor and the nature of the claim.
Review the trust instrument and relevant amendments.
Determine whether the interest is subject to a valid spendthrift provision.
Establish whether the requested funds remain in trust.
Check whether a statutory exception may apply.
Preserve relevant records and comply with valid legal process.
Obtain advice before taking action that could breach fiduciary duties.
This checklist is intended to organize the initial review. It does not replace a legal determination about the particular trust or claim.
13. Hypothetical Situations: What Happens When Creditors Come Knocking?
Trust protection can sound wonderfully reassuring until a creditor comes looking for money. The details matter, though, and a creditor’s determination to get paid does not automatically give them the right to raid a trust. Here is how the rules might play out in everyday situations.
Scenario A: Credit card debt and an inheritance still in trust
Daniel owes $35,000 on his credit cards. His mother leaves him an inheritance through an irrevocable trust with a valid spendthrift provision. The trustee has not released the money, and Daniel has no right to demand an immediate payout.
His credit card companies cannot simply call the trustee and request a transfer. Under Florida Statute § 736.0502, ordinary creditors generally cannot attach a beneficiary’s protected interest before distribution. Certain exceptions and successful legal challenges can change that result.
Daniel’s debts have not vanished, of course. His creditors can still pursue other assets available under collection law.
The takeaway: Knowing someone is due an inheritance does not mean a creditor can collect it on demand. An inheritance still held in a protected trust is a very different proposition from money sitting in Daniel’s checking account.
Scenario B: The inheritance has already hit the bank
Maria receives $80,000 from a spendthrift trust and deposits it into her personal account. Unfortunately, she also has an unpaid judgment against her.
Once the trustee distributes the funds, the spendthrift provision generally stops protecting the money from ordinary collection remedies. Maria’s creditor may pursue the account, subject to applicable exemptions.
Maria might wish the trust’s protection came with the money. Unfortunately, legal protections do not always travel as well as cash.
The takeaway: Before distribution, the money may be protected inside the trust. After distribution, Maria may have to deal with creditors under the ordinary collection rules.
Scenario C: The person who created the trust owes money
Robert transfers $400,000 in investments into a revocable living trust. He remains in control and can take the assets back whenever he revokes the trust. Later, he defaults on a personal loan, and the lender obtains a judgment.
Robert argues that the investments belong to the trust. Florida law has an inconvenient answer for that strategy. Under Florida Statute § 736.0505, assets in a revocable trust are generally available to the creator’s creditors during the creator’s lifetime.
In other words, Robert cannot usually put his money in a legal box, keep the key in his pocket, and expect creditors to forget the box exists.
The takeaway: A revocable trust can serve important estate planning purposes. Shielding the creator’s assets from their own creditors generally is not one of them.
Scenario D: A beneficiary falls behind on child support
Elena receives financial support through an irrevocable trust established by her grandparents. She falls behind on court ordered child support, and the other parent seeks to enforce the obligation against her trust interest.
This is not necessarily treated like an unpaid credit card bill. Florida Statute § 736.0503 recognizes exceptions to spendthrift protection for certain claims, including qualifying child support obligations. The available remedy depends on the legal requirements and the trust’s terms.
Elena cannot assume that the spendthrift provision ends the discussion. The other parent cannot assume they are entitled to the entire trust balance, either.
The takeaway: Spendthrift protection can be powerful without being absolute. Certain support obligations receive special treatment under Florida law.
Scenario E: The trust appears just as a lawsuit looms
Michael learns that a former business partner intends to sue him over an unpaid debt. He transfers an investment property into an irrevocable trust for a relative, hoping the creditor will no longer be able to reach it.
The timing is likely to attract attention. Under Florida’s Uniform Voidable Transactions Act, Chapter 726, a creditor may challenge a transfer that meets the statutory requirements for being voidable. A court may consider when the transfer occurred and whether Michael retained control over the property.
Putting the property in an irrevocable trust does not automatically settle the matter in Michael’s favor. If the transfer violates the law, the creditor may seek remedies against it.
The takeaway: An irrevocable trust is not a legal reset button. Transferring property when a creditor is already on the horizon can leave the debtor fighting over the original debt and the transfer itself.
The common thread
A trust can protect an inheritance from certain creditors, but the protection has boundaries. Money still held in a qualifying spendthrift trust may receive different treatment from funds already paid to a beneficiary. A revocable trust generally offers little protection against the creator’s own creditors.
The useful question is what rights the debtor actually has over the assets. That answer usually matters far more than what the trust is called.
14. Frequently Asked Questions About Trusts and Creditors in Florida
Can credit card companies take money from a trust in Florida?
Generally, a credit card company cannot attach a beneficiary’s undistributed interest in a trust with an enforceable spendthrift provision, subject to statutory exceptions. The result may be different if the debtor created a revocable trust or has already received the funds.
Could creditors take money from an irrevocable trust?
Sometimes. An irrevocable trust can protect certain interests, but the result depends on the identity of the debtor, the trust terms, statutory exceptions, and whether the transfer can be challenged.
Can creditors reach a revocable living trust?
Florida Statute § 736.0505 generally permits creditors to reach the assets of a revocable trust during the settlor’s lifetime. The trust’s estate planning benefits do not automatically create creditor protection.
Does a spendthrift clause prevent every creditor from collecting?
No. Florida law recognizes exceptions to spendthrift protection. Certain support claims may qualify, and other legal doctrines may affect the result.
Can a creditor take money after the trustee distributes it?
Potentially. After distribution, the funds may be subject to ordinary collection procedures. Other exemptions may apply depending on the asset and circumstances.
Could a trustee refuse a distribution because the beneficiary owes money?
Not automatically. The trustee must follow the trust instrument and applicable law. A mandatory distribution may be treated differently from a discretionary one.
Can I put my assets in a trust to avoid paying existing debts?
A transfer made to hinder, delay, or defraud creditors may be challenged under Florida’s voidable transfer laws. Anyone considering a transfer while facing a claim should obtain legal advice before acting.
Are trust assets protected during bankruptcy?
Not automatically. Federal bankruptcy law contains rules concerning trust interests and certain transfers. The outcome depends on the trust arrangement and the bankruptcy circumstances.
Does Florida homestead protection apply to money inherited from a trust?
Not automatically. Homestead protection concerns qualifying property under a separate legal framework. Money received from a trust does not become protected merely because the beneficiary intends to use it to buy a home.
Can a creditor force a trustee to make a discretionary distribution?
Generally, a creditor cannot compel a distribution that remains within the trustee’s discretion, subject to statutory exceptions. The terms of the trust and the applicable law determine the trustee’s obligations.
What should I do if a creditor sends a demand involving my inheritance?
Keep the correspondence and obtain the complete trust document. Determine whether the demand concerns an undistributed interest or money already paid to you. If formal court papers arrive, pay attention to the response deadline and obtain legal advice promptly.
Can a creditor challenge a trust created by a deceased parent?
A creditor may examine whether the trust or a transfer into it is subject to a valid legal challenge. The creditor’s rights depend on the trust structure, the relevant statutes, and the facts of the transaction.
15. Trust Creditor Questions in Coral Springs and Broward County
For families in Coral Springs and Broward County, trust creditor disputes can arise during estate administration or after an inheritance becomes available. The applicable Florida statutes remain central regardless of the beneficiary’s city of residence.
A local review may be useful when a trustee receives a creditor demand, when beneficiaries disagree about a proposed distribution, or when a creditor alleges that assets were transferred to frustrate collection.
The location of the trust assets and the parties may affect procedural questions, but geography alone does not determine whether a creditor can reach a beneficiary’s interest.
Final Thoughts
Florida law distinguishes between assets controlled by the person who created a trust and a beneficiary’s interest in a trust established by someone else. A valid spendthrift provision can protect an undistributed beneficiary interest from many ordinary creditors, but statutory exceptions and the terms of the trust matter.
Revocable trusts generally do not protect a living settlor’s assets from that person’s creditors. Distributions can also change the analysis, and transfers intended to obstruct legitimate claims may be challenged.
If the original will is missing in Florida, the court may still admit it to probate if the person seeking probate can prove its contents and establish that it was not revoked. Under Florida Statutes § 733.207, one disinterested witness can establish the contents when a correct copy exists. If no correct copy is available, two disinterested witnesses are required.
But finding a copy does not necessarily solve the problem. Florida courts may presume that a will was revoked if the original was last known to be in the deceased person’s possession and cannot be found after death. That presumption can be challenged with evidence about the document’s disappearance and the person’s intentions.
For families in Coral Springs and Broward County, the stakes can be substantial. A missing will may determine who inherits a family home, receives financial assets, or benefits from an estate plan. Understanding the evidence Florida law requires is the first step toward determining whether the missing document can still be honored.
Can a missing will still be admitted to probate in Florida?
Yes. Florida law allows a lost or destroyed will to be established and admitted to probate under specific conditions. The fact that the original cannot be located does not, by itself, mean the deceased person’s wishes must be disregarded.
The difficult part is proving the document’s terms and addressing whether it remained legally effective at death. Those are separate questions, and a family can have strong evidence on one without having enough evidence on the other.
A photocopy, for instance, might show exactly how the estate was supposed to be distributed. It does not necessarily explain why the original disappeared. That distinction becomes especially important when someone stands to inherit substantially more under the missing will than they would under Florida’s intestacy laws.
What if the family has a photocopy of the will?
A photocopy can be a very useful starting point. It may preserve the exact wording of the will and help identify the people who were supposed to inherit. Florida law expressly accounts for this situation.
Under § 733.207, a correct copy allows the will’s contents to be established through one disinterested witness. Without a correct copy, two disinterested witnesses are required to establish those contents.
There is a catch, however. A document that looks convincing is not necessarily a correct copy of the executed will. A draft saved by the drafting attorney might contain nearly all the same provisions while omitting a final change. An older version might name a beneficiary who was later removed.
In In re Estate of Parker, the Florida Supreme Court distinguished an identical reproduction from a draft that merely reflected the contents of the missing will. That distinction may sound technical until an inheritance depends on whether a document qualifies under the statute.
The practical lesson is simple: preserve every version you find, even if some appear incomplete or outdated. An attorney can assess which documents may help establish the final will and which require further proof.
Who can testify about a missing will?
The law does not simply ask whether someone remembers the will. It matters what that person knows and whether they have an interest in the outcome.
A neighbor might remember that the deceased kept a will in a particular drawer. A relative might recall a conversation about leaving the house to one child. The attorney who prepared the document might have a draft in the firm’s records. Each person could provide useful information, but their testimony would not necessarily establish the precise contents of the missing will.
Florida requires disinterested witnesses to establish those contents under § 733.207. A witness who stands to benefit from the outcome may not qualify for that purpose.
This distinction became important in Pilak v. Reigel. The dispute involved a will and two codicils, which are documents that amend an existing will. A witness named as a beneficiary in a codicil could not establish the documents’ contents. The appellate court reversed the order admitting the documents to probate because the statutory requirements had not been satisfied.
The case offers a useful warning for families. A person may know the deceased extremely well and still be unable to provide the specific testimony the court needs. Familiarity with someone’s wishes is not the same as proof of the terms of a legal document.
The difficult question: Was the will revoked?
Finding a copy can feel like a breakthrough. It gives the family something concrete to work with, and it may settle arguments about what the deceased wanted. But the original’s disappearance can raise another question that a copy alone cannot answer.
Did the deceased intend to revoke the will?
Florida courts recognize a rebuttable presumption of revocation in certain circumstances. If the original will was last known to be in the testator’s possession and cannot be found after death, the court may presume that the testator destroyed it intending to revoke it.
The presumption does not mean that every missing will has been revoked. People misplace documents. Homes are sold, files are moved, and important papers occasionally disappear for reasons nobody can reconstruct. The court must consider the evidence surrounding the particular case.
What evidence can help show that the will remained valid?
There is no universal checklist that guarantees a successful petition. The usefulness of any particular piece of evidence depends on what happened to the document and what the court needs to determine.
Still, a few categories deserve attention.
Statements by the deceased may help establish whether they continued to regard the will as valid. Records from the attorney who prepared the document may help explain which version was final. Evidence about who had access to the original can also matter, particularly if the document disappeared from a location where other people could reach it.
The circumstances surrounding the disappearance deserve careful examination. A will that vanished during a house clearance presents different questions from one that was kept by an attorney and cannot now be located.
These details do not automatically prove that the deceased never revoked the will. They can, however, help the court evaluate competing explanations for what happened.
Two Florida cases show why the evidence matters
In Balboni v. LaRocque, the Fourth District Court of Appeal found the evidence insufficient to overcome the presumption that the deceased had intentionally revoked the missing will.
The result illustrates a difficult reality for families. Being convinced that a loved one would never have changed their mind is not necessarily enough to establish that conclusion in court. The relevant question is what the evidence supports.
A different outcome followed in Walton v. Estate of Walton. The Third District Court of Appeal found sufficient evidence to rebut the presumption. The evidence included a copy of the will and testimony about the deceased person’s wishes, along with circumstances involving the person’s final illness and another individual’s access to the home.
The contrast between these decisions is worth understanding. Florida law does not require families to give up whenever an original disappears. It does require them to establish their position with evidence that meets the applicable legal standard.
When a missing will puts a family home at stake
The consequences become especially tangible when the missing document controls who inherits real estate.
In Property Solutions Powerhouse, LLC v. Nelson, decided in June 2025, the dispute involved Margaret Templeton’s missing will and her homestead. The will purported to leave the property to a friend. After a foreclosure sale, surplus proceeds remained at issue, creating a dispute over who was entitled to the money.
The trial court admitted the lost will to probate. The appellate court affirmed the relevant orders, rejecting arguments concerning notice and the treatment of the homestead.
This kind of dispute helps explain why a missing will should not be treated as a minor paperwork problem. A document that appears to have vanished from a file cabinet can affect ownership of a valuable home or determine who receives the proceeds from its sale.
It also shows why the interests of other potential heirs matter. Someone who expects to inherit under Florida’s default rules may have a very different position from the person named in the missing will. Both may have legitimate reasons to pay close attention to the proceeding.
How to establish a lost will in Florida
Florida has a specific procedure for establishing and admitting a lost or destroyed will. The process involves proving the document’s contents and giving the appropriate people an opportunity to participate.
The practical work usually begins before a petition reaches the court. A family that spends time gathering records and understanding the history of the document may be better prepared to address the questions that arise during the proceeding.
1. Search for the original before treating it as lost
Start with the obvious places, even if someone has already checked them once. Look through personal files, home safes, safe deposit records, and correspondence from the attorney who prepared the will.
Ask whether the deceased gave the original to someone for safekeeping. A relative might have been asked to store it during a move. The drafting attorney may have retained records that help explain which version was signed.
Keep a record of what was searched and what was found. This is useful for organizing the family’s efforts and may help explain the circumstances to counsel.
2. Preserve every version of the document
A photocopy may be the best available evidence, but it should not be the only thing the family considers.
Keep scans, drafts, correspondence, codicils, and related estate planning documents. Do not discard an older version just because someone believes a newer will existed. The older document may help establish the history of the estate plan, even if it ultimately cannot govern the estate.
A codicil deserves particular attention. It may amend a will without replacing the entire document, and its disappearance can create a separate problem when the court tries to determine the deceased person’s final instructions.
3. Identify witnesses who can establish the actual terms
The next task is to determine who can testify about the contents of the will. The answer may involve the drafting attorney or another person who has direct knowledge of the final document.
Remember that the law distinguishes between knowing the contents and simply remembering the signing. A person who watched the deceased execute the will may be unable to say what its provisions actually were.
Under § 733.207, the number of disinterested witnesses required depends on whether a correct copy is available. Establishing that the appropriate witnesses exist is an important part of assessing the case.
4. Investigate why the original disappeared
The family should be prepared to explain what is known about the original’s whereabouts. Was it last kept at home? Did an attorney retain it? Did the deceased move shortly before death? Were other people able to access the place where it was stored?
The answers may help clarify whether the presumption of revocation applies and what evidence is available to address it.
This is also a point where assumptions can become counterproductive. If the family suspects that someone removed the will, it should preserve relevant information and discuss the circumstances with counsel rather than presenting an unproven suspicion as an established fact.
5. File the petition and give formal notice
The petition must explain the basis for establishing the lost will and state its contents or include a copy when one is available. The proceeding must comply with the applicable evidentiary requirements.
Formal notice must be given to people who would inherit if the missing will were not admitted. This can include heirs who would receive property under Florida’s intestacy laws.
Notice is important because the court is not simply resolving a private disagreement between relatives. The outcome can affect the legal rights of people whose interests may conflict with those of the petitioner.
6. Present the evidence to the court
The court considers the evidence about the contents of the missing will and whether the document remained effective at death. Interested parties may challenge the petition.
If the court admits the will, the final order states its terms. The estate can then proceed under the established will, subject to the other requirements of Florida probate law.
A successful petition does not eliminate every issue that may arise during administration. Questions about assets, creditor claims, ownership, or the distribution of particular property may still need to be resolved.
What happens if the court cannot admit the missing will?
If the court cannot establish the missing will, the next step depends on whether another valid will exists and how the deceased’s property is owned.
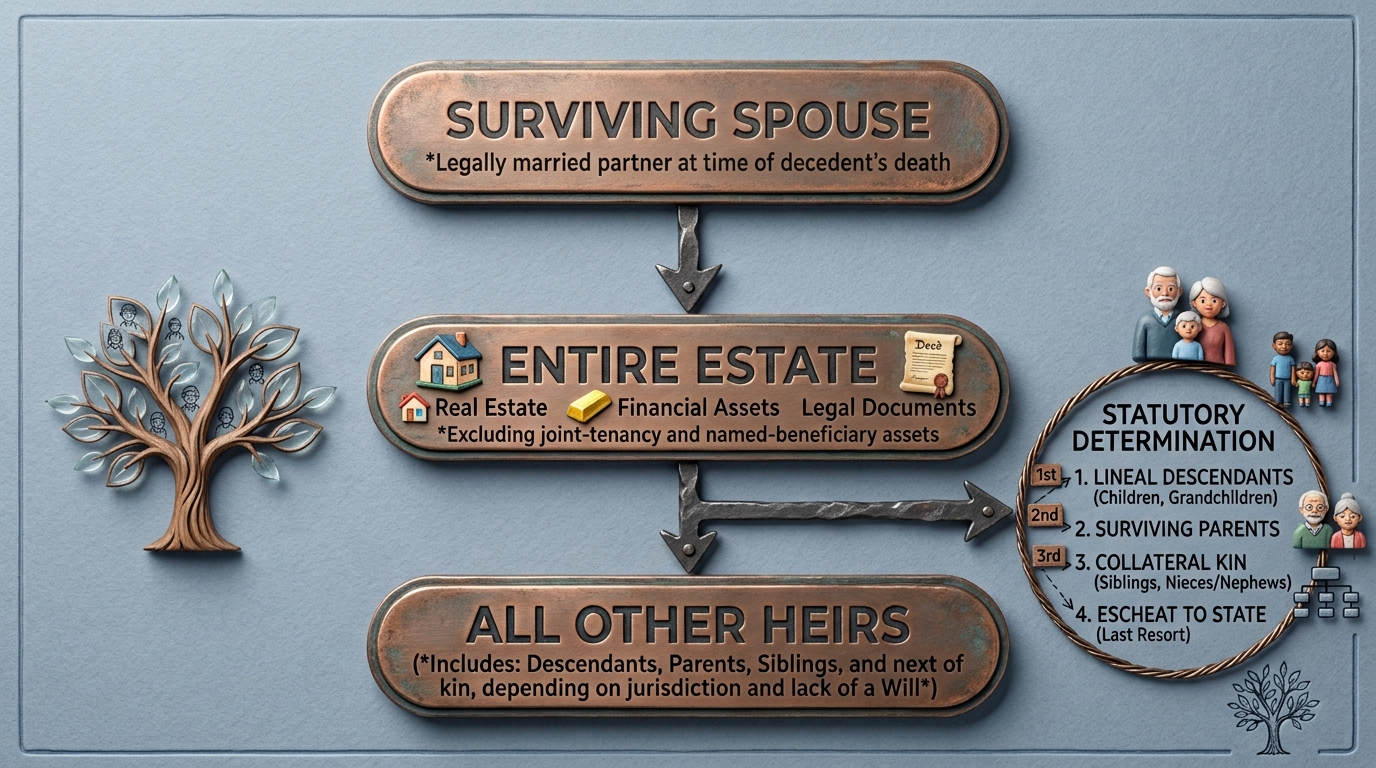
An earlier will may still be relevant. Some assets may also pass outside probate because of joint ownership or beneficiary designations. If no effective will governs the property, Florida’s intestacy rules generally determine who inherits it.
That can produce a result the deceased would not have chosen.
Imagine someone who intended to leave a house to a close friend while leaving other assets to relatives. If the missing will cannot be established, the friend may not receive the house under the rules that apply without an effective will. The actual outcome depends on the ownership arrangements and the applicable law.
It is important not to assume that every asset follows the same route. A will generally does not control property that passes automatically to another owner or beneficiary under a valid arrangement. The family may need to examine the title and beneficiary records before drawing conclusions about what is at stake.
For readers who want to understand the alternative, see MyPersonalAttorneys’ article on Florida intestate succession, which explains who may inherit when a person dies without an effective will.
What if someone finds the will after probate has started?
Sometimes the original turns up after the family has already begun the probate process. It might be discovered among old papers, in a storage box, or in records that were not available when the estate was opened.
Finding it can change the situation, but it does not automatically undo everything that has happened.
Florida Statutes § 733.208 addresses the discovery of a later will or codicil. It allows an interested person to petition concerning the later discovered document, subject to the statute’s requirements. It also restricts offering a will after the estate has been completely administered and the personal representative discharged.
The timing can be important. If a document is found after probate has begun, the family should not assume that it can simply be substituted for the will already being administered. Nor should anyone assume that a discovered document will necessarily change the outcome.
The appropriate response is to preserve the document and obtain legal advice promptly. Counsel can assess its status and explain what procedure may be available at that stage of the estate.
Common mistakes families make with a missing will
The law can be difficult enough without avoidable assumptions getting in the way. A few mistakes deserve particular attention.
Assuming a photocopy guarantees probate
A photocopy can help establish the contents, but the court must still apply the statutory requirements. The circumstances surrounding the original’s disappearance may raise a separate question about revocation.
Asking a beneficiary to prove the will
A person who expects to receive property under the document may not qualify as a disinterested witness. Even a close relative who remembers the deceased’s wishes may be unable to provide the required testimony.
Confusing the signing ceremony with proof of the contents
Someone may remember witnessing the will’s execution without knowing what it said. The law requires evidence of the document’s actual provisions, not simply proof that a signing occurred.
Treating suspicion as proof of interference
A missing will can create understandable mistrust. One relative may suspect another of taking the document, particularly when the inheritance would change significantly if the will were admitted.
The family should distinguish what it knows from what it suspects. Evidence about access, storage, and the document’s disappearance may be relevant, but an accusation alone does not establish what happened.
Waiting until the estate is almost finished
Families sometimes postpone dealing with a missing will because they expect the original to turn up eventually. That can be risky.
Section 733.208 restricts offering a will after the estate has been completely administered and the personal representative discharged. The applicable timing rules depend on the situation, so a family should not wait for a document to appear without understanding the potential consequences.
Why keeping a reliable copy matters
A missing will dispute is a good reminder that preparing an estate plan and preserving it are two different tasks.
A person may take considerable care when choosing beneficiaries and arranging their affairs, yet leave family members uncertain about where the final signed documents are kept. That uncertainty can create difficulties at precisely the moment when relatives are trying to settle the estate.
Keeping estate planning records organized and making sure the appropriate people know how to locate them can help. A copy stored securely with the drafting attorney may also prove useful if the original cannot be found.
Still, a copy is not a complete substitute for careful document management. The family needs to know which version was actually executed and whether a later will or codicil changed it.
The broader picture is worth considering, too. A 2025 Pew Research Center survey found that 32% of U.S. adults reported having created a will. That figure does not measure how often wills go missing, but it illustrates that many adults have not documented their wishes in a will at all.
For families who have already prepared a will, preserving the final version is a sensible next step. It may spare loved ones from having to reconstruct an estate plan from old emails, incomplete drafts, and conflicting memories.
When should you speak with a Florida probate attorney?
It is worth seeking legal advice if the original will cannot be located, if the available copy may not be the final version, or if relatives disagree about what happened to the document.
A probate attorney can review the evidence and assess whether the requirements for establishing the will may be met. The attorney can also help identify interested parties who must receive notice and evaluate whether the circumstances raise a question about revocation.
For families in Coral Springs and Broward County, it helps to gather the records already available before the first consultation. Bring any copies, drafts, correspondence with the drafting attorney, and information about where the original was last kept. Even documents that appear incomplete may help explain the history of the estate plan.
Frequently asked questions about missing wills in Florida
Can a photocopy of a will be used in Florida probate?
Yes. A correct copy may be used to establish the contents of a lost will if the statutory requirements are satisfied. Under § 733.207, one disinterested witness can establish the contents when a correct copy is available.
The copy does not automatically resolve whether the will remained valid at death. The circumstances surrounding the original’s disappearance may still matter.
Does Florida presume that a missing will was revoked?
Florida courts recognize a rebuttable presumption of revocation when an original will was last known to be in the testator’s possession and cannot be found after death. The presumption may be overcome with sufficient evidence, depending on the circumstances.
Can a family member testify about the contents of a lost will?
Potentially, provided the witness meets the legal requirements. The court considers whether the witness is disinterested and can establish the document’s precise terms.
A relative’s familiarity with the deceased’s wishes is not necessarily enough. The testimony must address what the will actually said.
What if the only document available is an unsigned draft?
An unsigned draft is not automatically a correct copy of an executed will. In In re Estate of Parker, the Florida Supreme Court distinguished an accurate draft from an identical reproduction of the missing document.
The draft may still provide useful evidence about the estate plan’s history. Whether it can help establish the will depends on the available evidence and the applicable legal requirements.
Do all heirs have to agree before a lost will can be admitted?
No. Unanimous agreement among heirs is not the statutory test. The proceeding must satisfy Florida’s evidentiary requirements, and formal notice must be given to people who would inherit if the will were not admitted.
Interested parties may challenge the petition if they dispute the document’s contents or continued validity.
What happens if the will is found after the estate has been distributed?
The answer depends on the stage of administration and the applicable law. Section 733.208 addresses later discovered wills and codicils, but it restricts offering a will after the estate has been completely administered and the personal representative discharged.
Anyone who discovers a will at this stage should seek legal advice promptly. The document’s discovery does not automatically reverse completed proceedings.
Is a lost will case the same as a will contest?
No. A lost will proceeding seeks to establish and admit a document that cannot be located. A will contest challenges a will’s validity on grounds such as lack of testamentary capacity or undue influence.
The issues can overlap. A dispute over a missing will may involve both the contents of the document and whether it remained effective at death.
Should I contact a probate attorney if I have a copy but not the original?
Seeking advice early is sensible, especially if the will affects a home or a substantial inheritance. An attorney can review the copy, assess the available evidence, and explain the procedure that may apply.
Final thoughts
A missing will can leave a family with an uncomfortable mixture of certainty and doubt. Everyone may remember that an estate plan existed, and someone may even have a copy. Yet the court still needs to determine what the document said and whether it remained legally effective.
Florida law provides a way to establish a lost or destroyed will, but the process depends on evidence rather than family recollection alone. The distinction between proving the contents and addressing possible revocation is often the most important part of the case.
For families in Coral Springs and throughout Broward County, the best place to start is with the documents and facts already available. A careful review can help clarify whether the missing will may still be admitted to probate and what steps are worth considering next.
Who inherits when someone dies without a will in Florida?
The answer depends on the decedent’s surviving relatives and on which property is actually part of the intestate estate. Under Florida Statute § 732.101, property that is not effectively disposed of by a will passes to the decedent’s heirs under Florida’s intestacy laws. The right to that intestate property vests at death.
Florida’s rules do not give every relative an inheritance claim. A surviving spouse may receive the entire intestate estate in some families, while the spouse receives one half when certain descendants or blended family circumstances exist. If no spouse inherits the property, Florida law turns to descendants, parents, siblings, and progressively more remote relatives according to the hierarchy in § 732.103.
Florida Intestate Succession Hierarchy Structure
That hierarchy can produce results that surprise families. A half sibling can receive a different share from a whole blood sibling. A child who died before the decedent can leave a branch of descendants who inherit under the per stirpes rule. An alleged heir may have to prove the claimed family relationship before receiving anything. A distant relative may discover that being biologically related to the decedent does not place that person within a statutory class of heirs.
Florida law also treats some property differently from ordinary intestate assets. A jointly owned asset may pass through survivorship rights. A trust can control property outside the probate estate. A beneficiary designation can determine who receives certain financial assets. Florida homestead has its own inheritance rules that can change the analysis when a surviving spouse and descendants are involved.
The result is a legal question with several layers:
Who qualifies as an heir?
What share does that heir receive?
Is the property subject to intestate succession at all?
Those questions become particularly important when a Florida estate involves a blended family, disputed heirship, distant relatives, or a home owned by the decedent.
What Is Intestate Succession in Florida?
Intestate succession is the statutory process used to determine who inherits property that a Florida decedent did not effectively dispose of through a will.
Florida’s principal intestacy rules appear in Part I of Chapter 732 of the Florida Statutes. The provisions address the intestate estate, the surviving spouse’s share, the shares of other heirs, per stirpes inheritance, half blood relatives, afterborn heirs, escheat, adopted persons, children born outside marriage, and termination of parental rights.
The term therefore has a narrower legal meaning than “everything a person owned when they died.”
A person can die without a will while some assets pass through another legal mechanism. The intestacy statutes become relevant to property that remains subject to the statutory inheritance scheme.
Can someone have a will and still have an intestate estate?
Yes.
Florida Statute § 732.101 applies when part of an estate has not been effectively disposed of by will. A person can therefore leave a valid will while some property passes to heirs under intestate succession.
This is known as partial intestacy.
For example, a will might dispose of several assets but fail to provide an effective disposition for a particular piece of property. That property can pass under the intestacy statutes even though the decedent left a will.
That distinction matters throughout probate.
The relevant question is not simply whether a document called a will exists. The question is whether the will effectively disposes of the property at issue.
What Is Intestate Succession in Florida?
Florida intestate succession is the legal system that determines who receives property when a person dies without an effective will. Under Florida Statute § 732.101, property that is not effectively disposed of by a will passes to the decedent’s heirs under the intestacy statutes. The heirs’ rights to that intestate property vest at death.
The absence of a will does not mean that the estate has no legal rules governing inheritance. It means the legislature has supplied those rules.
Florida Statute § 732.102 addresses the surviving spouse. Section 732.103 determines who inherits the remaining estate when there is no surviving spouse or when the spouse does not receive the entire intestate estate. The result depends heavily on the decedent’s family relationships at the time of death.
That distinction matters because intestate succession applies only to property that actually belongs in the intestate estate. A person can die without a will while some assets pass through another legal mechanism. The ownership structure or beneficiary designation attached to an asset may determine what happens to it without applying the intestacy hierarchy.
Which Property Is Subject to Intestate Succession?
The first question in an intestate estate is not simply who the relatives are. It is whether the particular property passes through intestacy at all.
Florida Statute § 732.101 applies to property that was not effectively disposed of by will. This can include property that the decedent owned individually and that does not have another valid method of passing at death.
An asset may therefore fall outside the intestate estate because of the way it was owned or because another legal arrangement controls its transfer. For example, property held with another person in a form that carries a right of survivorship may pass to the surviving owner. Certain accounts and insurance policies may pass according to a valid beneficiary designation.
This distinction becomes particularly important when someone says that a deceased relative had “no will.” The absence of a will does not automatically mean that every asset must be divided under Chapter 732.
It is possible to have an estate with both intestate property and property that passes outside intestacy.
That situation is sometimes called partial intestacy. A will may also create partial intestacy if it fails to dispose effectively of some property. Florida law addresses the property that remains undisposed of through the intestacy statutes.
Who Inherits First Under Florida Intestacy Law?
The surviving spouse receives special treatment under Florida law.
If the decedent leaves no surviving descendants, the surviving spouse receives the entire intestate estate. The same result generally applies when every surviving descendant is also a descendant of the surviving spouse and the spouse has no descendant from another relationship.
The result changes when the family structure is different.
If the decedent has a surviving descendant who is not also a lineal descendant of the surviving spouse, the spouse receives one half of the intestate estate. The other half passes according to the rules governing the decedent’s descendants.
Florida law also addresses a less obvious blended family situation. Even if every surviving child of the decedent is also the spouse’s child, the spouse receives one half when the spouse has a descendant from another relationship who is not a descendant of the decedent.
Example: A Married Person With Children From Another Relationship
Suppose Maria dies without an effective will. She leaves a husband and two children. Both children are also her husband’s children.
If her husband has another child from a previous relationship, the statute treats the family differently from a marriage in which the surviving spouse has no children outside the marriage.
Under § 732.102, Maria’s husband receives one half of the intestate estate. The remaining half passes under the rules for Maria’s descendants.
This is one reason a simple statement such as “the spouse inherits everything” can be legally misleading.
What Happens If There Is No Surviving Spouse?
When there is no surviving spouse, Florida Statute § 732.103 supplies the succession rules.
The estate first passes to the decedent’s descendants. If the decedent has no descendants, the statute moves to the parents.
In some cases if neither parent survives, the statute reaches the decedent’s brothers and sisters and the descendants of deceased siblings.
If those relatives do not exist, the statute moves farther into the family tree. Florida divides this stage between the decedent’s paternal and maternal kindred. Grandparents receive priority within those branches. If the relevant grandparents are not living, the statute addresses aunts and uncles and the descendants of deceased aunts and uncles.
The statute does not continue indefinitely through every person who can establish some biological connection to the decedent.
That limitation became important in a recent Broward County case.
How Far Does Florida Intestacy Law Reach?
In State of Florida, Department of Legal Affairs v. Estate of Kyle William Bruening, the Fourth District Court of Appeal considered an intestate estate involving distant relatives.
Kyle Bruening died without a will. No spouse or children survived him. His parents and grandparents had also died, and there were no surviving siblings or aunts and uncles within the categories recognized by the statute. Several distant relatives claimed the estate because they shared great grandparents with Bruening.
The trial court treated those relatives as heirs. The Fourth District reversed.
The appellate court held that sharing great grandparents with the decedent did not place those relatives within a class of heirs recognized by § 732.103. The court explained that the statute identifies the relatives who inherit through intestacy and does not create a general right of inheritance for every distant blood relative.
The case arose in Broward County, which makes it particularly relevant to probate disputes in Coral Springs and elsewhere in South Florida.
The practical point is straightforward. A family connection is not enough by itself. The relationship must fall within a category recognized by Florida intestacy law.
What Does Per Stirpes Mean in Florida?
Florida Statute § 732.104 provides that intestate descent is per stirpes. The rule applies to descendants and to collateral heirs.
The concept becomes important when an heir who would have inherited directly has already died.
Consider a decedent who has two children. One child survives the decedent. The other child died before the decedent but left two children of their own.
The surviving child does not simply take the entire estate. The deceased child’s branch remains relevant. The descendants of that deceased child can receive the share attributable to that branch under the per stirpes rule.
This can produce a different result from dividing an estate equally among every living descendant. Florida law preserves the deceased heir’s branch when the statute reaches that branch of the family.
A family tree can therefore matter at several generations.
Can One Side of the Family Receive the Entire Estate?
Yes.
People sometimes miss this point because they assume that intestate property must always be divided equally between the maternal and paternal sides of the family.
Section 732.103 does not require that result when one side has no qualifying heirs.
In Faskowitz v. Department of Legal Affairs, the decedent had no surviving descendants. His will had attempted to leave his property to his wife, but she died before him and the will did not provide an alternate beneficiary. Relatives on the paternal side established their status as heirs. The probate court had treated half of the property as potentially belonging to unknown maternal relatives.
The Second District Court of Appeal rejected that approach. Under § 732.103, if there is no qualifying kindred on one side, the surviving kindred on the other side can receive the entire estate.
The case demonstrates why determining heirship requires more than locating one relative and assuming the estate will be divided along a simple family line.
What Happens If Family Members Disagree About Who Is an Heir?
Disputes over family relationships can easily turn an intestate estate contentious.
Florida Statute § 733.105 allows an interested person to ask the probate court to determine who is entitled to receive property or what share a person should receive when there is doubt about the proper beneficiaries.
That proceeding can require evidence about the decedent’s family history.
The Florida Supreme Court addressed this problem in State v. Rudawski, a case involving the estate of Jacob Tim. Tim died intestate in Miami Beach. More than fifty people appeared claiming different degrees of relationship to him. The court ultimately held that the claimants had failed to establish their entitlement to the estate.
The case illustrates a basic probate principle that can become decisive in an intestate estate: a person claiming inheritance must establish the legal basis for that claim.
A surname is not enough. A family story is not enough. The evidence must establish the relationship required by the applicable law.
Do Adopted Children Inherit Under Florida Intestacy Law?
Yes. Florida law generally treats an adopted person as a descendant of the adopting parent for purposes of intestate succession.
Section 732.108 provides that an adopted person becomes a descendant of the adopting parent and a member of that family for intestate succession purposes. The statute also contains specific exceptions involving certain adoptions by a natural parent’s spouse and other family relationships.
The details can matter when an adoption changes the legal relationship between the child and the natural family.
For that reason, a probate court may need to examine the adoption itself rather than relying on a family description used informally during the decedent’s lifetime.
What Happens With a Half Sibling?
Florida has a specific rule for half blood relatives.
When property passes to collateral relatives and some are related to the decedent by whole blood while others are related by half blood, the half blood relatives receive half as much as the whole blood relatives. If all of the relevant collateral relatives are half blood relatives, they receive equal shares.
This rule can matter when an estate reaches the sibling portion of the intestacy hierarchy.
For example, assume an intestate estate reaches the decedent’s siblings. When a surviving full sibling and a surviving half sibling both inherit, the statute does not automatically give them equal shares.
Therefore, you should calculate the shares under § 732.105 rather than treating every sibling as having the same statutory relationship.
Can a Child Born After the Parent’s Death Inherit?
Florida law expressly addresses this situation.
Under § 732.106, an heir who was conceived before the decedent’s death but born afterward inherits intestate property as though the child had been born during the decedent’s lifetime.
The timing of the birth therefore does not by itself eliminate the child’s inheritance rights.
Other legal questions can arise when parentage is disputed. Those questions should be addressed under the statutes governing the particular relationship rather than assumed from the family’s understanding of who the child’s parent was.
What Happens to a Florida Homestead When There Is No Will?
Florida homestead property requires separate attention because constitutional protections and Florida statutes impose special rules.
Section 732.401 provides that homestead generally descends under the intestacy rules when it has not been validly devised. When the decedent leaves a surviving spouse and descendants, however, the surviving spouse receives a life estate with a vested remainder in the descendants who were living at the decedent’s death. The spouse may instead elect an undivided one half interest as a tenant in common, with the remaining half passing to the descendants per stirpes.
This means a family home cannot always be treated like an ordinary asset in an intestate estate.
A surviving spouse may have rights that differ substantially from the result produced by simply dividing the home according to the general intestacy hierarchy.
The homestead rules also make property ownership particularly important. Before assuming that a house must be distributed through intestacy, the probate lawyer must determine how the property was titled and whether Florida’s homestead protections apply.
Can Intestate Succession Create Problems With a Family Home?
Yes.
Suppose a person dies in Coral Springs without a will and leaves a house to several descendants. Those heirs may acquire ownership interests in the property rather than receiving an automatic cash distribution.
The situation can become difficult when one heir wants to sell and another wants to keep the property. The heirs may also disagree about maintenance or the use of the house.
The problem can become larger with later deaths. An heir who receives an interest can later die without a will, causing that interest to pass through another estate. Over time, ownership can become divided among a growing number of relatives.
This is one reason intestate succession can have consequences long after the initial probate administration.
What Happens If No Legal Heir Can Be Found?
Florida law provides for escheat when a person dies without leaving anyone entitled to the estate.
Under § 732.107, property that has no person entitled to receive it can escheat to the State of Florida. The statute provides a procedure for handling the property and permits a person with a valid claim to seek the proceeds within the statutory period.
Escheat is not the first step merely because relatives are difficult to locate.
The question is whether a person legally entitled to inherit exists under the applicable statutes. Bruening demonstrates that a court will not expand the statutory categories simply because a distant relative can establish a biological connection.
Faskowitz demonstrates the other side of the problem. When qualifying heirs exist on one side of the family, the absence of qualifying heirs on the other side does not automatically send half the estate to the State.
Who Handles an Estate When There Is No Will?
An intestate estate still requires administration.
Florida law establishes a preference for appointment as personal representative in an intestate estate. The surviving spouse has the first preference. The statute then addresses selection by the heirs and the heir nearest in degree.
The personal representative is responsible for administering the estate under Florida probate law.
That role does not give the representative ownership of the estate. The representative administers property that belongs to the estate and distributes it according to the law after the required probate process has been completed.
A dispute over who should serve as personal representative can therefore be separate from a dispute over who inherits.
What If Nobody Knows Exactly Who the Heirs Are?
Florida provides a court procedure for this problem.
Under § 733.105, an interested person can petition the probate court to determine the beneficiaries or their respective shares when property passes through intestate succession and there is uncertainty about entitlement.
This can become relevant when relatives have incomplete records or when different family members provide conflicting accounts of the decedent’s family history.
The evidence may include civil records and other documentation establishing the claimed relationship. In a difficult estate, a genealogical investigation may also become necessary.
The objective is not to identify every person who might be related to the decedent. The objective is to establish the relatives who fall within the statutory categories of heirs.
What If the Person Had a Will That Did Not Cover Everything?
A person does not have to die completely intestate for the intestacy statutes to matter.
Section 732.101 applies to any part of an estate that was not effectively disposed of by will.
Imagine a will that leaves a particular bank account to one beneficiary but does not effectively dispose of the remainder of the estate.
The undisposed property can pass under Florida intestacy law.
This distinction matters when reviewing an older will after a death. The question is not simply whether the decedent signed a document called a will. The question is whether that document actually controls the property now at issue.
Why Intestate Succession Can Produce Surprising Results
Florida intestacy law follows statutory categories rather than the family’s idea of what would have been fair.
A decedent may have been especially close to a niece while having little contact with a sibling. That does not allow the niece to inherit simply because the relationship was closer.
A person may have supported one child financially during life while providing little support to another. Intestacy law does not generally adjust the statutory inheritance share because the family considers one relationship stronger.
The statute applies the legal relationships recognized by the Probate Code.
That is why the consequences can feel unexpected when a family has never discussed estate planning.
What Should a Family Do After Someone Dies Without a Will?
The first step is to determine what property actually belongs in the probate estate.
The next question is who may have inheritance rights under Florida law. That inquiry should account for the surviving spouse and the decedent’s descendants before moving farther into the family tree.
The family should also determine whether the decedent owned a Florida homestead. That property can be subject to special rules that change the ordinary intestacy analysis.
If relatives disagree about heirship, the probate court can determine who is entitled to the property and what share each person should receive. Section 733.105 specifically provides a procedure for resolving that uncertainty.
In Coral Springs and elsewhere in Broward County, these questions can arise in estates involving a family home, multiple generations, or relatives who have lived in different states for many years.
Waiting can make the factual investigation harder. Birth records may be difficult to locate. Family members may have incomplete information. Property may remain titled in the decedent’s name while relatives disagree about what should happen next.
A Florida probate attorney can review the ownership records and family relationships against the applicable statutes before the estate is distributed.
Frequently Asked Questions About Florida Intestate Succession
Who inherits if someone dies without a will in Florida?
The answer depends on the decedent’s surviving relatives and the property involved. A surviving spouse may receive the entire intestate estate or one half, depending on the family structure. If no spouse survives, descendants generally take priority under § 732.103.
Does the oldest child inherit more under Florida intestacy law?
No. Age does not give the oldest child a larger intestate share. When descendants inherit directly, Florida applies its statutory distribution rules.
Does a surviving spouse always inherit everything?
No. The surviving spouse receives the entire intestate estate in several situations, but § 732.102 reduces the spouse’s share to one half in specified family structures involving descendants.
Do grandchildren inherit if their parent is alive?
Generally, the inheritance hierarchy reaches the decedent’s descendants directly before moving to more remote relatives. The per stirpes rule becomes particularly important when a descendant who would have inherited has already died.
Can a niece or nephew inherit from an aunt or uncle who dies without a will?
A niece or nephew may inherit when the intestacy hierarchy reaches the descendants of a deceased sibling. The exact result depends on which relatives survive the decedent and how the statutory branches apply.
Can a second cousin inherit under Florida intestacy law?
Usually not merely because the person is a second cousin. In Bruening, the Fourth District held that relatives who shared great grandparents with the decedent did not fall within the statutory class of heirs applicable to that estate.
Do adopted children inherit from their adoptive parents?
Yes. Florida generally treats an adopted child as a descendant of the adopting parent for intestate succession. The statute contains specific exceptions that can affect relationships with natural family members.
Does a half sibling inherit the same amount as a full sibling?
Not always. When the relevant collateral heirs include both whole blood and half blood relatives, Florida law gives a half blood relative half the share of a whole blood relative.
What happens to a Florida house when the owner dies without a will?
The answer depends on the ownership of the property and the circumstances of the family. Florida homestead law contains special inheritance rules when a surviving spouse and descendants exist.
Can the State of Florida inherit an intestate estate?
Yes, but only when the statutory conditions for escheat are satisfied. If someone legally entitled to the estate exists under Florida law, the property does not simply pass to the State because the family is difficult to identify.
What if family members disagree about who should inherit?
An interested person can ask the probate court to determine who is entitled to the property or what share each person should receive. Florida Statute § 733.105 provides the procedure for that determination.
Florida Intestate Succession Requires a Property and Family Analysis
Dying without a will does not leave an estate without rules. Florida law supplies a statutory inheritance system that begins with the surviving spouse and descendants before reaching more remote relatives.
The difficult cases arise when the family structure is complicated or the property does not fit neatly into the ordinary probate estate. Homestead property can require a separate analysis. A distant relative may have a biological connection without having a statutory right to inherit. A surviving relative on one side of the family may receive the entire estate when the other side has no qualifying heirs.
For families in Coral Springs and Broward County, an intestate estate should be examined under the current Florida statutes before property is distributed. The right heir may not be the person the family expects, and the property that appears to belong to the estate may not all be subject to intestate succession.
Do You Have to Pay a Deceased Parent’s Debts in Florida?
No. In Florida, children generally do not have to pay a deceased parent’s debts from their own money simply because they are family members. Valid debts are usually paid from the deceased parent’s estate during probate. If the estate lacks sufficient assets, unpaid debts do not automatically become the children’s personal responsibility.
The estate: Generally pays valid debts from available estate assets.
The personal representative: Handles creditor claims and pays debts according to Florida probate law.
The children or other heirs: Generally are not personally liable unless a separate legal obligation applies.
Secured creditors: May retain rights against property securing a debt, such as a mortgaged home.
When must you pay a deceased parent’s debt?
You may be personally responsible if you:
Co-signed a loan or other credit agreement.
Are legally liable for a joint credit account.
Separately agreed to assume the debt.
Received an improper estate distribution that you may be legally required to return.
Inheriting property does not automatically make you personally responsible for every debt your parent owed. However, a mortgage or another valid lien may remain attached to inherited property.
If a credit card company, hospital, or debt collector contacts you after your parent’s death, determine whether the claim is against the estate or against you personally. A demand for payment does not, by itself, establish that you owe the debt.
Who Pays a Parent’s Debts After Death?
In most cases, the deceased person’s estate is responsible for valid debts. The estate consists of assets and property available to settle the deceased person’s affairs under the applicable law.
When a Florida probate case is opened, the personal representative is responsible for administering the estate. This includes identifying assets, reviewing creditor claims, paying obligations in the legally required order, and distributing any remaining property to beneficiaries.
The personal representative does not automatically become personally liable for the deceased person’s debts. Their role is to handle the estate according to Florida law.
Consider a parent who dies with $25,000 in credit card debt and leaves $10,000 in available estate assets. The credit card company may seek payment from the estate, but the deceased person’s child does not automatically owe the remaining $15,000. If the estate cannot cover all its valid debts, some creditors may receive partial payment or nothing at all.
This is the general rule described by the Federal Trade Commission. The important exceptions arise when a relative has an independent legal obligation or when estate property has been handled improperly.
When Can You Be Personally Responsible for a Parent’s Debt?
Your relationship with the deceased does not ordinarily make you responsible for their debts. Certain financial arrangements, however, can create personal liability.
You co-signed a loan
If you co-signed your parent’s car loan or personal loan, you may remain responsible for the balance after their death. Your obligation comes from the agreement you signed, not from being their child.
Review the contract before assuming you owe the balance. If a creditor claims you co-signed an account and you dispute that assertion, ask for documentation supporting its position.
You were a joint account holder
A person who is legally responsible for a joint credit account may remain liable after the other account holder dies. That situation differs from being an authorized user on someone else’s credit card. An authorized user generally does not become responsible for the debt solely by having permission to use the account.
If a collector says you owe the balance, ask which agreement or account status creates that obligation.
You agreed to assume the debt
You may have a separate obligation if you signed a contract or made an enforceable agreement to pay the debt. Helping a parent manage their finances, handling paperwork after their death, or being named in their will does not by itself establish personal liability.
This distinction matters when a family member has been helping with a parent’s care or finances for years. Managing someone else’s bills is not the same as agreeing to become the borrower.
You mishandled estate assets
A separate issue arises if you receive money from an estate before the applicable debts and expenses have been addressed.
Florida Statutes § 733.812 allows recovery of certain improper distributions. Depending on the circumstances, a beneficiary may have to return property or funds distributed improperly. A personal representative may also face liability for failing to perform their legal duties.
That does not mean every mistake makes a child responsible for all a parent’s debts. It does mean that anyone distributing estate property should understand which claims must be addressed first.
What Happens If the Estate Cannot Pay All Its Debts?
When an estate has insufficient assets to pay every valid claim, Florida law determines which obligations receive payment first.
Under Florida Statutes § 733.707, estate expenses and obligations are divided into statutory priority classes. Administration expenses come first, followed by specified funeral and interment expenses. Other categories include certain preferred debts and taxes, qualifying medical expenses from the final illness, and other claims.
Ordinary unsecured debts generally fall behind claims with higher statutory priority. If the estate cannot pay all claims within a class, the available funds may have to be distributed proportionately among those claims.
For example, suppose a parent leaves a small bank account but owes substantially more than the account contains. The personal representative cannot necessarily pay whichever creditor calls first. They must evaluate the claims and follow the applicable payment priorities.
An estate with insufficient funds does not automatically pass the shortfall to the children. The result depends on the assets available, the claims filed, and any separate legal obligations held by family members.
For families in Broward County, this is one reason to be cautious about paying a creditor immediately just because it demands payment. The estate’s financial position and the applicable priorities need to be reviewed first.
How Long Do Creditors Have to Claim a Debt in Florida?
Florida law establishes deadlines for claims against a deceased person’s estate. Missing the applicable deadline can prevent a creditor from enforcing its claim against the estate.
Under Florida Statutes § 733.702, the usual deadline is three months after the first publication of the notice to creditors. For a creditor required to receive individual service, the deadline is generally 30 days after service if that date falls later.
A separate provision, § 733.710, generally bars claims against the estate, personal representative, and beneficiaries two years after the person’s death, subject to the statute’s exceptions. It also preserves certain recorded mortgages and security interests.
These deadlines should not be treated as interchangeable. The relevant dates, the creditor’s status, and the type of claim can affect the result. A creditor who was known or reasonably ascertainable but did not receive required notice may raise a different legal issue from one that had proper notice.
If you are administering an estate, keep records of creditor communications and obtain legal advice before deciding that a claim is too late to matter.
Can a Debt Collector Make You Pay Your Parent’s Bills?
A debt collector cannot make you personally responsible for a parent’s debt simply by demanding payment. If you did not co-sign the obligation, become legally responsible for the account, or otherwise incur liability, being the deceased person’s child is generally not enough.
Federal law also restricts how debt collectors communicate about deceased consumers’ debts. Collectors may contact certain people to locate the person authorized to administer an estate. That does not give them permission to misrepresent who owes the money.
If a collector insists that you must pay, ask for the legal basis of that claim. Keep copies of letters and messages, and make a record of calls where appropriate. If the collector threatens to sue you personally, or continues to demand payment despite a clear dispute about your liability, consider seeking legal advice.
Do You Have to Use Your Inheritance to Pay a Parent’s Debts?
Not necessarily. The answer depends on how the property passes to you, whether it is available to satisfy estate claims, and whether a lien or another legal obligation applies.
Some assets pass directly to a named beneficiary rather than through the ordinary probate process. Life insurance with a valid beneficiary designation is a common example. Other assets may be part of the probate estate and subject to its administration.
The distinction is important, but it does not mean that every asset passing outside probate is automatically protected from every creditor. Florida law includes specific rules governing creditor claims, trusts, and exempt property. The result can depend on the ownership arrangement and the type of asset involved.
If you expect to receive money or property from a parent’s estate, establish how the asset passes before assuming that it must be used to pay a debt—or that creditors have no possible claim against it.
What If You Inherit a House With a Mortgage?
Inheriting a home does not necessarily eliminate the mortgage or another valid lien attached to the property. A lender may retain enforcement rights even after the borrower dies.
Florida’s two-year limitation on certain estate claims expressly preserves specified recorded mortgages and security interests. A deadline that bars an ordinary claim does not automatically remove a mortgage lien.
The property’s status under Florida homestead law can also affect the probate process and the rights of surviving family members. Protected homestead property is treated differently from other estate assets. Whether a particular home qualifies depends on the facts and applicable legal requirements.
Before selling, transferring, or making major financial decisions about an inherited home, determine whether a mortgage or another lien remains in place. It is also important to establish how ownership passes and whether any homestead protections apply.
Can Creditors Take Money From a Living Trust?
A living trust does not automatically make every asset unavailable to creditors after the person who created it dies.
Florida Statutes § 736.0505 addresses creditor claims against a trust settlor. The law generally makes property in a revocable trust subject to the settlor’s creditors during the settlor’s lifetime to the extent the property would not otherwise be exempt if owned directly. Florida probate law also contains provisions addressing certain trust assets when the probate estate is insufficient to pay expenses and obligations.
The outcome depends on the trust’s terms, the assets it holds, applicable exemptions, and the circumstances of the estate. A trust can affect how property is transferred and administered, but its existence alone does not establish that creditors have no rights.
If your parent used a revocable living trust, review the trust documents and determine whether any statutory obligations apply before assuming the assets are beyond the reach of valid claims.
Are There Special Rules for Medicaid and Medical Debts?
Medical bills are generally handled as claims against the deceased person’s estate. A child does not automatically become responsible for a parent’s medical expenses simply because they are related.
Florida also has a Medicaid Estate Recovery Act. Under Florida Statutes § 409.9101, the state may pursue recovery for qualifying Medicaid assistance provided after the recipient reached age 55, subject to applicable federal and state requirements.
The law contains exceptions and protections. The type of property involved can also affect whether recovery is available. If the estate received Medicaid benefits, or if a substantial medical claim appears after a parent’s death, it is worth determining exactly what kind of claim has been made.
A private medical bill and a Medicaid estate recovery claim are not the same thing. Each must be assessed under the rules that apply to it.
What Should You Do Before Paying a Parent’s Debt?
If a creditor contacts you after a parent’s death, take a moment to establish what is being requested and why.
Find out who owes the money. Ask whether the creditor is making a claim against the estate or alleging that you are personally liable.
Review any agreement you signed. A co-signed loan or joint credit obligation may create liability that a family relationship alone would not.
Keep estate money separate from your own. If you are the personal representative, do not distribute estate assets or pay selected creditors before understanding the applicable probate rules.
Do not ignore formal notices. A demand letter is different from a court document. If you receive legal papers, pay attention to the stated deadlines.
If the claim is disputed, the estate has limited assets, or an inherited home is involved, get advice before committing your own money. A payment made under pressure can complicate an already difficult situation.
When Should You Speak With a Probate Attorney?
Legal guidance can be especially useful when the estate has insufficient assets, a creditor disputes the handling of its claim, or family members disagree about whether property should be sold or distributed.
An attorney can review the estate’s assets and liabilities, determine which creditor deadlines apply, and help the personal representative follow Florida’s payment priorities. Advice may also be necessary when a family home is involved or a trust holds substantial property.
Families in Coral Springs and elsewhere in Broward County may need to determine which assets are available to pay creditors, whether a claim was filed on time, and whether an heir has any personal responsibility for the balance. A probate attorney can review those questions under Florida law before the family pays a disputed debt or distributes estate property.
Children generally do not become personally responsible for a parent’s debts simply because the parent dies. Valid debts are usually handled through the estate, although a child may be liable under a separate agreement, such as a co-signed loan.
Can a credit card company make me pay my deceased parent’s credit card debt?
Generally, no, unless you have an independent legal obligation, such as liability as a joint account holder or under a separate agreement. The company may still submit a valid claim against the parent’s estate through the applicable probate process.
What happens if my parent dies with more debt than assets?
The estate’s assets are used to pay valid claims according to Florida’s statutory priorities. If the estate cannot pay every claim, lower-priority creditors may receive partial payment or nothing. A child does not automatically have to cover the shortfall with personal funds.
Do I have to use my inheritance to pay my parent’s debts?
Not automatically. The answer depends on whether the asset is part of the probate estate, how it passes to you, and whether any lien or other legal obligation applies. Some assets pass directly to beneficiaries, but that does not guarantee protection from every creditor claim.
Can I keep my parent’s house if they still owe a mortgage?
Possibly, but inheriting the house does not automatically remove the mortgage. The lender may retain rights against the property. The outcome depends on the loan, the property’s ownership and homestead status, and the circumstances of the inheritance.
How long do creditors have to claim a debt after someone dies in Florida?
The usual probate claim deadline is three months after the first publication of the notice to creditors. For a creditor entitled to individual service, the deadline is generally 30 days after service if that date falls later. Florida also has a separate two-year limitation measured from death, subject to statutory exceptions. The correct deadline depends on the claim and the circumstances.
Can I be sued for distributing my parent’s money before paying creditors?
Potentially. If you receive an improper distribution from an estate, Florida law may permit recovery of the property or funds. A personal representative may also face consequences for failing to follow their legal duties. The outcome depends on the facts and the applicable statutes.
Does a living trust protect my parent’s assets from creditors?
Not automatically. Florida law allows certain creditor claims involving revocable trusts, and some trust assets may be subject to estate obligations when probate assets are insufficient. The trust documents and applicable law must be reviewed to determine what protections exist.
Can Florida Medicaid recover money after a parent dies?
In some cases. Florida’s Medicaid Estate Recovery Act allows recovery for qualifying Medicaid assistance provided after the recipient reached age 55, subject to legal requirements and exceptions. Whether recovery can be made from particular property depends on the facts and applicable protections.
This article provides general information about Florida law and is not legal advice for a specific estate or debt. Deadlines, exemptions, and personal liability depend on the facts of the case.
Yes. An estate plan can keep an asset out of probate while creating a different problem involving ownership, inheritance, control, or family disputes.
Joint accounts, beneficiary designations, trusts, and survivorship ownership can all be useful estate-planning tools. Problems arise when one of those arrangements is created without considering how it fits with the rest of the estate plan.
A person may add a child to a bank account because the child will receive it automatically at death. Someone else may name a beneficiary on a retirement account and never update it. A homeowner may add a child to a deed to make a future transfer easier.
Each decision can accomplish its immediate purpose. It can also produce an unintended result elsewhere.
When Probate Avoidance Changes the Intended Inheritance
The central problem is coordination.
Suppose a parent wants three children to inherit equally. The will reflects that intention, but one child is the beneficiary of a bank account, another is the beneficiary of a life insurance policy, and the house is jointly owned with the third.
The probate estate may then tell only part of the story.
Florida recognizes numerous arrangements that allow assets to pass outside probate. Some nonprobate assets can nevertheless remain relevant for other estate-planning purposes. For example, Florida’s elective-share statute includes certain payable-on-death, transfer-on-death, in-trust-for, and survivorship accounts when calculating a surviving spouse’s elective estate.
Avoiding probate and determining who should ultimately receive an estate are therefore separate questions.
Can Adding Someone to a Bank Account Cause an Inheritance Problem?
It can.
Adding a child or other person to an account may be intended to provide convenience during the owner’s lifetime or allow the account to pass automatically at death.
But joint ownership can affect both control and inheritance.
The Florida Bar warns that joint ownership can produce unintended consequences involving creditor exposure, unequal treatment of heirs, estate expenses, and other issues.
For example, a parent might add one child to an account because that child helps manage the parent’s finances. If the account carries survivorship rights, the arrangement may also determine who receives the money when the parent dies.
That result may be completely different from an intention to divide the estate equally among several children.
Can a Beneficiary Designation Conflict With a Will?
Yes.
A beneficiary designation can determine who receives certain assets without the asset passing through probate.
That can be useful until an old designation conflicts with a later estate plan.
Suppose someone signs a new will leaving the estate equally to two children. A retirement account still names one child as the sole beneficiary.
The new will does not necessarily change that beneficiary designation.
Beneficiary designations should therefore be reviewed whenever the overall estate plan changes and after major life events such as marriage, divorce, or the death of a beneficiary.
What If I Create a Trust but Forget to Transfer an Asset?
A trust document does not automatically place every asset into the trust.
If someone creates a revocable trust intending for it to hold an investment account, but the account remains solely in that person’s individual name, the trust may not control the account simply because the trust document says it should.
The same issue can arise with real estate, business interests, and other significant property.
The planning documents and ownership records need to match.
Can Putting a Child on Your House Cause Problems?
It can.
Adding a child to real estate can affect ownership and control during the parent’s lifetime as well as what happens after death.
The parent may have intended to make the eventual transfer easier. Instead, the arrangement can create a co-ownership relationship that affects decisions about selling, refinancing, or managing the property.
Florida homestead adds another layer of rules. Florida law places restrictions on the devise of homestead when a surviving spouse or minor child is involved, and separate provisions address certain lifetime transfers.
An ownership change intended to avoid probate therefore needs to be considered under the homestead rules as well.
What Happens When Estate Documents Disagree?
Consider a simple example:
The will divides the estate equally among three children.
A bank account names Child A as beneficiary.
A life insurance policy names Child B.
The house is jointly owned with Child C.
A trust was created to hold the house, but the deed was never transferred to the trust.
There is no single document explaining the entire estate.
Each asset may have its own transfer mechanism. The family may then have to determine which arrangement controls each asset and whether any of them create additional legal rights.
The underlying problem is coordination.
Should Every Asset Be Arranged to Avoid Probate?
No.
Some assets may appropriately pass through probate. Others may be better handled through a trust, beneficiary designation, survivorship arrangement, or another structure.
The useful planning exercise is to identify the major assets, determine how each is currently owned, and ask how each will pass at death.
Then compare that result with the intended distribution.
That review can reveal inconsistencies before they become disputes.
Avoiding Probate in Coral Springs and Broward County
For families in Coral Springs and Broward County, these issues can arise when an estate includes a Florida homestead, investment accounts, business interests, jointly owned property, or multiple beneficiaries.
They can also arise when someone moves to Florida with estate documents and account arrangements created years earlier in another state.
A will, trust, beneficiary designation, deed, and account title can each serve a legitimate purpose. Problems arise when they produce different results.
Frequently Asked Questions
Can avoiding probate cause problems?
Yes. Probate avoidance can create unintended ownership, inheritance, control, or family issues if the arrangement is inconsistent with the rest of the estate plan.
Can adding someone to my bank account change who inherits the money?
Yes. Depending on the account’s ownership and survivorship terms, adding another person can affect who receives the account at death.
Could a beneficiary designation conflict with my will?
Yes. Certain beneficiary designations control the transfer of assets outside probate and may produce a different result from a later will.
Can I create a trust but still have assets go through probate?
Yes. An asset that remains outside the trust and is otherwise a probate asset may still require probate administration.
Can putting my child on my house cause problems?
Yes. Adding a child as an owner can affect control and ownership during life, while Florida homestead law imposes additional rules on certain transfers and inheritance.
Should every asset be arranged to avoid probate?
No. The appropriate treatment depends on the asset, the owner’s objectives, family circumstances, and applicable Florida law.
When Probate Avoidance Becomes an Estate-Planning Problem
Keeping an asset out of probate can be useful. It can also change who owns it, who controls it, and who receives it.
The important question is whether the way an asset avoids probate produces the result the owner actually intended.
How Long Does a Landlord Have to Return a Security Deposit?
Florida Statute §83.49 creates two different timelines.
If the landlord is not making a claim against the security deposit, the deposit must be returned within 15 days after the tenancy ends.
If the landlord intends to keep some or all the deposit, the landlord has 30 days to notify the tenant. He provides a copy in writing of the intention to impose a claim and the reason for it. The notice must be sent as required by the statute. This by certified mail to the tenant’s last known mailing address or, when the parties have properly agreed to electronic notices, by email.
That difference is important. The 15-day rule is about returning a deposit when there is no claim. The 30-day rule gives the landlord time to notify the former tenant about a claim against the deposit.
What If the Landlord Wants to Keep Part of the Deposit?
A landlord cannot simply decide that the security deposit has become a convenient repair fund.
When a landlord intends to impose a claim, the required notice must state the amount claimed. It should also state the reason for the claim. The tenant then has 15 days after receiving the notice to object in writing.
If the tenant does not object within that period, things change. The landlord may deduct the claim and must send the remaining balance within the time required by the statute.
A late objection does not necessarily eliminate every possible legal claim by the tenant. Florida law says that failing to object within the 15-day period doesn’t waive the right to seek damages.
What Can a Landlord Deduct From a Security Deposit in Florida?
A security deposit exists to secure the tenant’s obligations under the rental agreement. A dispute can arise over unpaid rent, damage to the property, or other amounts the landlord claims are owed under the lease.
The recurring fight, however, is usually about damage versus ordinary wear and tear.
A tenant who has lived in an apartment for several years shouldn’t expect it to look as it did on move-in day. Normal deterioration is different from a broken fixture, a damaged door, or other physical damage caused during the tenancy.
The lease, the property’s condition, and the evidence surrounding the claimed damage all matter.
For that reason, both sides should preserve useful records:
The lease and any amendments
Move-in and move-out photographs
Inspection reports
Messages about repairs
Photographs of claimed damage
Repair invoices or estimates
Proof of rent payments
The tenant’s forwarding address
The landlord’s deposit correspondence
A photograph taken on moving day can be considerably more useful than an argument six months later about what the carpet looked like.
What Happens If the Landlord Misses the 30-Day Deadline?
This is one of the most important Florida security deposit rules.
If a landlord fails to give the required notice within the 30-day period, the landlord forfeits the right to impose a claim against the security deposit. The statute still allows the landlord to bring an action for damages after returning the deposit.
That does not mean every late notice automatically ends every dispute between the parties. It means the landlord cannot use the security deposit itself as a setoff after missing the statutory notice deadline.
For a tenant who has been waiting for a deposit, the date the tenancy ended and the date the landlord sent the notice can therefore become important evidence.
What If the Tenant Disagrees With the Deduction?
A tenant who receives a claim against the deposit has 15 days after receiving the notice to object in writing.
The objection should address the actual dispute. If the landlord claims $2,000 for repairs and the tenant believes the property suffered ordinary wear and tear, thing vary. The tenant can explain that disagreement and preserve the relevant evidence.
Photographs, inspection records, repair communications, and the condition of the property at move-in can all become useful.
If the dispute cannot be resolved, either party can bring an action to determine who is entitled to the security deposit. Florida law provides that the prevailing party is entitled to court costs and a reasonable attorney fee in an action concerning the deposit.
That can make the size and strength of the claim relevant when deciding how to proceed.
Does a Florida Security Deposit Earn Interest?
It can.
Florida law allows a landlord to hold a security deposit in a separate non-interest-bearing account, a separate interest-bearing account, or under certain circumstances through a surety bond.
When the deposit is held in an interest-bearing account, the tenant must receive interest calculated under the formula in §83.49. The statute also provides a 5% simple-interest requirement when the landlord uses the specified surety-bond option.
The landlord must also give the tenant written information about how the deposit is being held and whether the tenant is entitled to interest, subject to the statutory exceptions.
What If I Paid a Fee Instead of a Security Deposit?
Florida law now recognizes a separate arrangement in which a landlord may offer a tenant the option to pay a fee in lieu of a security deposit.
That fee is legally different from a traditional security deposit. The arrangement has its own disclosure requirements and rules concerning claims for unpaid rent, fees, and property damage. The statute applies to rental agreements entered into or renewed on or after July 1, 2023.
So if the money paid at the beginning of the tenancy was called a “deposit waiver fee,” “deposit alternative,” or something similar, the first step is to determine what agreement the tenant actually signed.
The ordinary security-deposit rules should not automatically be applied to a different arrangement.
What If the Tenant Never Gave a Forwarding Address?
Give the landlord one.
Florida’s statutory security-deposit notice specifically tells tenants to provide a new address after moving out so the landlord can send notices concerning the deposit. Section 83.49 also contains separate rules concerning a tenant who vacates or abandons a property without giving the required notice.
A forwarding address also removes one very unnecessary source of confusion.
If there is a dispute over the deposit, keep proof that the new address was provided and keep copies of the communication.
Security Deposit Disputes in Coral Springs and Broward County
A security deposit dispute in Coral Springs is governed primarily by Florida’s statewide landlord-tenant law. Florida expressly preempts local regulation of matters covered by Part II of Chapter 83, including security deposits and landlord-tenant notice requirements.
The same statutory framework applies across Broward County and South Florida, whether the rental property is in Coral Springs, Tamarac, Fort Lauderdale, Parkland, or another community.
The facts of the dispute will still be local: the rental property, the lease, the inspection records, the communications between the parties, and the evidence supporting the claimed deduction.
Landlord or tenant? Get the deposit dispute reviewed before it gets bigger.
If you are a tenant and your security deposit was withheld, bring the lease, the landlord’s notice, photographs, and your move-out records to an attorney who can evaluate whether the deduction and notice complied with Florida law.
If you are a landlord, have the lease, deposit records, photographs, invoices, and notice reviewed before assuming a deduction is enforceable. A mistake in the notice or timing can affect your ability to claim against the deposit.
How long does a landlord have to return a security deposit in Florida?
Generally, 15 days after the tenancy ends if the landlord does not intend to make a claim against the deposit. If the landlord intends to make a claim, the landlord generally has 30 days to provide the required notice.
Can a landlord keep a security deposit for damages in Florida?
A landlord may have a claim against a security deposit for amounts the tenant owes under the rental agreement, including qualifying damage. The landlord must follow Florida’s statutory notice procedure when making a claim.
What is the 30-day rule for security deposits in Florida?
If a landlord intends to impose a claim against the security deposit, the landlord generally must give the tenant written notice of the claim and its reason within 30 days after the tenancy ends.
How long does a tenant have to dispute a security deposit deduction in Florida?
A tenant generally has 15 days after receiving the landlord’s claim notice to object in writing.
What happens if a landlord does not return a security deposit in Florida?
The answer depends on whether the landlord made a claim and whether the required statutory notices were provided on time. A landlord who misses the 30-day claim-notice deadline forfeits the right to impose a claim against the deposit itself, although the statute allows a later action for damages after the deposit is returned.
This article provides general information about Florida landlord-tenant law and security deposits. It is not legal advice for a particular landlord or tenant, and the outcome of a dispute depends on the lease, the facts, and the applicable law.
Florida law establishes two primary court-supervised probate procedures for handling an estate. Specifically, courts offer Summary Administration as an expedited process for smaller estates and Formal Administration as the traditional, fully supervised court proceeding
Whether an estate qualifies for Summary Administration depends on the total net value of non-exempt probate assets, whether the decedent has been deceased for over two years, and the complexity of outstanding creditor claims under Florida probate law (Fla. Stat. § 735.201). Understanding how these two probate paths function ensures that South Florida beneficiaries receive their inheritance as quickly and cost-effectively as possible.
Summary vs. Formal Administration at a Glance
Qualification & Process Feature
Summary Administration (Fla. Stat. § 735.201)
Formal Administration (Florida Probate Rules)
Estate Value Threshold
Non-exempt probate assets are $150,000 or less (for deaths on/after July 1, 2026), OR the decedent has been deceased for over 2 years.
Required for estates exceeding $150,000 in non-exempt probate assets (if death occurred within 2 years).
Personal Representative
Not appointed. No Letters of Administration are issued by the court.
Required. Court officially appoints a Personal Representative (Executor) with fiduciary authority.
Average Timeline
4 to 8 weeks (subject to Broward County court docket schedules).
Creditors must be resolved or served prior to distribution; or barred if death occurred over 2 years ago.
Formal 3-month Notice to Creditors published in local media to legally bar future claims.
Primary Judicial Order
Order Summary Administration directly transfers legal title of assets to beneficiaries.
Letters of Administration issued at inception; Order of Discharge issued at estate closing.
When Does Summary Administration Apply in Florida?
Furthermore, Summary Administration provides an expedited judicial procedure that transfers property title to beneficiaries without opening a full probate estate.. However – to qualify under Florida law, the estate must satisfy one of two statutory criteria:
The $150,000 Net Asset Test: Effective July 1, 2026, Florida increased the summary administration statutory limit. The total value of all assets subject to probate—excluding protected Florida Constitutional Homestead real estate and statutory exempt personal property—does not exceed $150,000 (for deaths on or after July 1, 2026; $75,000 for deaths prior to July 1, 2026).
The Two-Year Rule: In addition, petitioners can file for Summary Administration if the decedent died more than two years prior. Florida law waives the asset limit after this two-year period expires. Under Fla. Stat. § 733.710, two years establishes a non-claim statute of repose that automatically bars unfiled creditor claims.
Key Distinction: No Personal Representative Appointed
In Summary Administration, the court does not appoint a Personal Representative and does not issue Letters of Administration. Instead, the petitioner files a petition asking the judge to transfer specific assets, such as a bank account or vehicle, directly to named beneficiaries.
Some estates require active ongoing legal authority to access restricted medical records, pursue a wrongful death lawsuit, or negotiate complex business debts. Consequently, the petitioner must open Formal Administration regardless of the estate’s total value.
When Is Formal Administration Mandatory?
Formal Administration is the comprehensive, fully supervised probate process in Florida. It is mandatory when:
Non-exempt probate assets exceed $150,000 and the decedent passed away within the last two years.
The decedent’s Last Will and Testament explicitly mandates formal probate administration.
The estate involves disputed creditor claims, contested wills, or missing heirs.
In addition, the appointed Personal Representative must actively list, market, and sell real estate during probate by signing legal contracts and closing documents.
FLORIDA PROBATE DECISION PATH
↓
Is the non-exempt probate value under $150k OR has the decedent been deceased > 2 years?
▼ YES▼ NO
Are there complex debts, disputes, or land sales requiring an Executor?
YES
Requires formal oversight / Executor
NO
SUMMARY ADMINISTRATION
Expedited, 4-8 Weeks, Order Directly Transfers
FORMAL ADMINISTRATION
Full Court Process
Personal Rep Appointed, 6-12 Month Duration
What About Very Small Estates? (Disposition Without Administration)
For extremely modest estates where the decedent left no real estate, Florida offers an informal non-probate process under Fla. Stat. § 735.301 known as Disposition of Personal Property Without Administration.
This simplified filing is available only when remaining non-exempt personal property does not exceed the total sum of preferred funeral expenses and necessary medical bills incurred during the last 60 days of the decedent’s final illness.
Selecting between Summary and Formal Administration involves critical legal trade-offs beyond estate size:
1. The Post-Probate Creditor Exposure Risk
Under Fla. Stat. § 735.206, Summary Administration directly distributes assets to beneficiaries without opening a mandatory 90-day newspaper creditor publication window.
Consequently, if the petitioner files the petition before the two-year non-claim period expires, creditor claims can still affect the estate. (Fla. Stat. § 733.710). Beneficiaries remain personally liable to valid estate creditors up to the full value of the property received. If unknown debts emerge post-distribution, Formal Administration is often safer because publishing a statutory Notice to Creditors permanently cuts off future claims after 90 days.
2. Ancillary Administration for Out-of-State Residents
However, an out-of-state court order cannot transfer real estate in Broward County or anywhere in South Florida when a non-resident dies. An Ancillary Probate proceeding (Fla. Stat. § 734.102) must be opened in Florida. Depending on the non-exempt Florida land value, Ancillary proceedings can be conducted as either Summary or Formal Administration.
Frequently Asked Questions
Does Florida Homestead Property count toward the $150,000 Summary Administration limit?
No. Protected Florida Constitutional Homestead property passes to heirs outside general creditor claims. Furthermore, the court excludes this property when calculating the $150,000 Summary Administration threshold, provided the petitioner files a formal Petition to Determine Homestead Status alongside the summary petition.
What is the 10-day Will Deposit Rule in Florida?
Under Fla. Stat. § 732.901, whoever holds the decedent’s original Last Will and Testament must deposit it with the Clerk of the Circuit Court in the county where the decedent resided within 10 days of receiving notice of death, regardless of whether formal probate will be opened.
What is the current Florida Summary Administration asset threshold?
Effective July 1, 2026 (Fla. Stat. § 735.201), the Florida Legislature increased the non-exempt probate asset threshold for Summary Administration from $75,000 to $150,000 for deaths occurring on or after July 1, 2026 (or where the decedent has been deceased for more than 2 years). Protected homestead property continues to be excluded from this calculation.
How long does Formal Administration take in Broward County?
A routine, uncontested Formal Administration in Broward County typically takes between 6 and 12 months. This timeframe accommodates publishing the mandatory Notice to Creditors, observing the 90-day statutory creditor claim window, marshaling asset inventories, preparing tax accountings, and securing final court discharge.
Can the court convert a summary administration to a formal administration if a dispute arises?
Yes. Unexpected creditor claims, beneficiary disputes, or newly discovered assets can push an estate’s total value over $150,000. Consequently, any interested party or petitioner can motion the court to convert the summary proceeding into a Formal Administration.
Do I need a probate attorney for Summary Administration in Broward County?
Florida law technically permits self-representation in Summary Administration when the court does not appoint a Personal Representative. However, court clerk offices cannot provide legal advice or assist you with legal filings.. Drafting accurate petitions, verifying homestead status, and coordinating creditor searches require specialized legal guidance to avoid judicial rejection.
Don’t Let an Outdated Deed Dictate Your Family’s Future
Choosing the correct probate pathway prevents costly administrative delays, court rejections, and personal liability for estate debts. Your family may qualify for an expedited Summary Administration or require full Formal Administration in South Florida. Regardless, working with experienced legal counsel ensures that you protect every estate asset.
Schedule a Property Deed & Titling Audit
Consequently, you should structure your real estate title and probate strategy so assets pass seamlessly outside of or through probate court. Contact the attorneys at Reinfeld & Cabrera, P.A. today to review your estate and property deeds with our South Florida legal team.
Office Locations: Coral Springs | Fort Lauderdale | Plantation
Direct Telephone: (954) 334-1520
Email: Info@lawrct.com
Website: mypersonalattorneys.com
Local Practice Coverage: Coral Springs, Fort Lauderdale, Tamarac, Plantation, and Broward County
When you sit down at the kitchen table to sort through a parent’s papers after they pass away, the last thing you want is a fresh wave of bureaucratic dread.
What happens to the house now? How do we pay the lingering bills? And why does everyone make probate sound like a multi year hostage negotiation with the state of Florida?
Quick Answer:
Under Florida probate law, administering an estate through the 17th Judicial Circuit in Broward County involves formal or summary court proceedings to settle debts and transfer property. Formal administration typically takes between six months and over a year due to mandatory creditor notice windows, whereas summary administration offers an expedited process for estates valued under $75,000 or where the decedent passed away more than two years ago.
If you search online for estate guidance, you will drown in dry textbook definitions. Most treat probate like an unavoidable trap or a magical cure all. Neither description captures reality. Probate is simply the legal mechanism the state uses to clear title to property. It’s how to pay legitimate creditors, and transition assets when someone passes away without proper advance planning.
So what do Florida families and property owners actually need to know about navigating the Broward County court system. What do they need to get to manage a estate, and keep your hard earned assets out of unnecessary courtrooms? Let us pull back the curtain and talk about how estate administration really works in South Florida without any legal mumbo jumbo.
Why the Internet Gets Probate Wrong (And Why Wills Do Not Avoid Court)
There is a stubborn myth floating around the internet that having a last will and testament means your family completely bypasses the probate court. People assume a will acts like a VIP backstage pass that lets your heirs walk right past the judges and walk away with your property.
Nothing could be further from the truth.
Ask yourself: If I spend my entire life building equity in a home and saving for my children, why would I hand them a legal document that explicitly instructs a judge to oversee how those assets get handed out?
A will does not avoid probate. A will is instructions for the probate court. It tells the judge who you want to inherit your belongings. But the court still has to supervise the process, validate the signature, notify creditors, and formally authorize your personal representative to act. If you want to spare your family from court supervision, you have to look beyond a basic will. You should utilize tools like revocable living trusts, payable on death designations, and properly structured joint ownership.
What Actually Goes Through Probate in Florida?
Not every asset a person owns gets sucked into the probate vortex upon death. Understanding the dividing line between probate and non probate property is the first step toward building a sensible estate plan.
Probate Assets: Solely owned real estate, bank accounts held in a single name without payable on death instructions, and personal belongings like vehicles or jewelry without designated beneficiaries must go through court administration to change legal ownership.
Non Probate Assets: Assets governed by contract or operation of law pass directly to beneficiaries without court interference. This includes living trusts, life insurance policies with named beneficiaries, retirement accounts. It also includes real estate held as tenants by the entirety or joint tenants with rights of survivorship.
If your estate consists entirely of beneficiary designated accounts and trust owned property, things change. Your family might never set foot inside a courtroom. But if a single deed or bank account was left in your individual name, the probate doors swing wide open.
Formal Administration Versus Summary Administration in Broward County
When a probate estate is opened in the 17th Judicial Circuit in Broward County, the administration generally follows one of two statutory paths. Both depend on the size of the estate and how long the decedent has been gone:
Formal Administration: This is the standard, comprehensive court process required for larger estates or complex matters involving multiple creditors and disputed claims. The court appoints a personal representative, issues letters of administration, requires formal publication of notice to creditors, and mandates a multi month inventory and accounting process.
Summary Administration: A streamlined, expedited court procedure available in Florida if the value of the entire estate subject to probate does not exceed $75,000, or if the decedent has been dead for more than two years. Summary administration bypasses the appointment of a personal representative and moves much faster, though it still requires a formal petition filed by an attorney.
Avoiding Dual Tracking and Creditor Traps During Estate Administration
When a personal representative steps up to manage an estate in South Florida, they quickly realize that administering assets is a minefield of strict statutory deadlines and creditor notification rules under Florida Probate Code.
How do you handle aggressive credit card companies or mortgage lenders demanding payment while the estate is still frozen in court?
The Creditor Notice Period: Florida law requires a diligent search for known creditors and publication of a formal notice in a local legal periodical. Creditors have a strict window (typically three months from the first publication of notice) to file formal claims against the estate.
The Priority of Claims: You cannot simply pay out inheritance money to family members while valid estate debts remain unpaid. Florida law establishes a rigid priority structure for paying funeral expenses, administrative costs, taxes, and medical bills before beneficiaries see a dime. Failing to follow this order can expose the personal representative to personal financial liability.
Real World Case Example: Untangling an Estate in Broward County
To see how these rules play out in local practice, consider a scenario our firm frequently handles across Coral Springs and Fort Lauderdale.
A client came to our office after losing a parent who owned a residential home in Broward County without a living trust. The parent had left a simple will naming our client as personal representative, but because the deed was in the parent’s individual name, the property was completely frozen. To make matters worse, a home equity line of credit was past due, and the lender was threatening default proceedings while the family was still grieving.
How Our Legal Team Resolved the Crisis
Opening Formal Administration: We immediately filed a petition for formal administration in the 17th Judicial Circuit, securing letters of administration so our client had the legal authority to deal with the bank.
Publishing Creditor Notice: We managed the statutory creditor notice period. We shield the personal representative from harassing collection calls and ensuring claims were evaluated through proper legal channels.
Resolving the Debt and Transferring Title: By coordinating with the mortgage lender and liquidating a small non probate account to cover arrears, we stabilized the property, avoided foreclosure, and ultimately transferred clear title of the home to the rightful heirs.
Frequently Asked Questions About Florida Probate
How long does the probate process take in Broward County?
An uncontested formal administration in Florida typically spans 6 to 12 months. This timeline is largely dictated by mandatory statutory creditor notice periods and court review schedules in the 17th Judicial Circuit. Complex estates involving will contests or contested creditor claims can take significantly longer.
Can I avoid probate simply by writing a last will and testament?
No. A common misconception is that having a will avoids probate. In reality, a will provides instructions for the probate court on how you want your assets distributed. To avoid probate entirely, assets must pass outside the will via living trusts, beneficiary designations, or survivorship titles.
What happens if someone dies intestate without a will in Florida?
If a person dies without a valid will, Florida intestacy statutes dictate how assets are distributed among surviving spouses, children, or extended relatives. This rigid statutory formula rarely matches what the decedent would have actually wanted. And it often forces court sales of family property to divide proceeds among heirs.
Do I need a probate attorney if I am appointed as a personal representative?
Yes. Under Florida probate rules, a personal representative representing an estate with multiple beneficiaries or outstanding creditors is generally required by law to be represented by a licensed attorney admitted to practice in Florida.
Protect Your Estate and Your Family Legacy
Planning for the future or handling the aftermath of a loved one’s passing is not something you should do alone. Whether you want to bulletproof your own estate with a comprehensive living trust or you need experienced local counsel to guide you through a Broward County probate administration, having the right advocate changes everything.
The estate planning and probate attorneys at Reinfeld Cabrera Tison help families across South Florida secure their assets. We establish durable trusts, and resolve complex court proceedings with absolute confidence.
Schedule a Confidential Consultation
Do not wait until a crisis forces your family into court. Speak directly with an experienced attorney today to review your options:
Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
Website: mypersonalattorneys.com
Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate. All surrounding communities across Broward, Miami Dade, and Palm Beach Counties.
The answer depends on when the beneficiary died, the language of the will, the beneficiary’s relationship to the person who died, and whether the beneficiary had already acquired a legal interest in the inheritance.
This situation can become complicated during Florida probate. A beneficiary may die while the estate is still being administered, leaving the personal representative and the surviving beneficiaries with an important question: Who is now entitled to receive that beneficiary’s share?
The answer is not always the beneficiary’s children, and the inheritance does not automatically return to the estate of the person who originally died.
What Happens When a Beneficiary Dies During Probate?
The first question is when the beneficiary died in relation to the person whose estate is being administered.
There is an important legal difference between a beneficiary who dies before the decedent and one who survives the decedent but dies before receiving an inheritance.
Those situations can produce different results under Florida law.
If the beneficiary survived the decedent, the beneficiary may have acquired an interest in the estate even though the probate case had not yet been completed. If that happens, the beneficiary’s own estate may become involved in receiving and administering that interest.
By contrast, if the beneficiary died before the decedent, Florida’s anti-lapse rules may determine whether the gift passes to certain descendants or otherwise fails under the terms of the will.
What If a Beneficiary Dies Before Receiving an Inheritance?
A common misconception is that an inheritance does not belong to a beneficiary until the personal representative actually writes the check or transfers the property.
That is not necessarily how probate works.
When a beneficiary survives the person who created the will, the legal treatment of that beneficiary’s interest can be different from the situation in which the beneficiary predeceases the decedent. The fact that distribution has not yet occurred does not by itself answer who ultimately receives the property.
The personal representative may therefore need to determine whether the deceased beneficiary’s interest must be distributed to the beneficiary’s estate.
This is one reason the question “what happens if a beneficiary dies before probate is complete?” cannot be answered with a single rule.
What If the Beneficiary Survived the Decedent?
This is one of the most important distinctions.
Suppose Maria leaves $100,000 to her son David in her will. Maria dies, and her probate estate is opened. David is alive when Maria dies, but he dies several months later while the probate case is still pending.
The fact that David died before receiving the $100,000 does not necessarily mean the gift disappears.
Depending on the circumstances and the terms of Maria’s will, David’s interest may become part of his own estate. His personal representative may then have to address that inheritance as part of David’s estate administration.
That can introduce a second probate or estate administration process.
The personal representative of Maria’s estate may therefore need to coordinate with the representative of David’s estate before the inheritance can be distributed.
What If the Beneficiary Died Before the Person Who Made the Will?
The situation can be different when a beneficiary dies before the testator.
For example, imagine that Maria’s will leaves her estate to her son David, but David dies before Maria. Maria later dies without changing her will.
Florida’s anti-lapse statute can sometimes preserve a gift to a deceased beneficiary’s descendants rather than allowing the gift to lapse. Florida Statutes section 732.603 applies to certain devisees who are relatives of the testator and who leave descendants who survive the testator. The statute also contains exceptions and conditions that can affect whether the rule applies.
This means that a beneficiary’s children do not automatically inherit every time a named beneficiary dies first.
The relationship between the deceased beneficiary and the testator matters. So does the language of the will.
How Does Florida’s Anti-Lapse Law Work?
Florida’s anti-lapse statute is designed to address certain situations in which a person named to receive property under a will dies before the testator.
Under section 732.603, a devise to certain relatives of the testator does not necessarily lapse merely because the named beneficiary dies before the testator. When the statutory requirements are satisfied, the deceased beneficiary’s descendants may take the property in the manner provided by the statute.
But anti-lapse rules should not be treated as a universal substitute-beneficiary provision.
The statute has specific requirements concerning the relationship between the testator and beneficiary, the beneficiary’s descendants, and survival. The will itself can also contain language that affects the outcome.
For that reason, determining whether Florida’s anti-lapse law applies requires examining the actual estate planning documents and the family relationships involved.
Does the Inheritance Go to the Beneficiary’s Children?
Not automatically.
Whether a deceased beneficiary’s children receive the inheritance depends on the circumstances.
If the beneficiary died before the testator, Florida’s anti-lapse statute may allow certain descendants to receive the gift.
If the beneficiary survived the testator and then died during probate, the analysis can be different. The beneficiary’s interest may instead become part of the beneficiary’s own estate, depending on the nature of the property interest and the governing documents.
The distinction is critical.
Simply knowing that “the beneficiary died” is not enough to determine what happens next.
What Happens to the Deceased Beneficiary’s Estate?
When a beneficiary survives the original decedent but dies before receiving the inheritance, the beneficiary’s own estate may become relevant.
The inheritance may need to be administered alongside the beneficiary’s other assets. The beneficiary’s will, if there is one, may affect who ultimately receives the property. If there is no valid will, the beneficiary’s estate may instead be distributed under the applicable intestacy rules.
This can create a situation in which one estate is effectively waiting for another estate to be administered.
For example, the personal representative of the first estate may need documentation establishing who has authority to act for the deceased beneficiary’s estate before completing distribution.
What If the Will Names a Backup Beneficiary?
Some wills specifically address what happens if a beneficiary dies.
A will might provide that if a named beneficiary does not survive the testator, the property goes to another person or group of people. Other wills may contain language creating a substitute gift or otherwise addressing descendants.
These provisions can change the analysis significantly.
This is why the will should be reviewed before relying on a general rule about a beneficiary who dies before receiving an inheritance.
A specific provision in the will may provide a different result from what would happen under the default statutory rules.
What Does the Personal Representative Need to Do?
The personal representative is responsible for administering the estate according to the will and Florida law.
When a beneficiary dies during administration, the personal representative may need to determine:
When the beneficiary died
Whether the beneficiary survived the decedent
Whether the will contains a substitute beneficiary provision
Whether Florida’s anti-lapse statute applies
Whether the beneficiary had already acquired an interest in the estate
Whether the beneficiary left a will
Who has authority to represent the beneficiary’s estate
Whether additional court filings are necessary
Whether the distribution should be delayed until the issue is resolved
The personal representative should not simply assume that the deceased beneficiary’s share goes to the beneficiary’s children or surviving relatives.
The correct result depends on the facts and governing documents.
Can a Beneficiary’s Death Delay Probate?
Yes.
A beneficiary’s death can complicate or delay an estate administration, particularly when the deceased beneficiary’s estate must become involved.
The personal representative may need additional documentation, court orders, or information about the beneficiary’s heirs or estate. If family members disagree about who should receive the deceased beneficiary’s share, the issue can become contested.
This is one reason a probate case can remain open even after the major assets and beneficiaries initially appear to have been identified.
What If Family Members Disagree About the Inheritance?
Disputes can arise when different family members interpret a will differently or disagree about whether an anti-lapse provision applies.
For example, one relative might argue that the deceased beneficiary’s children should receive the inheritance, while another argues that the property should pass under a different provision of the will.
The personal representative may need to seek legal guidance or court involvement rather than making the distribution based on an informal family agreement.
A disputed inheritance can also become more complicated when the deceased beneficiary had creditors, a separate probate estate, or competing heirs.
What Happens When a Beneficiary Dies Before the Estate Is Distributed in Florida?
There is no single answer for every Florida probate case.
If the beneficiary died before the decedent, Florida’s anti-lapse statute may apply in certain circumstances.
If the beneficiary survived the decedent but died before receiving the inheritance, the beneficiary’s interest may instead become part of the beneficiary’s own estate.
The will, the timing of the deaths, the relationship between the people involved, and the nature of the property all matter.
That is why a personal representative should determine the legal status of the beneficiary’s interest before distributing the estate.
Frequently Asked Questions
What happens if a beneficiary dies before probate is complete?
It depends on whether the beneficiary survived the person whose estate is being administered. If the beneficiary survived the decedent and later died during probate, the beneficiary’s interest may need to be handled through the beneficiary’s own estate. If the beneficiary died first, Florida’s anti-lapse rules may apply in certain circumstances.
Are heirs responsible for a deceased beneficiary’s inheritance?
Not necessarily. An inheritance may become part of the deceased beneficiary’s estate, and the people ultimately entitled to receive it can depend on the beneficiary’s will or Florida intestacy law.
Does a deceased beneficiary’s estate receive the inheritance?
When a beneficiary survives the original decedent but dies before distribution, the beneficiary’s estate may have a claim to the beneficiary’s share. The specific result depends on the nature of the interest, the will, and the circumstances of the estate.
Does Florida’s anti-lapse statute apply whenever a beneficiary dies?
No. Florida’s anti-lapse statute contains specific requirements and applies to certain circumstances involving beneficiaries who die before the testator. The statute should be reviewed together with the will and the family relationships involved.
Do the beneficiary’s children automatically inherit?
No. The beneficiary’s children do not automatically inherit simply because their parent died. They may receive property under Florida’s anti-lapse statute in qualifying circumstances, or they may inherit through their parent’s estate under different circumstances.
Can a beneficiary’s death create another probate case?
It can. If a beneficiary survives the original decedent and later dies while entitled to receive property, the beneficiary’s estate may need to administer that interest.
What should a personal representative do when a beneficiary dies?
The personal representative should establish when the beneficiary died. He needs to review the will, determine whether the beneficiary survived the decedent, identify any applicable substitute-beneficiary or anti-lapse provisions. He then needs to determine who has legal authority to receive or administer the beneficiary’s interest.