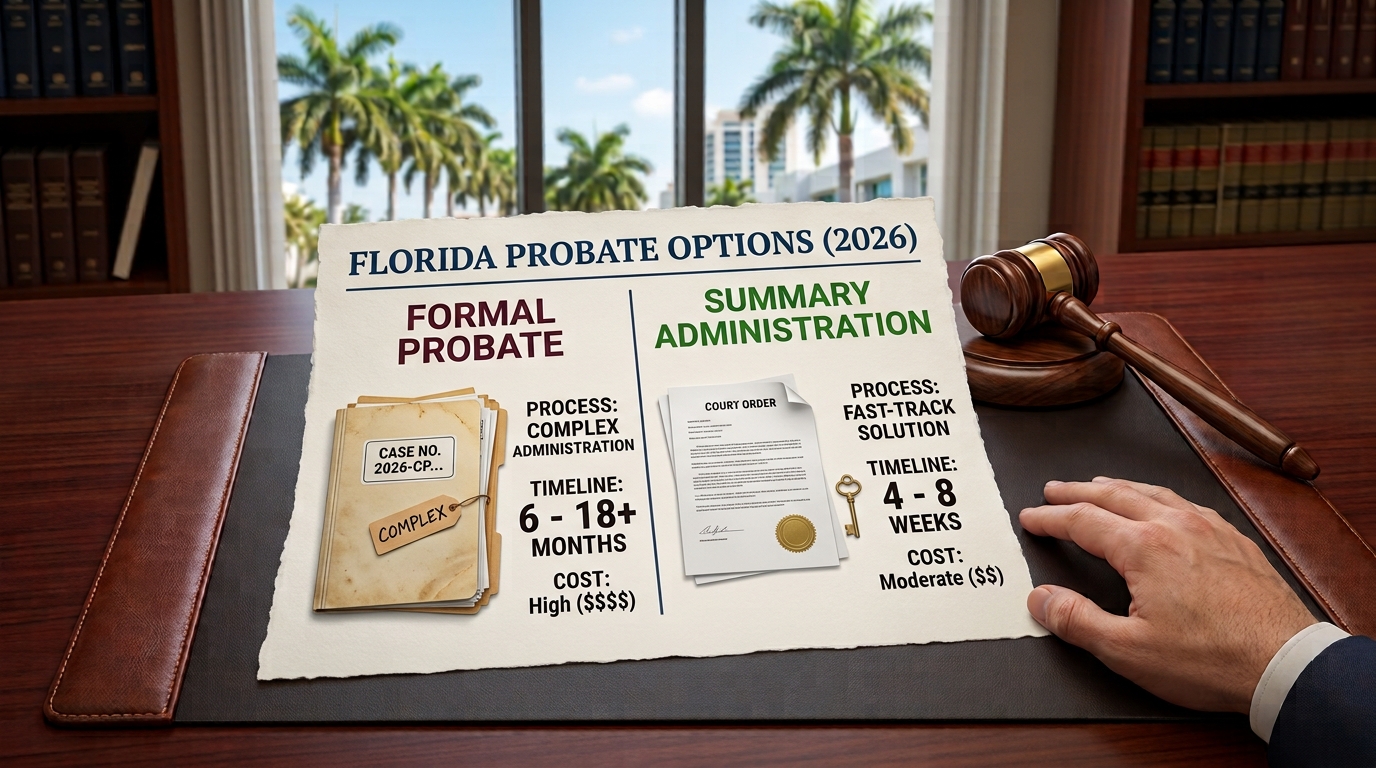
When a loved one passes away in Florida, families often assume they are facing a year-long legal battle filled with court dates, stacks of paperwork, and exorbitant administrative costs. However, under Chapter 735 of the Florida Probate Code, many families qualify for a fast-track judicial process known as Summary Administration.
Effective July 1, 2026, Florida doubled the statutory limit for small estate probate under Fla. Stat. § 735.201 from $75,000 to $150,000. This critical update allows significantly more families to distribute estate assets in a matter of weeks rather than months.
Direct Answer
What are the requirements for Summary Administration in Florida?
To qualify for Summary Administration in Florida under Fla. Stat. § 735.201, an estate must satisfy either of the following two criteria:
The $150,000 Asset Cap: The total value of non-exempt Florida probate assets is $150,000 or less (for deaths on or after July 1, 2026).
The 2-Year Rule: The decedent has been deceased for more than two years, regardless of total estate value.
Additionally, the decedent’s Last Will and Testament must not explicitly mandate Formal Estate Administration.
The Two Pathways to Qualifying for Summary Probate
Unlike Formal Administration—which requires the court to appoint a Personal Representative (Executor) and oversee a lengthy administration period—Summary Administration acts as a direct judicial order transferring assets straight to beneficiaries.
For decedents passing on or after July 1, 2026, the estate’s total non-exempt probate assets must not exceed $150,000. (For deaths occurring prior to July 1, 2026, the statutory limit remains $75,000).
2. The Two-Year Statute of Repose Rule
If the decedent passed away more than two years ago, the estate automatically qualifies for Summary Administration, regardless of how millions of dollars the estate is worth. Under Fla. Stat. § 733.710, Florida enforces a strict two-year statute of repose that permanently bars unfiled creditor claims, removing the necessity for a formal personal representative to manage debts.
Why “On-Paper” Net Worth Misleads Most Heirs
One of the most frequent misconceptions beneficiaries encounter is assuming that if a relative owned a high-value home in South Florida, they are automatically forced into Formal Probate.
Florida law only evaluates probate assets subject to court distribution. The following major asset categories are entirely excluded from the $150,000 threshold calculation:
Florida Protected Homestead Real Estate: Under Article X, Section 4 of the Florida Constitution, a primary residence passing to a surviving spouse or lineal heirs is constitutionally protected from general creditors. Because homestead rights vest immediately upon death, the home’s value (whether $400,000 or $2,000,000) does not count toward the $150,000 limit when petitions are properly structured.
Statutory Exempt Personal Property: Under Fla. Stat. § 732.402, up to $20,000 in household furniture/furnishings and two personal motor vehicles used by the decedent are exempt from creditor claims and excluded from the asset tally.
Non-Probate Financial Transfers: Bank accounts with Payable-on-Death (POD) or Transfer-on-Death (TOD) designations, life insurance policies with named beneficiaries, jointly owned property with rights of survivorship, and assets held inside a Revocable Living Trust bypass probate entirely.
“Many families walk into our office believing they owe thousands in court fees because their parent owned a $700,000 house in Coral Springs. Once we isolate the constitutional homestead and exempt vehicles, the actual probate asset is just a $40,000 checking account—qualifying them for fast-track Summary Administration instantly.”
— Devin P. Tison, Esq., Lead Partner at Reinfeld Cabrera Tison
Real-World Case Studies: How Summary Administration Works in Practice
Case Study 1: Bypassing Formal Probate for a Broward County Home & Bank Account
Scenario: A widow in Fort Lauderdale passed away, leaving a home valued at $550,000 and a sole-name savings account containing $65,000. Her two adult children were named as equal beneficiaries in her Will.
The Legal Challenge: A traditional law firm informed the siblings they needed Formal Administration due to the $615,000 gross estate value, quoting an estimated 9-month process and thousands in hourly fees.
The RCT Solution: Our probate team filed a Petition for Determination of Homestead Property alongside aPetition for Summary Administration. Because the $550,000 home was protected homestead, its value dropped to $0 for qualification purposes. The only remaining asset was the $65,000 account—well under the statutory limit.
Outcome: The Broward County Probate Court issued an Order of Summary Administration in 5 weeks. The bank released the funds directly to the siblings, and the homestead order cleared title for them to sell the home without appointing a Personal Representative.
Case Study 2: Settling an Estate Decades Later for Out-of-State Heirs
Scenario: A father passed away in Miami-Dade County in 2018 owning an unlinked parcel of land. His heirs, living in New York, never probated the estate because they believed the process was too complex from out-of-state.
The Legal Challenge: The land grew in value to $220,000. The heirs wanted to sell the land but could not clear title without court authorization.
The RCT Solution: Because the decedent had been deceased for over two years, the estate qualified under the 2-Year Rule regardless of the $220,000 property value. We managed the entire filing remotely via Florida’s electronic court portal without requiring the heirs to travel to Florida.
Outcome: The court signed the distribution order within 4 weeks, enabling the title company to execute a seamless sale.
Detailed Comparison: Summary vs. Formal Administration
Key Feature
Summary Administration (Fla. Stat. § 735.201)
Formal Administration (Fla. Stat. Ch. 733)
Statutory Eligibility
Non-exempt assets $\le \$150,000$ OR death > 2 years ago
Estates over $\$150,000$ or complex litigation cases
Average Timeline
4 to 8 weeks
6 to 12+ months
Personal Representative
None appointed by the court
Court appoints an Executor/PR
Letters of Administration
Not issued
Issued (gives PR power to act for estate)
Primary Court Order
Order of Summary Administration
Order of Discharge
Legal Costs
Significantly lower; often structured as a Flat Fee
Higher court fees, inventory costs, and hourly rates
Frequently Asked Questions (FAQ)
Does Florida have a Small Estate Affidavit to avoid probate?
No. Florida does not recognize a standalone “Small Estate Affidavit” for transferring real estate or bank accounts like some other states do. Florida’s equivalent for small estates is Summary Administration or, for extremely small asset values under funeral costs, Disposition Without Administration (Fla. Stat. § 735.301).
What happens to outstanding creditor debts in Summary Administration?
Because no Personal Representative is appointed to manage estate claims, beneficiaries who receive assets through Summary Administration remain personally liable for valid debts of the decedent up to the dollar value of what they inherited. To eliminate this risk, a probate attorney can publish an optional Notice to Creditors in a local South Florida newspaper, initiating a 30-day window that permanently bars unfiled claims.
Can an out-of-state beneficiary file for Summary Administration in Florida?
Yes. Florida probate courts utilize 100% digital filing systems. Out-of-state heirs in New York, New Jersey, or anywhere across the country can hire a local Florida probate lawyer to execute the entire proceeding remotely without ever stepping foot inside a courtroom.
How long does it take to get an Order of Summary Administration?
In South Florida courts (Broward, Miami-Dade, and Palm Beach counties), an uncontested Petition for Summary Administration typically takes 4 to 8 weeks from initial filing to final judge signature, depending on judicial caseloads.
Why Choose Reinfeld & Cabrera, P.A. for South Florida Probate?
Navigating court petitions while grieving a family member can feel overwhelming. At Reinfeld & Cabrera, P.A. (mypersonalattorneys.com), we simplify the Florida probate process with transparency and local courtroom experience:
Transparent Flat-Fee Pricing: We eliminate financial anxiety by offering predictable flat legal fees for uncontested Summary Administration—no hidden hourly bills.
Bilingual Legal Representation: Our attorneys and staff speak fluent English and Spanish, ensuring clear communication for non-English speaking beneficiaries.
Full-Service Local Filings: We handle all court communication across Broward (17th Judicial Circuit), Miami-Dade (11th Judicial Circuit), and Palm Beach (15th Judicial Circuit) counties.
If you need to transfer real estate, recover frozen bank accounts, or resolve an estate in South Florida, contact Reinfeld & Cabrera, P.A. today for a free case evaluation.
Direct Phone: (954) 334-1520 / (855) 529-7123
Coral Springs Office: 9625 W. Sample Rd, Coral Springs, FL 33065
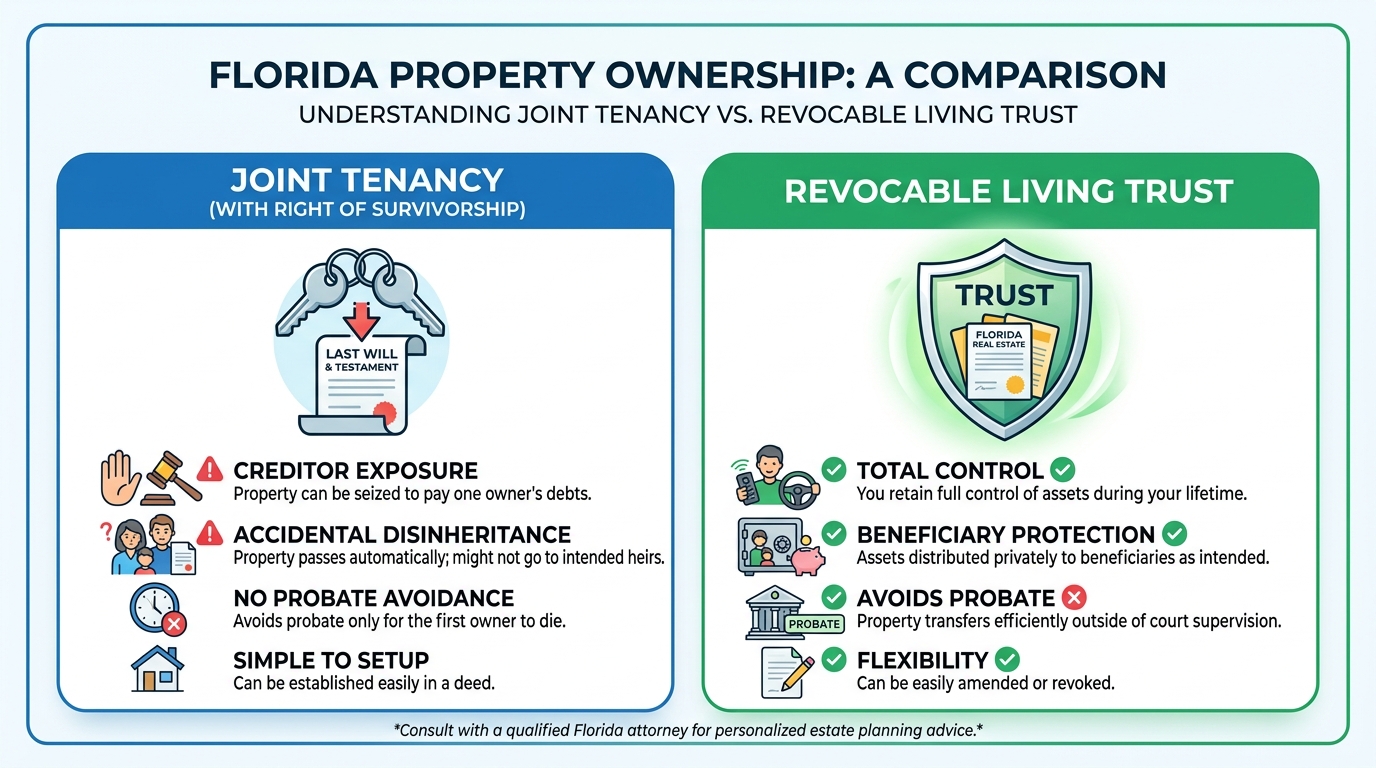
Joint Tenancy with Right of Survivorship (JTWROS) in Florida bypasses probate under Fla. Stat. § 689.15, but it completely overrides your Last Will and Testament. Upon the death of one joint owner, title vests immediately and automatically in the surviving owner. This exposes assets to the survivor’s future creditors, potential remarriage claims, and total disinheritance of biological children from prior marriages.
Governed by Will DirectivesJoint Tenancy completely overrides your Will. A Revocable Trust strictly enforces every distribution instruction in your estate plan.
Co Owner Creditor ProtectionJoint Tenancy exposes your assets to co owner debts and lawsuits. A Revocable Trust protects assets from third party beneficiary liabilities.
Many South Florida homeowners and account holders add adult children, second spouses, or relatives to bank accounts and real estate deeds as a quick shortcut to avoid formal probate court proceedings.
While adding a joint owner appears convenient on the surface, Joint Tenancy with Right of Survivorship (JTWROS) is one of the most unpredictable, blunt force mechanisms in estate planning. Under Florida property and probate law, joint titling strips away your lifetime financial control, exposes your hard earned assets to outside lawsuits, and routinely triggers accidental family disinheritance.
3 Fatal Vulnerabilities of Joint Ownership Under Florida Estate Law
1. Automatic Property Transfer Overrides Your Will and Intentions
Under Florida Statute § 689.15, when property or financial assets are held as joint tenants with right of survivorship, the deceased co owner’s interest transfers instantly to the surviving co owner upon death by operation of law.
Your Last Will and Testament, Revocable Trust instructions, or verbal promises made to family members carry zero legal weight. If a parent adds one adult child to a Coral Springs real estate deed purely for administrative convenience or convenience check writing, that child becomes the sole legal owner upon the parent’s death, completely cutting out their siblings regardless of what the parent’s Will specifies.
2. Immediate Asset Exposure to Co Owner Liabilities and Creditors
The moment you name a joint owner on a bank account or Broward County real estate deed, that individual gains immediate legal ownership rights. If your co owner faces a divorce proceeding, automobile accident lawsuit, business bankruptcy, or personal tax lien, judgment creditors can attach claims directly to your shared asset. You effectively gamble your lifelong financial security on your co owner’s personal financial discipline and legal stability.
3. The Blended Family Disinheritance Trap
In blended families with children from prior relationships, joint titling regularly causes catastrophic estate outcomes.
When a married couple holds real estate or bank accounts jointly with right of survivorship, all assets vest exclusively in the surviving spouse upon the first spouse’s death. When that surviving spouse eventually passes away, the entire estate passes to their personal biological children or designated heirs. The biological children of the spouse who passed away first receive nothing, creating permanent financial alienation between stepfamilies.
Real World Legal Case Study: In re Estate of Kester
A clear example of how joint titling destroys testamentary intent is illustrated in the official Florida legal precedent In re Estate of Kester, Fla. 4th DCA 1986), decided by the Fourth District Court of Appeal in West Palm Beach.
The Case Background
In this landmark dispute, a mother executed a formal Last Will and Testament directing that her entire estate be divided equally among her children. However, for everyday banking convenience, she established joint bank accounts and credit union shares with right of survivorship naming only one of her daughters as a co owner.
The Legal Conflict
Following the mother’s death, the siblings brought legal action in court, arguing that the funds in the joint accounts were intended for the benefit of all children under the terms of the mother’s Will, and that the joint owner held those funds merely as a fiduciary for the estate.
The Court Ruling
The Fourth District Court of Appeal ruled firmly against the other siblings. The appellate court held that under Florida statutory law governing joint accounts, titling an account as joint tenancy with right of survivorship creates a strong legal presumption of an absolute gift to the surviving joint owner.
Because the disappointed siblings could not provide clear and convincing written evidence proving the mother did not intend to create a survivorship right at the exact moment the accounts were established, the surviving joint daughter kept the entirety of the money. The clear instructions contained inside the mother’s Last Will and Testament were completely ignored and legally powerless.
Superior Florida Legal Alternatives to Joint Ownership
Rather than risking loss of control or accidental disinheritance through joint titling shortcuts, comprehensive estate plans utilize flexible legal structures designed under Florida statutory law:
1. Revocable Living Trust
Establishing a trust under Fla. Stat. Chapter 736 allows you to maintain 100 percent sole authority over your real estate and financial accounts during your lifetime. Upon death, your named successor trustee distributes property to your designated beneficiaries according to your exact written terms, achieving complete probate court avoidance without exposing your assets to co owner debts or disinheriting loved ones.
2. Florida Financial Durable Power of Attorney
If your main objective is allowing a trusted child or relative to assist with bill paying, property maintenance, or financial management during a health crisis, executing a Durable Power of Attorney (Fla. Stat. § 709.2104) grants them legal administrative authority without giving them property ownership rights or subjecting your assets to their personal creditors.
3. Enhanced Life Estate Deed (Lady Bird Deed)
For primary residential property in Coral Springs, Fort Lauderdale, or anywhere in Broward County, an Enhanced Life Estate Deed allows a property owner to retain total lifetime ownership rights, including the right to sell, lease, or mortgage the home without obtaining permission, while designating an automatic transfer on death beneficiary that completely bypasses Florida probate.
Frequently Asked Questions
Does joint ownership avoid probate in Broward County?
Yes, joint tenancy with right of survivorship avoids probate upon the death of the first co owner. However, when the surviving owner eventually passes away without establishing formal trust planning, the property must pass through formal Florida probate administration.
Can I remove a joint owner from my Florida real estate deed without their consent?
No. Once an individual is added to a deed as a joint tenant in Florida, you cannot remove them, sell the property, or execute mortgages without their formal notarized signature, even if you originally paid for the entire property yourself.
What is the legal difference between Joint Tenancy and Tenancy by the Entirety in Florida?
Tenancy by the Entirety is a specialized form of joint ownership reserved strictly for legally married couples under Florida law. It provides built in creditor protection against individual spouse liabilities that standard Joint Tenancy does not offer.
Can a Last Will override a joint bank account in Florida?
No. Under Florida law, joint accounts with right of survivorship transfer automatically upon death. A Last Will carries no legal authority to alter or redistribute funds held in a valid joint survivorship account.
Protect Your Property and Family Autonomy in Coral Springs
Selecting an estate planning and probate attorney in Coral Springs requires evaluating local Broward County courtroom experience, mastery of Florida trust statutes (Fla. Stat. Chapter 736), and integrated knowledge of Florida constitutional homestead laws (Fla. Const. art. X, § 4).
A qualified local attorney ensures wills, revocable trusts, and powers of attorney comply with strict execution requirements while guiding personal representatives through formal or summary probate proceedings in the 17th Judicial Circuit Court of Broward County.
Critical Evaluation Framework for Local Legal Counsel
Florida Statutory Compliance
Fla. Stat. Chapter 736 (Trust Code)
Fla. Stat. Chapter 709 (Durable Power of Attorney)
Fla. Stat. Chapter 765 (Health Care Directives)
Broward Judicial Experience
17th Judicial Circuit Court Rules
Local Broward Clerk Filing Protocols
Probate Division Judicial Orders
Reinfeld & Cabrera Legal Representation Hub
Securing your family’s financial future, protecting physical property, and ensuring seamless asset distribution requires thoughtful legal strategy. While online document assembly services promise cheap, automated legal templates, generic forms regularly fail under Florida probate court scrutiny.
Florida estate law involves intricate statutory execution rules, unique real estate protections, and strict probate filings across Broward County. Understanding how to choose an experienced local attorney is the single most important step in protecting your life savings and preserving your legacy.
5 Essential Standards When Evaluating Coral Springs Estate Legal Counsel
1. Direct Mastery of Florida Specific Estate and Trust Statutes
Florida law does not follow generic federal templates or out of state legal norms. Your legal counsel must maintain a daily transactional practice grounded in specific Florida legislation:
Florida Trust Code (Fla. Stat. Chapter 736): Regulates the creation, amendment, revoking, and administration of revocable and irrevocable trusts. It establishes strict fiduciary standards for named trustees and protects beneficiary distribution rights.
Florida Power of Attorney Act (Fla. Stat. Chapter 709): Governs financial durable powers of attorney. Under Florida law, general sweeping clauses are ineffective unless specific statutory superpowers under Fla. Stat. § 709.2114 are explicitly initialed by the principal.
Florida Probate Code (Fla. Stat. Chapters 731 through 735): Controls the judicial validation of wills, opening of estates, creditor notification periods, and final asset distribution.
Florida Health Care Advance Directives (Fla. Stat. Chapter 765): Outlines the legal appointment of health care surrogates, living wills, and anatomical gifts.
2. Local Courtroom and Judicial Experience in Broward County
Estate planning and probate are deeply localized practice areas. An attorney who regularly represents clients before the 17th Judicial Circuit Court in Fort Lauderdale understands local judicial preferences, divisional filing protocols, and clerk processing workflows.
When a loved one passes away, local judicial experience ensures that petitions for administration, orders appointing personal representatives, and letters of administration move through the Broward County probate court system without administrative rejections or unnecessary delays.
For the vast majority of Coral Springs and Parkland homeowners, primary residential real estate represents their largest asset. Under Florida Constitution Article X, Section 4, primary residential property enjoys unique protection from forced sale by creditors.
However, Florida homestead devise restrictions strictly limit how a primary home can be left in a Will or Trust if the owner is survived by a spouse or minor children. An experienced Coral Springs attorney knows how to structure deeds, trusts, and spousal waivers to preserve homestead protections while avoiding title clouding or unintended tax consequences.
Florida Constitutional Homestead Advantages
Creditor Exemption ProtectionProtects primary residential equity from forced sale by judgment creditors under Florida law.
Property Tax Cap LimitsLocks annual assessed property value increases under Florida Save Our Homes assessment caps.
Strict Devise RestrictionsProtects rights of surviving spouses and minor children regarding real estate transfers.
4. Comprehensive Probate Avoidance and Administration Capabilities
A complete legal counselor does not simply hand you a stack of paper and send you on your way. Your attorney must possess expertise across both proactive planning and reactive administration:
Incapacity Avoidance: Structuring financial durable powers of attorney and health care surrogates to prevent involuntary adult guardianship court hearings under Fla. Stat. Chapter 744.
Summary Probate Administration: Navigating expedited court proceedings under Fla. Stat. Chapter 735 for estates under $75,000 or where the decedent has been deceased for more than two years.
Formal Probate Administration: Managing complex court supervised estates requiring personal representative appointments, formal notice to creditors, estate accounting, and tax releases.
5. Proven Community Reputation and Legal Continuity
Estate planning is an ongoing lifetime relationship. As your family grows, assets change, and Florida tax laws evolve, your estate plan requires periodic reviews.
Recognized over the years by local Coral Springs community awards, Reinfeld & Cabrera, P.A. has established a decade long legacy of personal legal representation across Broward County. Choosing a stable, locally rooted firm ensures that the attorneys who drafted your trust will be available decades later to guide your loved ones through its execution.
Comparing Online DIY Legal Forms vs. Local Attorney Representation
Operational Feature
Online DIY Document Generator
Local Coral Springs Legal Counsel
Florida Execution Compliance
High risk of improper witnessing or notarization
Strict compliance with Fla. Stat. § 732.502
Homestead Protection Integration
Generic forms ignore Florida constitutional restrictions
Customized deed drafting and tax cap protection
Local Probate Court Knowledge
Zero court presence or regional administrative support
Direct filing experience in 17th Judicial Circuit Court
Fiduciary Guidance
No legal advice on selecting agents or trustees
Professional counseling on trustee appointment
Custom Contingency Planning
Rigid templates that fail during complex family changes
Bespoke trust structures adapted to family dynamics
Frequently Asked Questions
Why shouldn’t I use a basic online Will template in Florida?
Florida law requires strict execution formalities under Fla. Stat. § 732.502, including execution in the presence of two signing witnesses and a qualifying notary public. Online templates routinely miss unique Florida requirements, such as statutory power of attorney superpowers or constitutional homestead devise limits, rendering documents invalid or triggering expensive probate disputes.
What is the difference between summary administration and formal probate in Broward County?
Summary administration is an abbreviated court proceeding available if the total value of probate assets subject to administration is $75,000 or less, or if the decedent has been deceased for over two years. Formal administration is required for larger estates and involves appointing a personal representative to marshal assets, clear creditor claims, and manage distributions.
How often should I review my Coral Springs estate plan with an attorney?
You should review your estate plan every three to five years, or immediately following major life events such as marriage, divorce, the birth of a child, purchase of new real estate, significant changes in financial assets, or relocation to Florida from another state.
Can an out of state Will be used in Florida?
A Will executed in another state can be valid in Florida if it strictly met the execution laws of the state where it was signed. However, out of state Wills often name non resident personal representatives who may not qualify under Florida eligibility rules (Fla. Stat. § 733.304) or fail to utilize Florida specific probate shortcuts.
Dedicated Estate Planning and Probate Counsel in Coral Springs
At Reinfeld & Cabrera, P.A., lead attorney Alan J. Reinfeld and our legal team deliver tailored estate planning and probate solutions to South Florida families. We take the time to understand your personal goals, protect your real estate assets, and provide clear legal guidance through every stage of life.
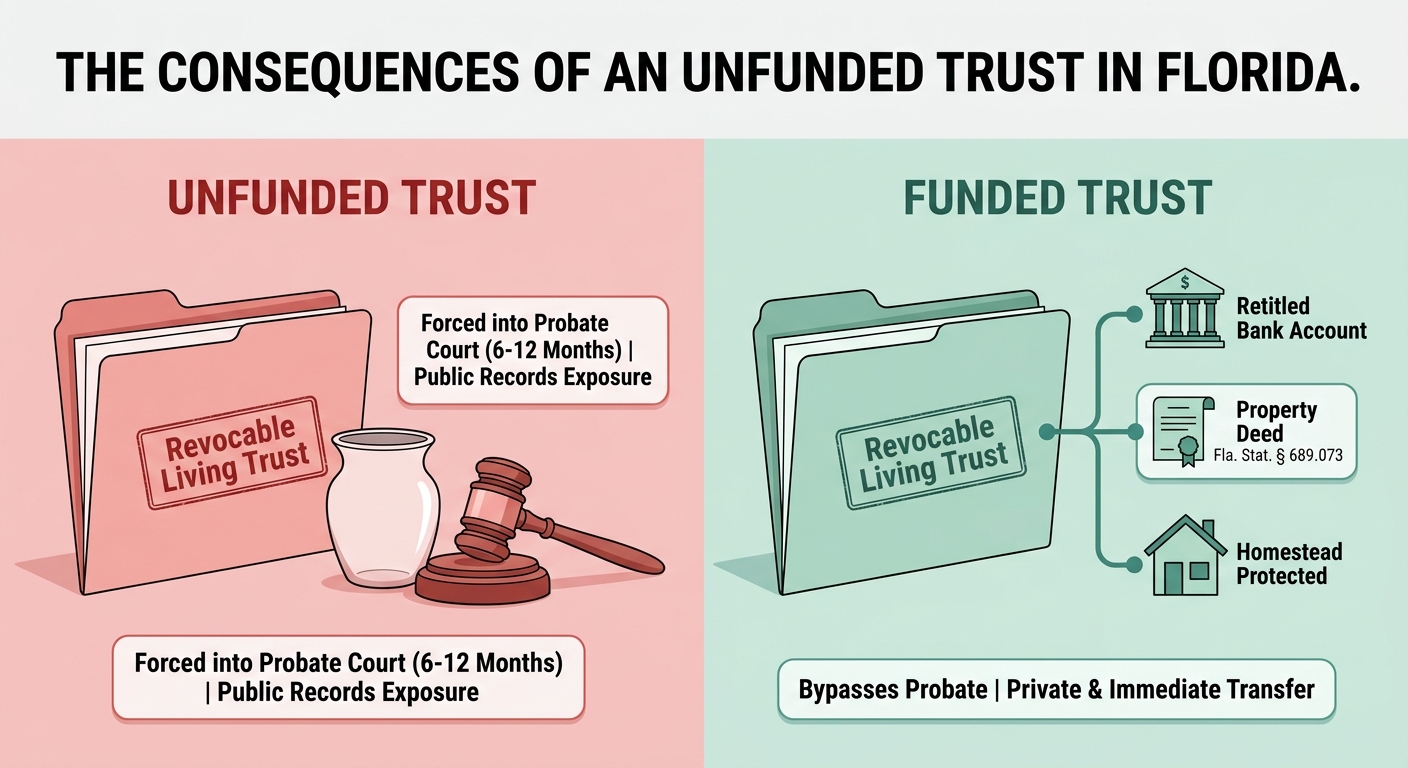
In Florida, a Revocable Living Trust is essentially an empty vessel with written instructions. Signing the trust document creates the legal framework, but if assets are not officially retitled into the name of the trust—a process known as funding—the trust cannot govern or transfer those assets upon your death or incapacity.
Here is an in-depth look at what happens in Florida when a trust remains unfunded, the legal consequences, and how Florida law resolves the gap.
1. The Core Problem: Loss of Probate Avoidance
The primary reason individuals establish revocable living trusts in Florida is to keep their assets out of probate court.
If Funded:Specifically, assets owned by ‘John Doe, as Trustee of the John Doe Revocable Trust’ pass directly to beneficiaries via the successor trustee according to the terms of the trust, bypassing probate court entirely.
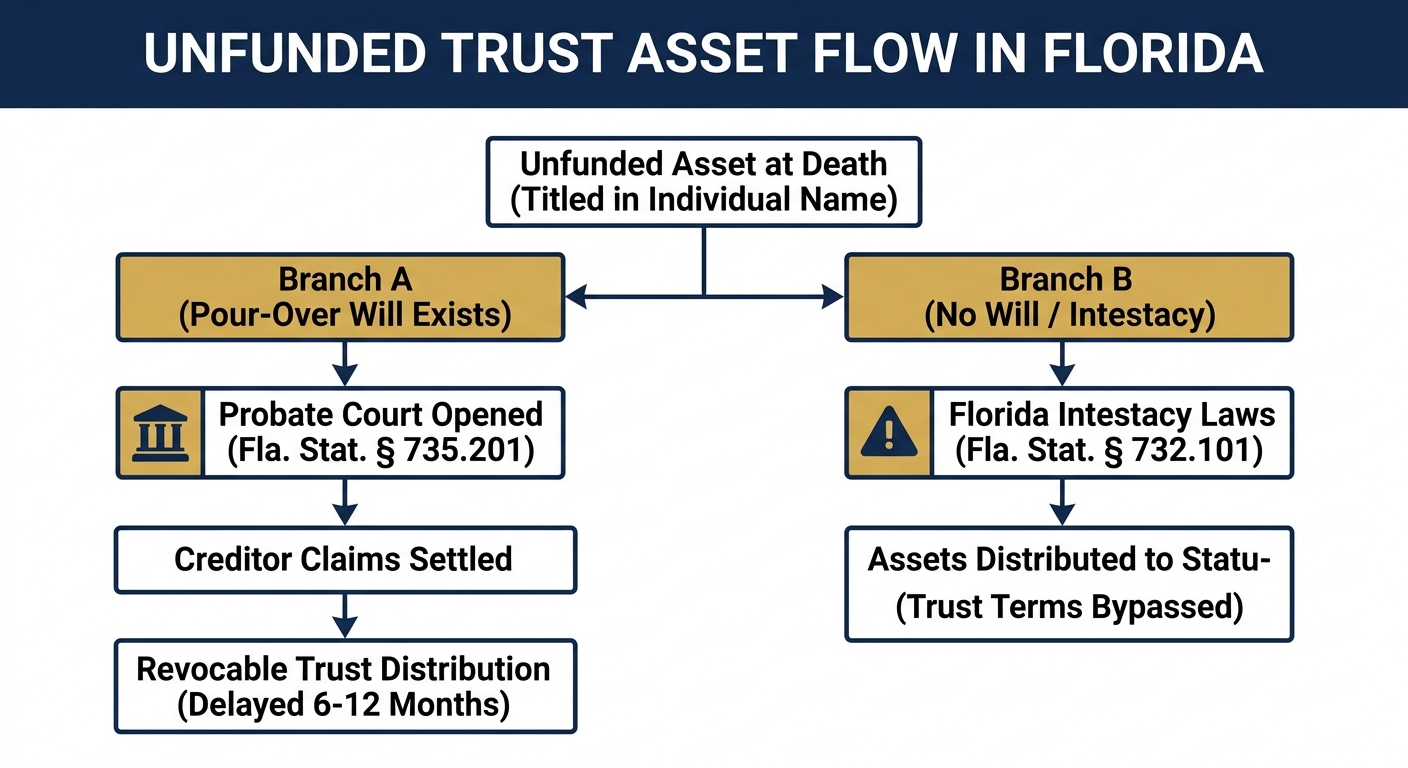
If Unfunded: Any asset that remains in an individual’s personal name at death (e.g., “John Doe”) forms part of the decedent’s probate estate. The trust document holds no legal authority over these individually titled assets.
2. The Legal Safety Net: The Florida “Pour-Over Will”
To protect against unfunded or forgotten assets, a properly executed Florida estate plan includes a Pour-Over Will.
How it works: The Pour-Over Will acts as a catch-all safety net. It states that any asset remaining in the individual’s name at death should be transferred (or “poured over”) into the trust.
The Catch:A Pour-Over Will must go through Florida Probate Court.
The Process:During this process, the court appoints a Personal Representative to collect the unfunded assets, satisfy valid creditor claims under Florida Probate Rules, and then transfer the remaining net assets to the trustee to distribute according to the trust’s instructions.
The Outcome: The wishes outline in the trust are eventually honored, but the estate experiences the exact court delays (6 to 12+ months), public record disclosures, and legal/court costs that the trust was designed to prevent.
3. What Happens If There Is No Pour-Over Will?
If a trust is unfunded and the creator (settlor) dies without executing a Pour-Over Will (or any valid Will):
Intestacy Laws Take Over: The unfunded assets pass according to Florida’s intestate succession laws (Fla. Stat. § 732.101 et seq.), which default to statutory family order (surviving spouse, adult children, parents, siblings).
Accidental Disinheritance:Furthermore, the trust’s provisions, such as leaving equal shares to children, funding charities, or holding money in trust for minors, are bypassed completely for those unfunded assets.
Key Complications Specific to Unfunded Trusts in Florida
Consequently, if real estate is not deeded to the trust using a properly drafted Quitclaim or Warranty Deed (specifying trust powers under Fla. Stat. § 689.073), the home remains individual property.
Upon death, the homestead therefore requires a court proceeding (a Petition to Determine Homestead) to pass free of claims to legal heirs, regardless of what the trust document outlines.
B. Loss of Incapacity Protection
A key function of a Florida revocable trust is managing assets if the creator becomes incapacitated (e.g., due to dementia or stroke).
Funded Trust: The successor trustee steps in smoothly to manage trust assets without court involvement.
Unfunded Trust: The successor trustee has no authority over individually owned bank accounts or real estate. Family members must instead rely on a Durable Power of Attorney or petition a Florida court for a costly Guardianship proceeding.
C. Exposure of Financial & Personal Privacy
Once probate is opened to catch unfunded assets, the estate inventory, financial balances, names of heirs, and trust references become part of the public court record in the county where the probate is filed.
Summary of Consequences
Scenario
Fully Funded Florida Trust
Unfunded Trust (with Pour-Over Will)
Unfunded Trust (NO Pour-Over Will)
Probate Required?
No (Bypasses court entirely)
Yes (Formal or Summary Administration required)
Yes (Must go through Intestate Probate)
Distribution Time
Immediate or within weeks
6 to 12+ months
6 to 12+ months
Privacy
Private (Kept out of court records)
Public (Will and asset inventories filed with court)
Public (Filed with court)
Who Inherits?
Trust Beneficiaries
Trust Beneficiaries (after probate completion)
Statutory Heirs under Florida Intestacy Laws
How Funding Is Completed in Florida
To fund a trust properly under Florida law:
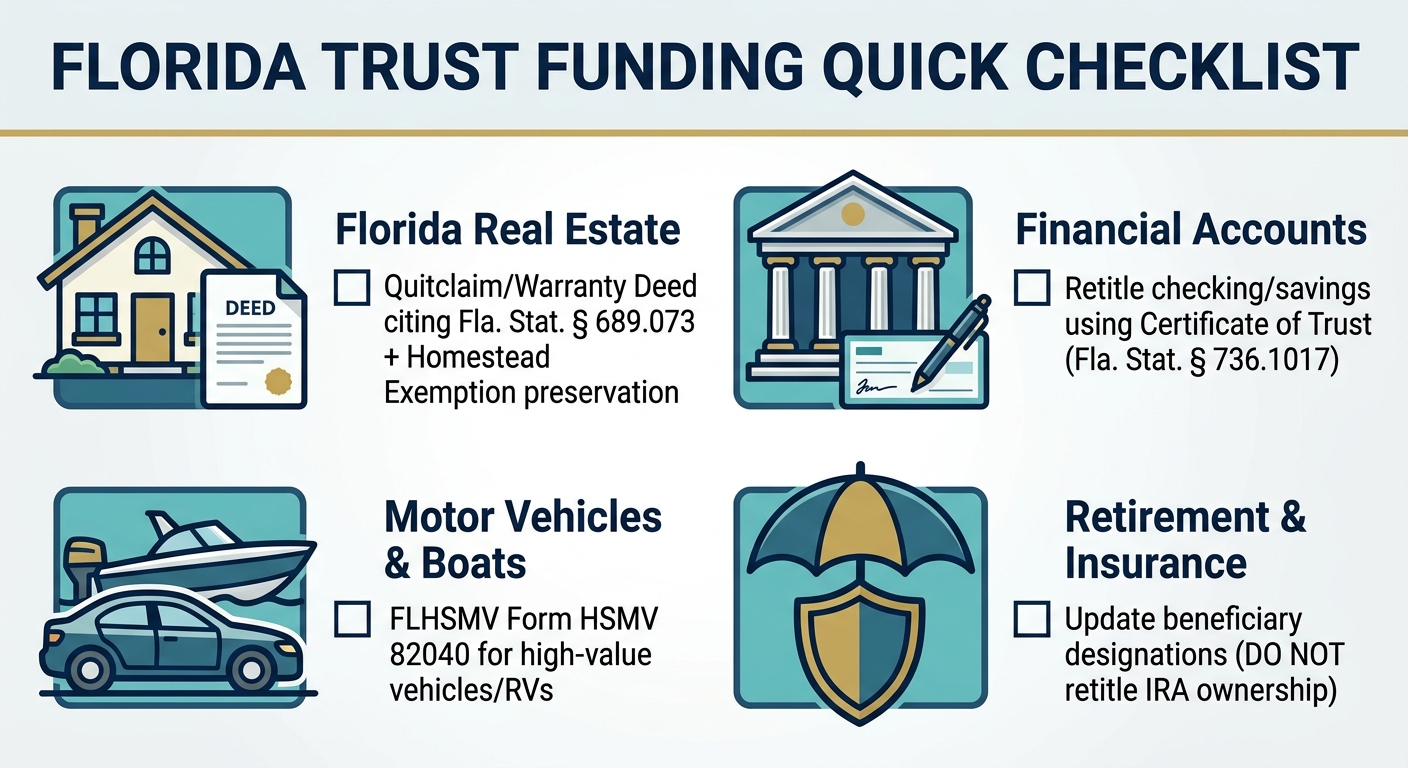
Real Estate: Draft and record a deed transferring title from the individual to the trust in the county where the property is located.
Financial Accounts: Change account ownership at banks and brokerages to the trust’s name.
Beneficiary Designations: Update primary or contingent beneficiary forms for life insurance policies, retirement accounts (IRAs/401ks), or Pay-on-Death (POD) accounts where appropriate.
Florida Revocable Living Trust Funding Checklist
A Revocable Living Trust cannot avoid probate or manage assets until those assets are retitled into the trust’s name. Follow this streamlined checklist to ensure your trust is properly funded under Florida law.
Essential Prerequisites
Certificate of Trust (Fla. Stat. § 736.1017): Provides banks, brokers, and title companies proof of trustee authority without exposing private beneficiary details.
Standard Trust Titling Format: [Trustee Name(s)], Trustee(s) of the [Trust Name], dated [Execution Date]
Quick-Action Asset Checklist
1. Bank Accounts & Cash Assets
Checking & Savings: Present your Certificate of Trust at your bank to retitle existing accounts or open new trust accounts.
Certificates of Deposit (CDs): Confirm in writing first that the bank will waive early withdrawal penalties for trust transfers before retitling.
Safe Deposit Boxes: Execute a new lease naming the trust or trustee to ensure immediate successor access.
2. Florida Real Estate
Deed Execution: Record a Quitclaim or Special Warranty Deed transferring title to the trustee.
Statutory Protection (Fla. Stat. § 689.073):To be valid under Florida law, the deed must explicitly grant the trustee full power to sell, lease, or encumber property.”
Preserve Homestead Exemptions: Include homestead occupancy rights in the deed/trust to safeguard tax caps (Fla. Admin. Code 12D-7.011) and creditor exemptions (Fla. Const. Art. X, § 4).
3. Motor Vehicles & Vessels (FLHSMV)
Selective Retitling: Under Fla. Stat. § 319.28, Florida allows heirs to transfer simple vehicle titles outside probate. We primarily recommend retitling high-value vehicles, RVs, or boats directly into the trust via FLHSMV Form HSMV 82040.
4. Investment Accounts & Non-Probate Assets
Brokerage Accounts: Submit ownership change forms to custodians (Schwab, Fidelity, Vanguard) along with your Certificate of Trust.
Life Insurance: Assign the trust as the primary or contingent beneficiary to ensure immediate, unencumbered payout administration.
Tax-Deferred Accounts (IRAs/401ks):However, do not retitle ownership, as this triggers immediate tax liabilities. Instead, update beneficiary designations carefully following SECURE Act 2.0 guidelines.
Complete Your Trust Execution with Experienced Counsel
Ensure your real estate, financial accounts, and business assets are properly structured under Florida law. Contact our South Florida estate planning team today:
Direct Telephone: (954) 866-4878 | Toll-Free: 954-866-HURT
Coral Springs Office: 9625 W. Sample Rd, Coral Springs, FL 33065
Fort Lauderdale Office: 2933 W. Cypress Creek Rd, Suite 201, Ft. Lauderdale, FL 33309
Website: mypersonalattorneys.com
Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and all surrounding areas of Broward County
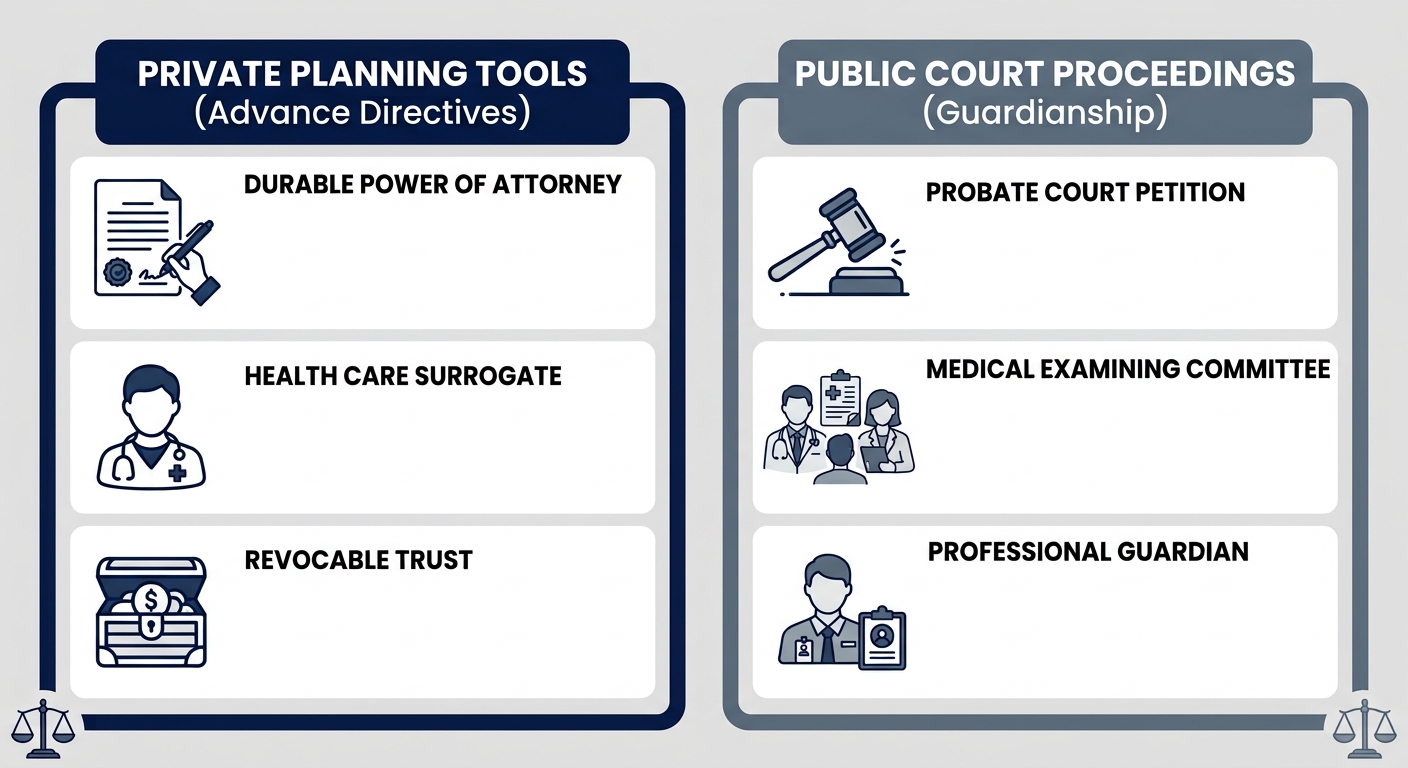
In Florida, adult guardianship is avoided by executing three proactive, legally binding instruments while mentally competent: a Durable Power of Attorney (Fla. Stat. § 709.2104), a Designation of Health Care Surrogate (Fla. Stat. § 765.202), and a Revocable Living Trust. Together, these documents grant immediate, private decision-making authority to chosen surrogates, preventing the 17th Judicial Circuit Court of Broward County from declaring incompetence or appointing a court-monitored professional guardian under Fla. Stat. Chapter 744.
Why a Florida Last Will and Testament Fails During a Lifetime Health Crisis
The most pervasive misconception among Florida property owners is the belief that a well-crafted Will protects their business, real estate, and financial accounts if they suffer a debilitating stroke, traumatic brain injury, or severe cognitive decline.
A Will is legally dormant until death. It grants zero authority during your lifetime.
If you lose legal capacity without specific lifetime governance documents, your family cannot simply present your Will to Bank of America, Chase, or a Broward County title company. Instead, your loved ones are forced into a rigid, public, and adversarial legal process known as Involuntary Adult Guardianship.
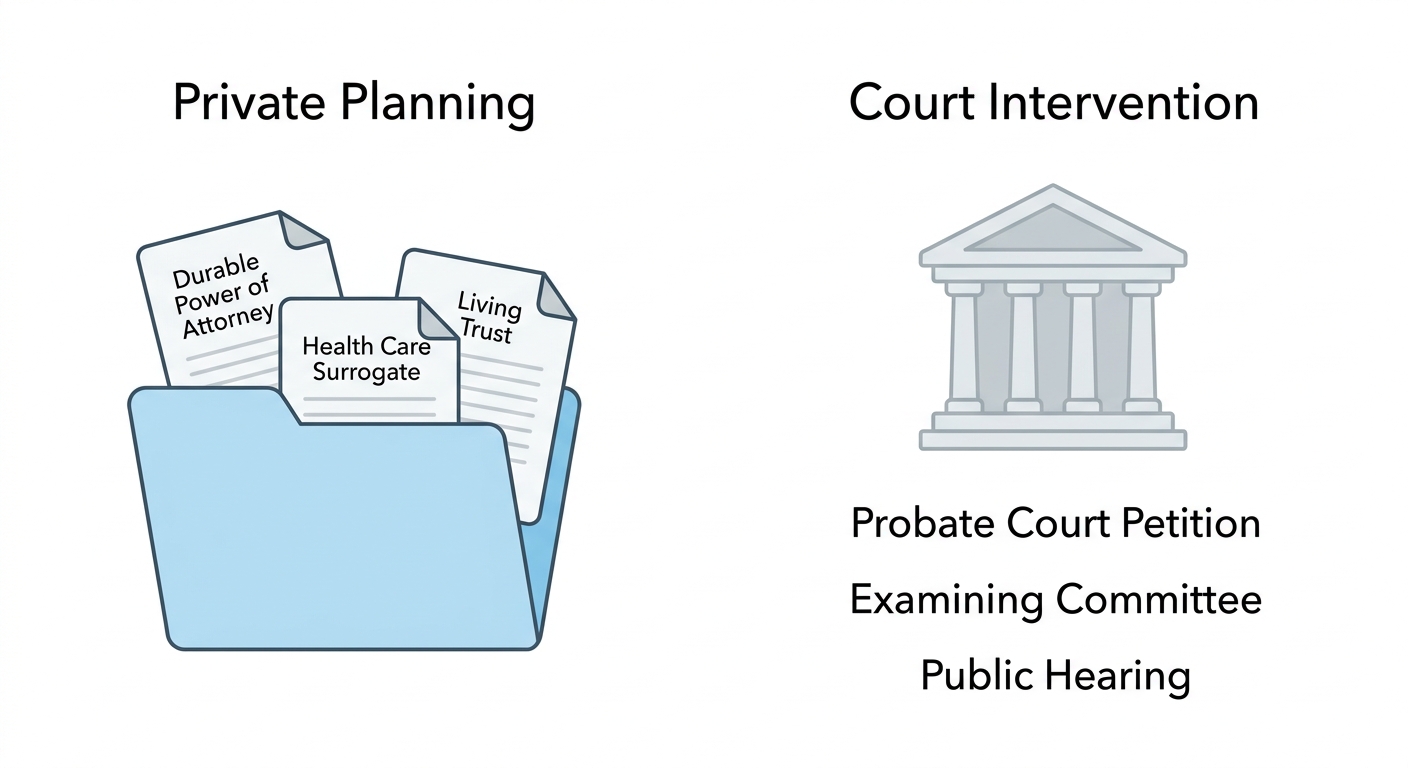
Path A: Proactive Planning (Private)
Path B: Court Intervention (Guardianship)
1. Key Legal Instruments:
Durable Power of Attorney
Health Care Surrogate
Revocable Living Trust
1. Emergency Court Petition:
Filed in the Broward County Circuit Court by family, health care providers, or interested third parties.
2. Immediate Authority:
Your designated agent or trustee steps in immediately without court permission.
2. 3-Member Examining Committee:
Court appoints a physician, medical expert, and layperson to evaluate your mental competency.
3. Privacy & Autonomy:
Financial affairs and health decisions remain strictly private within the family.
3. Public Incompetency Hearing:
Formal court hearing stripping fundamental constitutional rights and declaring legal incapacity.
Final Outcome: Seamless Family Management
Zero court fees, no public record, immediate operational continuity.
Final Outcome: Court Guardian Control
Appointed professional guardian, mandatory annual audits, assets drained by legal fees.
The Financial and Personal Realities of Florida Guardianship Proceedings
When a court petition is filed under Florida Statute Chapter 744, you become the “Alleged Incapacitated Person” (AIP). The judicial process moves quickly, privately stripping personal freedoms through public records:
1. Mandatory 3-Member Examining Committee
Under Fla. Stat. § 744.331, the court appoints an examining committee consisting of three professionals (at least one must be a medical doctor or psychiatrist). These individuals visit your home or hospital room, conduct cognitive testing, and submit written assessments directly to the Broward County judge.
2. Immediate Loss of Fundamental Civil Rights
If the court finds you incapacitated, you do not just lose access to your checking account. You lose the legal right to:
Contract, sign deeds, or manage business interests
Choose where you live or consent to medical treatment
Vote, hold a driver’s license, or marry
Retain personal legal counsel of your choice
3. The Financial Strain of Professional Guardianship
A court-appointed guardian is entitled to reasonable compensation paid directly out of your assets. Every financial move—selling a home in Coral Springs, liquidating stock, or paying for specialized memory care—requires formal court petitions, attorney appearances, and annual financial audits overseen by the clerk of court.
Real World Precedent: How Lack of Planning Triggers Systemic Vulnerability
To understand why Florida courts step in so forcefully, one needs to look no further than the notorious state guardianship cases that led to major legislative reforms across South Florida.
Consider the real life case of Jan Garwood, a Central Florida resident who suffered a sudden medical crisis without a complete, active incapacity plan in place.
┌────────────────────────────────────────────────────────┐
│               THE REALITY OF COURT CONTROL             │
├───────────────────────────┬────────────────────────────┤
│    WITHOUT A DPOA / TRUST │  WITH PROACTIVE R&C PLAN   │
├───────────────────────────┼────────────────────────────┤
│ Forced court petition     │ Private family transition  │
│ 3-person medical panel    │ Designated agent steps in  │
│ Court-appointed guardian  │ Zero court costs or fees   │
│ House sold without consent│ Assets fully protected     │
└───────────────────────────┴────────────────────────────┘
After an emergency hospital admission under the Baker Act, the hospital petitioned the court to appoint a professional guardian. Because Garwood lacked a updated Durable Power of Attorney and Revocable Living Trust specifically naming trusted family members to handle her affairs:
The Court Intervened Immediately: A judge declared her incompetent based on brief examining committee reports, bypassing her family.
Loss of Property: The court appointed professional guardian gained complete control over her finances, eventually selling her home to cover facility care costs.
Loss of Autonomy: Garwood spent three years in a locked assisted living facility before independent attorneys managed to restore her rights, by which time her personal assets had been liquidated.
Cases like Garwood’s—and the widespread Florida state investigations into court appointed guardians that followed—highlight a critical legal reality: If you do not choose your own decision makers through private estate planning documents, a Florida probate court will choose one for you.
The Incapacity Avoidance Triad: 3 Key Documents
To lock out judicial interference, an incapacity strategy must unite three precise legal instruments under Florida law:
1. Florida Financial Durable Power of Attorney (DPOA)
Governed by Fla. Stat. § 709.2104, a Florida DPOA must contain specific “superpowers” (explicit initialed clauses under Fla. Stat. § 709.2114) granting your named agent the legal right to manage real estate, conduct banking, handle tax returns, and qualify for governmental benefits without court approval.
2. Florida Designation of Health Care Surrogate
UnderFla. Stat. § 765.202, this instrument allows your named surrogate to consult with doctors, review HIPAA-protected medical records, authorise surgeries, and make end-of-life decisions if you become unable to provide informed consent.
3. Revocable Living Trust
Holding property, financial accounts, and business equity inside a revocable trust creates an unbroken chain of authority. If you face incapacity, your named Successor Trustee steps in seamlessly to manage trust assets according to your written directives, eliminating the need for court supervision.
Frequently Asked Questions
Can my spouse automatically handle my finances if I become incapacitated?
No. Spousal status alone does not grant legal authority to sign deeds, alter bank accounts, or manage individually held assets in Florida. Without a valid Durable Power of Attorney or Trust, a spouse must petition the court for guardianship just like any third party.
What is the difference between a Power of Attorney and a Guardian?
A Power of Attorney agent is chosen privately by you while you are mentally sound. A Guardian is appointed by a judge after a court determination of incompetence.
Does a Durable Power of Attorney expire upon incapacity in Florida?
No. Unlike a standard power of attorney, a Durable Power of Attorney explicitly remains effective during temporary or permanent mental incapacity under Fla. Stat. § 709.2104.
Protect Your Independence with a Coral Springs Estate Planning Attorney
Maintaining total control over your health choices, personal dignity, and financial assets requires clear legal planning before a sudden health crisis occurs.
The estate planning attorneys at Reinfeld & Cabrera, P.A. help individuals and families across Coral Springs, Fort Lauderdale, and Broward County construct airtight incapacity plans that bypass court intervention entirely.
Under Florida law, a minor child cannot legally hold direct title to real estate, financial accounts, or large inheritances.
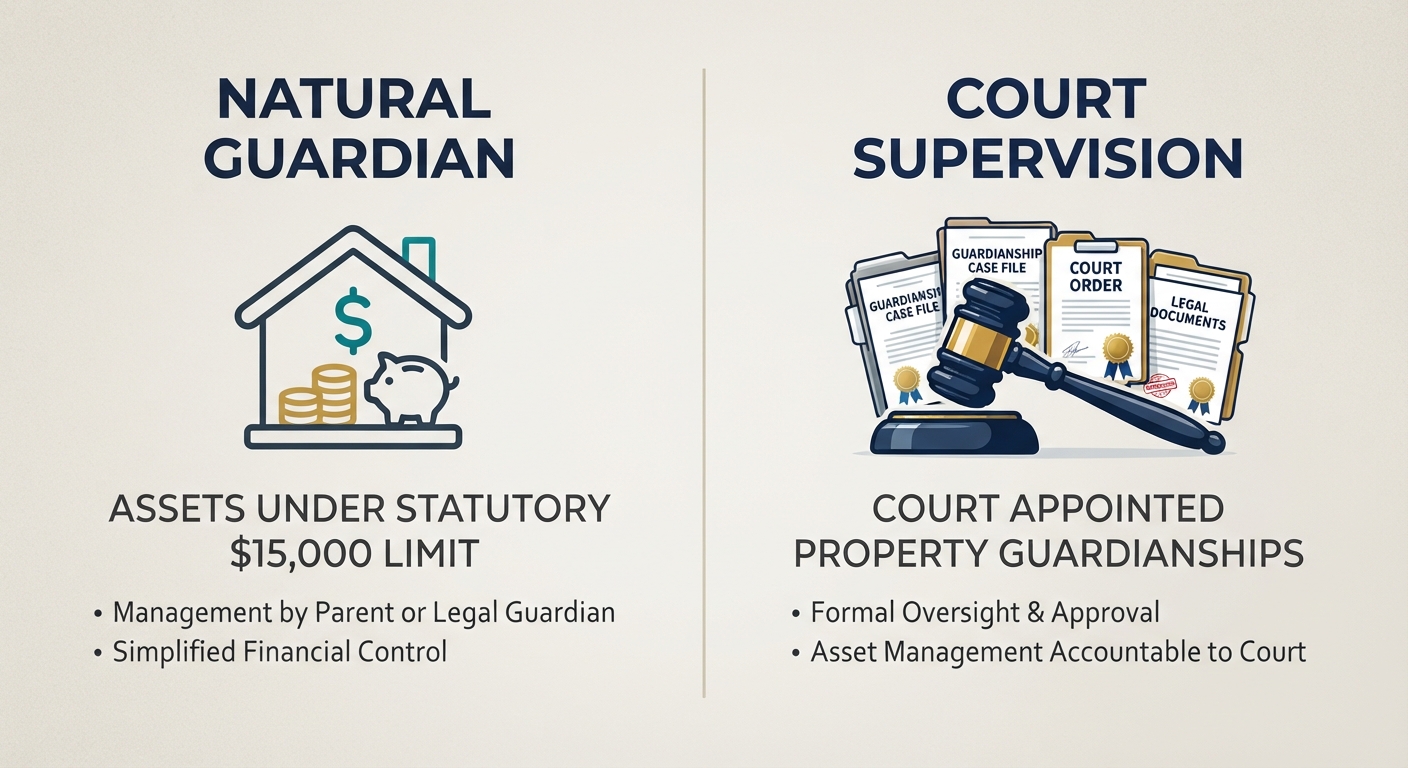
If a child receives property valued above the $15,000 statutory threshold under Florida Statute § 744.301 without a designated trust or custodial structure, the 17th Judicial Circuit or local probate court will typically require the formal appointment of a Guardian of the Property to oversee and manage the assets until the child turns eighteen.
UTMA Custodial AccountFlexible management without ongoing court oversight. Can extend distribution timing up to age 25.
Revocable Living TrustPrivate trustee control with custom phased distribution rules, completely bypassing public probate and guardianship courts.
Parents often assume that if something happens to them, any money, insurance proceeds, or real estate left behind will simply pass to their children and be managed by the surviving family members seamlessly.
In reality, Florida law draws a sharp legal line between who inherits property and who has the legal capacity to manage it. Because minors lack the legal standing to sign deeds, execute financial transfers, or control significant assets, an unintended inheritance triggers a complex web of probate rules, statutory thresholds, and court oversight.
1. Can a Minor Inherit Money or Property in Florida?
Yes. Legally, a minor child has every right to be named as a beneficiary in a Last Will and Testament, a life insurance policy, a retirement account, or a real estate deed.
However, owning property and controlling property are entirely different matters. While a child can legally own an asset, they cannot manage, sell, or spend it. If an estate distribution results in a minor receiving direct funds or real estate without a pre-arranged legal structure, the probate court steps in to freeze direct access until a qualified adult is formally authorized by a judge.
2. The $15,000 Threshold: Natural Guardianship Limits
Under Florida Statute § 744.301, biological or adoptive parents are recognized as the “natural guardians” of their minor children. As natural guardians, parents have the authority to manage minor property only if the total gross value of the personal property does not exceed $15,000.
If a child inherits an amount exceeding that $15,000 threshold—whether through a bank account, an investment portfolio, or a wrongful death settlement—a natural guardian cannot simply deposit or manage the funds. A formal Guardianship of the Property must be opened through the local probate court.
3. Case Study: Two Young Children Inherit a Large Estate (In re Matter of Castro)
To understand how Florida courts handle management disputes when children inherit major assets, consider the landmark Florida appellate decision in In re Matter of Castro, 344 So. 2d 270 (Fla. 3d DCA 1977).
The Facts: Following a father’s death, two young children ages four and six inherited a substantial estate. The children’s mother petitioned to be appointed as the legal guardian of their property. The trial court initially bypassed the mother and appointed an outside attorney, citing potential conflicts because of surrounding family circumstances.
The Ruling: The Third District Court of Appeal reversed the trial court, holding that Florida law establishes a strong statutory preference for qualified next of kin (such as a parent) to serve as guardian. A potential conflict, without concrete evidence establishing unfitness or disqualification, is not enough to strip a parent of their statutory preference. The court ordered the mother appointed as guardian, subject to posting a proper fiduciary bond.
The Takeaway:Castro demonstrates that inheriting property and deciding who manages that property are distinct legal hurdles. Even when a parent holds a natural preference, stepping into the role of formal property guardian requires navigating strict judicial scrutiny, background checks, and court bonds.
4. What Happens When a Minor Inherits Real Estate?
Real estate introduces some of the most complex hurdles in Florida probate and guardianship law.
If a grandparent leaves a home in Coral Springs or Broward County directly to minor grandchildren, the children cannot sign a listing agreement, execute a deed, or manage the property expenses.
The Guardianship Barrier: To sell, lease, or mortgage minor-owned real estate, a guardian of the property must petition the probate court for explicit authorization. Every major transaction requires judicial approval to ensure the minor’s financial interests are protected.
The Insurance and Tax Burden: Real estate requires continuous funding for property taxes, homeowner insurance, and maintenance. If the estate or guardianship lacks liquid cash to cover these ongoing carrying costs, the court may be forced to order a rush sale of the family property.
5. Case Study: A Minor, a Trust, and Insurance Proceeds (In re Estate of Weymer)
Another layer of complexity arises when insurance proceeds or estate assets flow through secondary legal structures. This dynamic was central toIn re Estate of Weymer, 199 So. 2d 495 (Fla. 4th DCA 1967).
The Facts: A father passed away leaving a residuary trust under his will for the primary benefit of his minor daughter. The father also maintained a life insurance policy payable directly to his estate. The executor collected the insurance funds, prompting the court appointed guardian of the minor’s property to demand those proceeds on behalf of the child.
The Ruling: The Fourth District Court of Appeal analyzed how insurance proceeds passing through an estate interact with testamentary trust provisions and minor beneficiaries, examining how funds must be segregated and accounted for while in the hands of estate fiduciaries.
The Takeaway:Weymer highlights why holding and administering a child’s money is completely separate from determining who inherited it. When insurance and estate assets collide, fiduciaries must carefully untangle whether funds belong directly to a guardianship estate or are funneled through a trust administration framework.
6. Does a Child Automatically Get an Inheritance at 18 in Florida?
A common misconception among parents is that establishing a guardianship or minor account locks up money until a child reaches maturity, at which point they handle it responsibly. In reality, “minor” status ends abruptly at age eighteen in Florida.
The table below illustrates how different legal structures dictate what happens when a child reaches adulthood:
Holding Structure
Management During Minority
What Happens at Age 18
Guardianship of Property
Court supervised, annual accounting, strict bond requirements
Terminates automatically. The 18 year old receives absolute, unrestricted control over the entire balance.
UTMA Custodial Account
Managed by a designated custodian without court supervision
Terminates at age 18, 21, or can be structured up to age 25 if properly designated at inception.
Revocable Living Trust
Managed privately by a trusted trustee according to custom terms
Controlled completely by the trust agreement. Distributions can be delayed, phased (e.g., portions at 25 and 30), or tied to milestones.
7. Frequently Asked Questions
Can a parent use a child’s inheritance to pay for family living expenses?
Generally no. Under Florida law, parents have a legal duty of support. A guardian of the property cannot use a child’s inherited funds to cover basic household rent, food, or clothing without explicit, prior authorization from the probate judge.
What is the difference between a guardian of the person and a guardian of the property?
A guardian of the person makes personal, medical, and educational decisions for the child. A guardian of the property manages financial assets, investments, and real estate. In many cases, these can be separate individuals or corporate fiduciaries.
How does a UTMA account differ from a formal trust?
A Uniform Transfers to Minors Act (UTMA) account is a simplified custodial arrangement ideal for smaller asset amounts. However, unlike a comprehensive Revocable Living Trust, a UTMA offers zero protection against a young adult gaining full access to the funds the moment they reach the statutory cutoff age.
Protect Your Children’s Future in Coral Springs
Leaving minor children unprotected against the rigid mechanics of Florida guardianship and probate courts can jeopardize their financial security.
A Lady Bird Deed in Florida is an enhanced life estate deed that allows a property owner to name someone who will receive the property after the owner’s death while retaining broad control over the property during life.
Unlike a traditional life estate, a properly drafted Lady Bird Deed can allow the owner to sell, mortgage, or otherwise convey the property without the future beneficiary’s permission. It can also allow the property to pass outside the ordinary probate process.
Because Florida does not have a statutory form called a “Lady Bird Deed,” the language used in the deed is especially important.
How Does It Work?
The property owner transfers the property through a deed that reserves an enhanced life estate and identifies one or more people who are intended to receive the property after the owner’s death.
During the owner’s lifetime, the owner generally retains the right to:
Live in and use the property
Sell the property
Mortgage the property
Convey the property to someone else
Change or defeat the beneficiary’s future interest, depending on the deed’s language
If the owner dies while the deed remains effective, the property can pass to the designated beneficiary without becoming part of the owner’s probate estate.
The exact result depends on the language of the deed and the circumstances surrounding the property.
Lady Bird Deed vs. a Regular Life Estate
The most important difference is the amount of control retained by the original owner.
With a traditional life estate, the owner keeps the right to possess and use the property for life but gives another person a present remainder interest. Selling or mortgaging the entire property can therefore require the remainderman’s participation.
An enhanced life estate, by contrast, can reserve the owner’s power to sell, mortgage, or convey the property without the beneficiary joining the transaction.
Florida courts have recognized this distinction. In Hirschenson v. Compu-Link Corp. of MI, the Third District Court of Appeal discussed an enhanced life estate as allowing the holder to sell, convey, mortgage, and otherwise manage the property without the remainderman’s joinder.
Does It Avoid Probate?
One reason Florida property owners consider this type of deed is probate avoidance.
If the deed is properly executed and remains effective when the owner dies, the designated beneficiary can receive the property without the real estate passing through the owner’s ordinary probate estate.
That does not mean every Lady Bird Deed will accomplish the same result. The deed must be legally effective, the property’s ownership must be correctly identified, and other Florida property laws may affect the transfer.
Why the Deed’s Language Matters
The enhanced powers need to be clearly established in the deed.
A Florida appellate case illustrates what can happen when the language is unclear. In Hirschenson, the deed contained inconsistent language concerning the power to mortgage the property. The resulting dispute required the court to determine what the deed actually meant, and the trial court ultimately reformed the deed. The appellate court affirmed that decision.
This is why a Lady Bird Deed should not simply be copied from an unidentified online form.
Can You Sell or Mortgage the Property?
A properly drafted enhanced life estate deed can preserve the owner’s ability to sell or mortgage the property without obtaining the future beneficiary’s consent.
That retained control is one of the defining characteristics of the arrangement.
However, the specific deed should be reviewed before a sale or mortgage. The deed’s wording, the property’s current title, and the requirements of the lender or title company can all matter.
What If the Beneficiary Dies First?
This depends on how the deed was drafted.
If the named beneficiary dies before the property owner, the deed should be reviewed to determine what happens to that person’s future interest. The owner may want to name alternate beneficiaries or include other provisions addressing this possibility.
This is one reason the beneficiary provisions should be considered carefully when the deed is prepared.
What If the Property Is Florida Homestead?
Homestead property requires additional care.
Florida law places special restrictions on the disposition of homestead, particularly when the owner has a spouse or minor children. Sections 732.4015 and 732.4017 of the Florida Statutes address important rules concerning homestead and lifetime transfers.
A Lady Bird Deed involving a Florida homestead therefore should not be evaluated solely on whether it can avoid probate. The owner’s family situation, title, and homestead status should all be considered before the deed is prepared.
Who Actually Owns the Property?
Before preparing the deed, it is important to determine how the property is currently titled.
For example, the property may be owned individually, jointly, through a trust, or subject to an existing interest.
In Johnson v. Johnson, Florida’s First District Court of Appeal considered enhanced life estate deeds that had been prepared in an individual’s name even though the properties were actually held by a living trust. The court affirmed reformation of the deeds based on the evidence concerning the mistake.
The practical lesson is simple: the current deed and ownership records should be checked before preparing a new conveyance.
When Might a Lady Bird Deed Be Useful?
A Florida property owner may consider an enhanced life estate deed when the goal is to:
Retain control of the property during life
Continue living in the property
Designate who should receive it after death
Preserve the ability to sell or mortgage the property
Potentially transfer the property outside probate
It may not be appropriate for every estate plan. More complicated family circumstances, multiple properties, trusts, creditor issues, or other planning concerns may call for a different approach.
It is an enhanced life estate deed that allows a property owner to retain substantial control over real estate while designating who should receive the property after the owner’s death.
Does a Lady Bird Deed avoid probate?
A properly drafted and effective deed can allow the property to pass to the designated beneficiary outside the ordinary probate process.
Is a Lady Bird Deed the same as a life estate?
No. A Lady Bird Deed is an enhanced form of life estate that can reserve significantly greater powers for the original owner.
Can I sell my house after signing a Lady Bird Deed?
Generally, an enhanced life estate can preserve the owner’s power to sell or convey the property without the beneficiary’s consent. The specific deed should be reviewed to confirm the powers it reserves.
Can I mortgage property with a Lady Bird Deed?
A properly drafted deed can reserve the owner’s power to mortgage the property. The exact language matters.
What happens when the owner dies?
If the deed remains effective and the property has not otherwise been conveyed, the designated beneficiary can receive the property according to the deed’s terms, potentially without probate.
Does a Lady Bird Deed work for Florida homestead?
It can, but Florida’s homestead rules create additional considerations involving spouses, minor children, and the owner’s particular circumstances.
Florida Estate Planning Attorneys Serving South Florida
A Lady Bird Deed can be a useful way to plan for the future of Florida real estate while retaining control during life. But the deed needs to match the property’s title and the owner’s circumstances.
Florida does not require every homebuyer to hire an attorney, but legal review can be valuable before signing a purchase contract. A real estate attorney can identify contractual, title, ownership, and closing issues that may affect your rights as a buyer.
For a home purchase in Coral Springs or elsewhere in Broward County, the legal review may involve:
Title: Examining the ownership history and identifying liens, judgments, probate issues, defective deeds, easements, or other recorded interests.
Deed and ownership: Determining how the property will be titled and whether the proposed ownership structure fits the buyer’s circumstances.
Closing: Reviewing documents and addressing unresolved legal issues before ownership transfers.
Florida homestead: Evaluating homestead considerations when the property will be the buyer’s primary residence.
Estate planning: Considering how the new property fits into the buyer’s will, trust, and broader estate plan.
Probate: Identifying potential probate issues when the property was inherited or when its future transfer may involve an estate.
The timing of the legal review matters. A lawyer who examines the transaction before the purchase contract is signed may be able to identify provisions that become difficult to change later. Title and ownership issues should also be addressed before closing, when resolving them can become more complicated.
For buyers in Coral Springs and Broward County, these questions arise under Florida real estate law, but the appropriate legal strategy depends on the specific property, contract, ownership structure, and family circumstances.
When should you hire a real estate attorney?
Many buyers think about hiring a lawyer when they reach the closing table. By that point, the most important contractual decisions may already have been made.
The purchase contract establishes the legal framework for the transaction. It can determine the buyer’s rights concerning financing, inspections, repairs, deposits, title, closing dates, and termination.
The Florida Bar recommends consulting an experienced Florida real estate lawyer before signing a purchase contract. Its consumer guidance explains that important provisions can become difficult to change once the agreement has been signed.
That timing matters whether you are buying a home in Coral Springs, Fort Lauderdale, Parkland, Coconut Creek, or another Broward County community.
Suppose an inspection later reveals substantial roof damage. The buyer may want the seller to make repairs or provide a credit. Whether the buyer can demand either remedy depends on the contract and the circumstances surrounding the transaction.
The same principle applies to financing problems, delays, title defects, and disputes about property condition.
A lawyer who reviews the agreement before signature can explain what the buyer has agreed to and identify provisions that deserve attention.
What does a real estate attorney do for a homebuyer?
The work depends on the transaction.
A real estate attorney may review the purchase agreement, examine title records, review the deed, address liens and judgments, examine closing documents, advise on ownership, and represent the buyer if a dispute develops.
Some transactions require little legal intervention after the contract and title are reviewed. Others become complicated because of the property’s history.
A house in Broward County may have changed hands several times. A previous owner may have died. A divorce may have affected ownership. An old mortgage may remain in the public record. A judgment may have attached to an owner’s interest. A deed may contain an error.
The current seller may have no knowledge of any of these issues.
That does not necessarily prevent the sale. It does mean that the issue should be identified and resolved before the buyer accepts the property.
For a buyer purchasing a home in Coral Springs, the property’s recorded history deserves the same attention as its current condition.
Why title matters when buying a house
A real estate listing tells you who is selling the property. It does not establish the entire legal history of the property.
A title examination looks at recorded documents affecting ownership. Depending on the property, those records may include deeds, mortgages, liens, judgments, probate documents, and other instruments.
Florida law governs the recording of interests in real property. Florida Statutes Section 695.01 addresses the recording of conveyances, mortgages, and other interests in land and explains when recorded instruments have priority against certain creditors and subsequent purchasers.
For a buyer, the practical issue is whether the seller can deliver the ownership interest required by the purchase contract.
Consider a property that has passed through several generations.
The owner listed on the tax record may have inherited the house from a parent. That parent may have inherited it from someone else. At some point, an estate may have been administered incorrectly or a deed may have failed to include someone whose interest mattered.
The problem can remain hidden until the property is sold.
A title examination can reveal that history.
This is particularly relevant in established Broward County neighborhoods, where some properties have changed ownership several times over many years.
What happens when the seller inherited the house?
Inherited property can create title questions that do not appear in an ordinary residential sale.
If the seller acquired the property through an estate, the circumstances surrounding that transfer may need to be examined. The buyer may need documentation showing how ownership passed from the deceased person to the current seller.
Probate can therefore become part of a real estate transaction.
This is one reason real estate law and probate law sometimes meet in the same file.
A buyer does not need to become an expert in probate procedure. The important question is whether the person selling the property has the legal authority to transfer the interest the buyer expects to receive.
If that authority is unclear, the transaction may need additional documentation or court action before closing.
A buyer should not assume that an inherited property has a clean title simply because the seller has lived there for years.
The deed deserves careful attention
The deed is the document that transfers the seller’s interest in the property.
Buyers sometimes give it little attention because the purchase agreement and mortgage receive most of the discussion. The deed deserves its own review.
The buyer should understand what interest is being conveyed and who will receive it.
That second question is particularly important.
A person buying a house alone may have a straightforward ownership arrangement. A married couple may have different estate planning concerns. Two unmarried people purchasing together may need to consider what happens if one owner dies or wants to sell.
Parents sometimes purchase property with adult children. Some buyers consider a trust or another ownership arrangement.
Each situation raises different legal questions.
The answer should be based on the buyer’s circumstances rather than a generic preference about how property should be titled.
How you take title can affect your estate
Buying a house creates an asset that may eventually become part of your estate.
The way that asset is owned can affect what happens after death.
Certain forms of ownership can affect whether an interest passes through probate. Other ownership arrangements may require the property to be addressed through the owner’s estate.
This is why the deed and the estate plan should be considered together.
A person might have a carefully prepared will but never review whether the way the person’s property is titled supports the intended estate plan.
That can create problems later.
The purchase of a home is therefore a useful point to review the larger ownership picture.
For a Coral Springs homeowner purchasing a primary residence, that conversation may also involve Florida homestead law.
Florida’s homestead laws deserve special attention when the property will be the buyer’s primary residence.
Florida provides significant legal protections for qualifying homestead property. The state also has specific rules concerning what happens to homestead property after the owner’s death.
Florida Statutes Section 732.401 addresses the descent of homestead property when an owner dies. Section 732.4015 places restrictions on the owner’s ability to devise homestead property when certain family members survive the owner.
These rules can affect surviving spouses and children.
For example, when a Florida homeowner dies while survived by a spouse and descendants, the disposition of the homestead may be governed by statutory rules rather than by whatever result the owner assumed a will would produce.
The details depend on the family and ownership circumstances.
That is why homeowners in Coral Springs and Broward County should not assume that a will alone determines what happens to their Florida homestead.
Can a will control who receives your house?
Sometimes. Florida law can limit what a homeowner may accomplish through a will when the property qualifies as homestead.
The owner’s family situation matters.
The ownership structure matters.
The type of property matters.
The timing of transfers can matter as well.
Florida Statutes Section 732.4015 contains specific restrictions concerning the devise of homestead when a spouse or minor child survives the owner. Section 732.401 also establishes rules concerning descent when a Florida resident dies without a valid disposition controlling the property.
This is one reason estate planning should be based on the actual assets a person owns.
A will should not be viewed in isolation from deeds, trusts, beneficiary arrangements, and Florida’s property laws.
Should you put your house in a trust?
A trust can be useful in some estate plans. It is not the right ownership arrangement for every homeowner.
The decision depends on what the owner wants the estate plan to accomplish.
A revocable living trust, for example, may be considered as part of an incapacity and estate administration plan. Other trusts can serve different purposes.
The important question is whether a particular trust arrangement fits the person’s property, family circumstances, and estate planning objectives.
Florida also has specific rules concerning transfers of homestead property into trusts and other lifetime transfers. Florida Statutes Section 732.4017 addresses certain transfers of homestead property and explains circumstances affecting the way the property is treated under the homestead rules.
That makes professional review useful before changing the title to a Florida home.
A homeowner should understand the consequences of the transfer before signing a new deed.
What if the inspection reveals serious damage?
A home inspection and a legal review serve different purposes.
An inspector examines the physical condition of the house. An attorney examines the legal rights and obligations created by the transaction.
Suppose an inspection reveals structural damage.
The buyer may want the seller to make repairs. A buyer may prefer a price reduction. The buyer may want a credit at closing. The buyer may decide that the property is no longer worth purchasing.
The purchase agreement determines which options are available.
An inspection report does not automatically give the buyer a right to cancel the transaction.
The contract may contain deadlines governing inspection objections. It may establish particular procedures for repairs or termination. Missing those deadlines can affect the buyer’s rights.
A lawyer can explain the relevant provisions before the buyer takes action.
What happens when a title search reveals a lien?
A lien does not always mean the buyer has to abandon the transaction.
The first step is understanding what the lien is and whose obligation created it.
A mortgage may need to be satisfied at closing. A judgment may require resolution. A construction lien may involve a contractor or subcontractor. An estate matter may require additional documentation.
The appropriate solution depends on the problem.
This is where title work becomes practical rather than abstract. The buyer needs to know whether the defect can be resolved before closing and whether the title company will insure the buyer’s intended ownership.
A buyer should also understand any exceptions listed in the title commitment.
Accepting an exception without understanding it can leave the buyer with a title issue that was visible before closing.
Is title insurance enough?
Title insurance provides protection against covered title risks under the terms of the policy.
It does not perform the same function as an attorney representing the buyer.
The Florida Bar explains that a title examination generally precedes issuance of a title insurance policy. A title commitment identifies requirements that must be satisfied before the policy can be issued and lists exceptions to coverage.
Those exceptions deserve attention.
A buyer should know what the policy covers and what it does not cover.
The buyer should also know who represents the buyer.
A closing attorney may be involved in the transaction without representing the buyer personally. The Florida Bar specifically advises consumers to determine who the closing attorney represents.
If you want independent legal advice, ask that question before closing.
When should a Broward County homebuyer consider legal representation?
Some circumstances call for particular caution.
Consider speaking with a Florida real estate attorney when:
The purchase contract contains provisions you do not understand.
The seller inherited the property.
The property has been involved in probate.
The title search identifies a lien or judgment.
A previous deed appears defective.
A divorce affected ownership.
You are buying with someone who is not your spouse.
You are considering buying the property through a trust or business entity.
The house will be a major part of your estate.
The inspection reveals serious defects.
The seller disputes a repair obligation.
The transaction involves seller financing.
The property has unusual easements or restrictions.
A dispute develops before closing.
You are unsure how the property should be titled.
These circumstances are not limited to any particular Broward County neighborhood. They can arise in a Coral Springs purchase just as they can in a transaction elsewhere in South Florida.
The common factor is uncertainty.
A buyer does not need to wait until a dispute reaches court before asking a lawyer to review the transaction.
What should you bring to the attorney?
The purchase contract is the obvious starting point.
If you have not signed it, bring the proposed agreement.
If you have already signed it, bring the complete version along with any amendments.
Other useful documents can include the title commitment, inspection report, seller disclosures, survey, mortgage documents, homeowners association documents, and written communications about repairs.
If the property was inherited, information about the estate can also be important.
If you are purchasing the property as part of an estate plan, bring the relevant estate planning documents.
The attorney also needs to know what you intend to do with the property.
Will it be your primary residence?
Will you own it alone?
Will someone else share ownership?
Do you expect to leave the property to your children?
Are you considering a trust?
Those answers can change the legal analysis.
What does this have to do with probate?
A house can become one of the largest assets handled by an estate.
When the owner dies, the legal treatment of that property depends on how it was owned and the circumstances surrounding the owner’s death.
Some properties pass through probate. Others may pass through a different legal mechanism. Homestead can create additional rules.
This is why the deed signed at the time of purchase can become relevant years later in an estate administration.
A buyer may be thinking about a mortgage and a move.
An estate planning attorney may also need to think about incapacity, death, family rights, and the eventual transfer of the property.
Both perspectives concern the same asset.
For families in Coral Springs and throughout Broward County, that connection can be particularly useful when a home is expected to remain in the family.
A house can create legal consequences long after closing
The closing date is only one point in the property’s legal history.
The deed remains part of the public record. The mortgage may remain for decades. The property may become subject to homestead protections. Ownership may change through marriage, divorce, death, or another transfer.
The house may eventually become part of a probate estate.
That is why a home purchase can be a useful time to review an estate plan.
If you live in Coral Springs or elsewhere in Broward County, the attorney reviewing your purchase should understand the Florida laws that govern the property and your ownership interest.
The goal is to understand the legal consequences before they become difficult to correct.
Questions to ask before signing a purchase contract
A buyer does not need a law degree to ask useful questions.
Start with these:
Who owns the property now?
The answer should be supported by the title records.
Can the seller deliver the title required by the contract?
A title examination can identify issues that need attention.
What happens if the inspection reveals a serious problem?
The answer should come from the purchase agreement and applicable law.
What happens if financing is delayed or denied?
The contract should establish the buyer’s rights in that situation.
Who will own the property after closing?
The deed should reflect the intended ownership arrangement.
What happens to the property if one owner dies?
That question can bring estate planning into the discussion.
Does the property qualify as homestead?
If it will be the buyer’s primary residence, Florida’s homestead laws deserve attention.
Does my estate plan account for this property?
If the house will be a significant asset, the answer should be clear.
The right legal question is often a little earlier
Homebuyers usually have plenty of practical questions.
How much will the mortgage cost?
When can we move in?
Did the inspection find anything serious?
Are the repairs finished?
Those questions matter.
There is another question worth asking before signing:
Do I understand the legal rights I am acquiring and the obligations I am accepting?
If the answer is uncertain, a Florida real estate attorney can review the transaction before the buyer becomes committed to terms that may be difficult to change.
For buyers in Coral Springs and throughout Broward County, that conversation can also include estate planning and probate considerations when the property is expected to remain a significant family asset.
A home purchase creates ownership.
The way that ownership is established can matter for years afterward.
Frequently Asked Questions
Do I need a real estate attorney to buy a house in Florida?
Florida does not require every residential buyer to hire a lawyer. The Florida Bar recommends that prospective buyers consult an experienced Florida licensed real estate attorney before signing a purchase contract. Legal advice can be particularly useful when the transaction involves title questions, unusual contract terms, probate, ownership concerns, or estate planning.
What does a real estate attorney check when buying a house?
A real estate attorney can review the purchase contract, examine title records, review the deed and closing documents, identify liens or other title problems, advise on ownership, and address disputes that arise before closing.
Should I hire an attorney before signing a purchase contract?
If you want legal advice about the agreement, reviewing it before signing gives the attorney an opportunity to identify provisions that could affect your rights. The Florida Bar specifically recommends consulting a Florida real estate lawyer before signing a purchase contract.
Can buying a house affect my estate plan?
Yes. The way a home is owned can affect what happens to the property during incapacity and after death. Florida also has special rules concerning homestead property.
Does a will determine who receives my Florida home?
A will may control some aspects of an estate, but Florida homestead law can restrict how a homestead property may be devised when a surviving spouse or minor child is involved. The ownership structure and family circumstances need to be considered.
Can a house become part of probate?
Yes. Real estate can become part of a probate estate when its owner dies, depending on the ownership structure and circumstances. Property that belonged to a deceased owner may therefore require probate administration before it can be transferred or sold.
Is a title search the same as a home inspection?
No. A home inspection examines the physical condition of the property. A title examination investigates ownership and recorded interests affecting the property.
Does title insurance replace a real estate attorney?
No. Title insurance protects against covered risks under the policy. An attorney can provide legal advice about the contract, title, ownership, closing documents, and other legal issues affecting the buyer.
Should I discuss estate planning when buying a house?
It can be useful when the property will be a significant asset or when the buyer has specific plans for its future ownership. The purchase may be a good opportunity to review the relationship between the new property, the deed, and the existing estate plan.
Can I put my Florida home into a trust?
A Florida homeowner may be able to transfer a home into a trust, but the consequences depend on the type of trust, the property, the owner’s circumstances, and Florida homestead law. Legal advice should be obtained before changing the title.
Talk with an attorney before signing
A home purchase can involve questions about contracts, title, ownership, homestead, probate, and estate planning.
A revocable living trust in Florida is an estate planning arrangement that allows a person to manage property during their lifetime and establish how that property will be managed or distributed after death. Because the trust is revocable, the person who creates it generally retains the ability to change or revoke it while they have the required capacity.
For many Florida families, the appeal of a revocable living trust is not simply avoiding probate. A properly structured and funded trust can also provide a framework for managing assets during incapacity, establish clear instructions for what happens after death, and give a successor trustee authority to step in when the original trustee can no longer serve.
But a trust only works as intended when the legal document, the ownership of the property, and the rest of the estate plan are coordinated.
What Is a Revocable Living Trust?
A revocable living trust is a legal arrangement created during a person’s lifetime.
The person who creates the trust is commonly called the settlor or grantor. The person responsible for managing property held by the trust is the trustee. The people or organizations who are intended to receive trust property are the beneficiaries.
One of the most common arrangements is for the person creating the trust to serve as the initial trustee. That allows the person to continue managing their property much as they did before creating the trust.
The trust document establishes the rules for managing the property and identifies what should happen if the creator becomes incapacitated or dies.
Florida’s Trust Code generally permits a settlor to revoke or amend a trust unless the trust terms make it irrevocable.
What does “revocable” mean?
It means the trust can generally be changed or terminated during the settlor’s lifetime, subject to the terms of the trust and applicable Florida law.
That flexibility is one of the defining characteristics of a revocable living trust. Creating one does not ordinarily mean giving up control of your property immediately.
Who Is Involved in a Revocable Trust?
A typical revocable living trust involves several roles.
Settlor or grantor
The settlor is the person who creates the trust and transfers property into it.
An individual can create a trust for their own benefit, while a married couple may use a joint or coordinated estate planning structure depending on their circumstances.
Trustee
The trustee manages property held by the trust according to its terms.
In a common revocable trust arrangement, the settlor also serves as trustee during their lifetime. This allows the person to continue managing trust property while they are able to do so.
Successor trustee
The successor trustee is the person or institution designated to take over management when the original trustee can no longer serve.
Choosing this person is an important part of the planning process. The successor may eventually be responsible for managing trust property during incapacity and administering the trust after death.
Beneficiaries
Beneficiaries are the people or organizations who are intended to benefit from the trust.
The trust can establish who receives property, when they receive it, and under what conditions or instructions the trustee must administer it.
What Happens While You Are Alive?
A revocable living trust is not simply a document that sits in a drawer until someone dies.
If you are the settlor and trustee, you can generally continue using and managing trust property according to the terms of the trust. You can also generally amend the trust as circumstances change.
That can make the trust useful as part of lifetime estate planning, rather than simply as a death-transfer document.
For example, your estate plan may need to change because of:
Marriage or divorce
The birth or adoption of a child
A beneficiary’s changing circumstances
A change in property ownership
The purchase or sale of real estate
A change in the person you want to serve as successor trustee
Changes in your financial circumstances
The trust should therefore be reviewed when major life or financial changes occur.
Alan J. Reinfeld:“A revocable trust is not simply a document you sign and put away. It is a way of organizing your property so that someone you trust can manage it if you become unable to do so and carry out your instructions after your death.”
What Happens If You Become Incapacitated?
One of the important differences between a revocable trust and a basic will is what the trust can do during your lifetime.
If you become unable to manage your financial affairs, a properly structured trust can allow your successor trustee to step in and manage property held by the trust.
The Florida Bar identifies this as one of the potential advantages of a revocable trust. Depending on the circumstances, the successor trustee may be able to continue managing trust assets, paying bills, and making financial decisions without requiring a court-appointed guardian of the person’s property.
This does not mean a trust eliminates every possible incapacity issue. The trust needs to be properly drafted, and the relevant assets need to be held or otherwise coordinated with the trust.
What Does “Funding” a Trust Mean?
Funding a trust means transferring appropriate property into the trust or otherwise coordinating ownership so that the trust can actually operate as intended.
This is one of the most important and frequently misunderstood parts of trust planning.
Signing a trust agreement does not automatically place every asset you own into the trust.
For example, if a person creates a revocable trust but leaves an important asset titled solely in their individual name, that asset may not receive the same probate-avoidance treatment as property properly held by the trust.
The Florida Bar specifically warns that assets such as real estate, bank accounts, and investments generally need to be formally transferred to the trust to obtain the maximum benefit from the arrangement.
That is why creating the document is only one part of establishing a functioning trust plan.
Alan J. Reinfeld: “One of the most important parts of creating a trust happens after the document is signed. If an asset is supposed to be managed through the trust, the ownership needs to be properly coordinated with the trust. An unfunded trust may not accomplish what the person who created it expected.”
What assets can be placed in a trust?
The answer depends on the type of asset, its ownership structure, applicable law, beneficiary designations, and the objectives of the estate plan.
Real estate, financial accounts, investments, and other property may potentially be coordinated with a trust, but they should not all be treated identically.
For a more detailed discussion of this issue, see What Assets Can a Trust Hold in Florida?
That distinction matters because what a trust is and what should be placed into a trust are related but separate estate planning questions.
Does a Revocable Trust Avoid Probate in Florida?
A properly funded revocable trust can allow property held by the trust to pass to beneficiaries without going through the ordinary probate process.
The reason is straightforward: the trustee already has authority to manage the trust property. The property does not have to be transferred from the deceased person’s individual ownership through a probate proceeding in the same way individually owned assets generally do.
However, saying that a revocable trust “avoids probate” without qualification is misleading.
The trust does not automatically control everything you own.
Assets that were never properly transferred to the trust may still require another method of administration after death. A pour-over will is commonly used as part of a revocable trust estate plan to address property that remains outside the trust.
Other assets may pass outside probate for entirely different reasons, including certain joint ownership arrangements or valid beneficiary designations.
So the real question is not simply:
“Did I sign a trust?”
It is:
“Is the property I want handled through the trust actually coordinated with the trust?”
What Happens to a Revocable Trust After Death?
When the settlor dies, the revocable trust generally becomes an important part of the estate administration process.
The successor trustee may need to:
Identify and secure trust property.
Review the trust’s instructions.
Determine what expenses and obligations must be addressed.
Deal with claims and required administration.
Manage or sell property when authorized or necessary.
Distribute property to the beneficiaries according to the trust terms.
Avoiding ordinary probate does not mean that nothing has to be done after death.
Trust administration can still involve legal, financial, and tax issues. Florida law also contains specific procedures involving a Notice of Trust in certain circumstances following a settlor’s death.
The successor trustee therefore has real responsibilities. The person chosen for that role should be capable of following the trust instructions and handling the administrative work that follows.
Devin P. Tison:“The best estate plan is one that makes the owner’s intentions clear before the family is forced to interpret them under pressure. A trust can provide that structure, but the document and the ownership of the assets need to work together.”
Revocable Trust vs. Will: What Is the Difference?
A will and a revocable living trust can serve different functions and are often used together.
A will generally takes effect at death and can identify beneficiaries, nominate a personal representative, and address property that passes through probate.
A revocable trust can operate during the settlor’s lifetime and can provide a framework for managing trust property during incapacity and after death.
A person who uses a revocable trust will commonly also have a will as part of the broader estate plan.
The important point is that a trust is not necessarily a replacement for every other estate planning document.
Does a Revocable Living Trust Protect Assets From Creditors?
Not generally for the person who created the trust.
This is an important correction to a common misconception about living trusts.
Under Florida Statutes §736.0505, property held in a revocable trust remains subject to the claims of the settlor’s creditors during the settlor’s lifetime to the extent that the property would have been reachable if the settlor owned it directly.
A revocable living trust should therefore not be presented as an automatic asset-protection device.
Different rules can apply to irrevocable trusts and to protections available to beneficiaries, which is a separate and more specialized area of trust planning.
Does a Revocable Trust Automatically Save Estate Taxes?
No.
A standard revocable living trust should not be described as an automatic estate-tax reduction strategy.
There can be circumstances in which trust planning is incorporated into a broader estate-tax strategy, including specialized provisions and irrevocable trusts. But those issues depend on the size and structure of the estate, the people involved, the applicable tax rules, and the objectives of the plan.
For 2026, the federal basic estate tax exclusion is $15 million per decedent.
That makes the tax discussion very different from older explanations that use figures such as $5.34 million or $10.68 million.
For a detailed discussion, see Can a Revocable Living Trust Reduce Estate Taxes in Florida?
The key distinction is simple: a revocable trust can be an important estate planning tool without being, by itself, an estate-tax savings strategy.
Revocable vs. Irrevocable Trusts
The difference between revocable and irrevocable trusts is fundamental.
A revocable trust generally allows the settlor to retain substantial control and the ability to amend or revoke the trust.
An irrevocable trust generally involves a greater restriction on the settlor’s ability to change or reclaim the trust property.
Irrevocable trusts can serve specialized estate planning, tax planning, and asset-protection purposes, but they involve different legal consequences and should not simply be treated as a more powerful version of a revocable trust.
For that reason, choosing between them requires looking at the purpose of the plan rather than starting with the assumption that one type is always better.
Who Should Consider a Revocable Living Trust in Florida?
A revocable living trust may be worth considering for people who want a structured plan for managing property during life and transferring it after death.
It can be particularly relevant when someone:
Owns Florida real estate or other significant property
Wants a successor trustee prepared to manage trust property during incapacity
Wants to organize the administration of an estate before death
Wants certain properly funded assets to pass outside ordinary probate
Has a family situation requiring more detailed instructions than a simple will may provide
Wants a coordinated estate plan that can be reviewed as circumstances change
But a trust is not automatically necessary for every Florida resident.
The right estate plan depends on the person’s property, family circumstances, goals, existing ownership arrangements, and the complexity of the intended plan.
Common Revocable Trust Mistakes
Some of the biggest problems with revocable trusts occur after the document has been signed.
Creating the trust but failing to fund it
A trust that does not actually hold the relevant property may not accomplish the probate-avoidance objectives the creator expected.
Treating every asset the same way
Different forms of property may require different ownership or beneficiary arrangements. Retitling everything without considering those differences can create unintended consequences.
Choosing a successor trustee casually
The successor trustee may eventually be responsible for substantial financial and administrative decisions. This should not be an afterthought.
Never reviewing the plan
A trust created years ago may no longer reflect current property, beneficiaries, family relationships, or financial circumstances.
Assuming the trust solves every estate planning issue
A revocable trust does not automatically provide creditor protection, eliminate taxes, or replace every other estate planning document.
Devin P. Tison: “Creating a trust does not automatically solve every estate planning problem. The important question is whether the trust was properly structured, whether the relevant assets were actually placed into it, and whether the plan addresses what happens when circumstances change.”
Frequently Asked Questions About Revocable Living Trusts in Florida
Is a revocable living trust the same as a living trust?
Generally, the terms are used to describe a trust created during the settlor’s lifetime. A revocable living trust is specifically a living trust that the settlor can generally amend or revoke under its terms and applicable law.
Does a revocable trust avoid probate in Florida?
Properly funded trust assets can generally pass to beneficiaries without going through ordinary probate. However, creating a trust does not automatically place every asset into it, and assets outside the trust may require another method of administration.
Can I still use my property after putting it in a revocable trust?
In a typical arrangement where the settlor remains trustee and beneficiary, the settlor can generally continue to manage and use trust property during life according to the trust terms.
What happens to my trust if I become incapacitated?
A properly drafted trust can allow a successor trustee to step in and manage trust property if the original trustee can no longer do so. This can help avoid the need for a court-appointed guardian of property in appropriate circumstances.
Does a revocable trust protect my assets from lawsuits?
A revocable trust generally does not protect the settlor’s assets from the settlor’s own creditors during life. Florida law specifically addresses creditors’ ability to reach revocable-trust property.
Does a revocable trust reduce estate taxes?
Not automatically. Tax planning may involve trusts and other strategies, but a standard revocable living trust should not be presented as an automatic estate-tax reduction tool.
Do I still need a will if I have a revocable trust?
Often, yes. A will can address property that was not transferred to the trust and can serve other estate planning purposes. The exact documents needed depend on the overall estate plan.
Planning a Revocable Living Trust in South Florida
For families in Coral Springs, Fort Lauderdale, Broward County, and throughout South Florida, creating a revocable living trust should be approached as an estate planning process rather than simply the preparation of a document.
The trust agreement is one part of the plan. Ownership of property, beneficiary designations, successor trustee arrangements, wills, and the person’s broader estate planning objectives also need to work together.
If you are considering a revocable living trust, the important questions are not simply whether a trust is popular or whether someone else has one. The important questions are what you want the trust to accomplish, what property should be coordinated with it, and what should happen if you become incapacitated or die.
Related Trust Planning Resources
What Assets Can a Trust Hold in Florida?
Can a Revocable Living Trust Reduce Estate Taxes in Florida?
Revocable vs. Irrevocable Trusts in Florida
What Happens If a Trust Is Not Properly Funded?
What Happens to a Trust After Someone Dies in Florida?
Florida Lady Bird Deed vs. Revocable Living Trust for Real Estate
Estate planning involves several legal terms that can be confusing if you are encountering them for the first time. Will, trust, and probate are among the most important.
Although these concepts are related, they serve different purposes. Understanding the basic differences can help you determine what questions to discuss with an estate planning attorney in Coral Springs and throughout South Florida.
What Is a Will?
A will is a legal document that provides instructions for what should happen to certain property after a person dies. In Florida, a valid will must meet specific legal requirements concerning its execution and witnessing.
A will can identify the beneficiaries who should receive probate assets and can name the person who should serve as the estate’s personal representative, which is Florida’s term for what many people call an executor.
A will can also be used to nominate a guardian for minor children.
Importantly, a will does not necessarily control every asset a person owns. Certain assets may pass outside probate through beneficiary designations, joint ownership, or other arrangements.
A will also does not take effect during the person’s lifetime. It becomes operative at death.
What Is a Trust?
A trust is a legal arrangement in which property is held and managed by a trustee for the benefit of one or more beneficiaries.
Unlike a will, a trust can operate during a person’s lifetime. For example, a revocable living trust can allow someone to continue managing property during life while establishing instructions for what should happen if that person becomes incapacitated or dies.
A trust can therefore serve purposes that go beyond distributing property after death. Depending on how it is structured and funded, it may provide a framework for managing assets during incapacity, distributing property to beneficiaries over time, and avoiding probate for assets properly transferred to the trust.
A useful way to think about a trust is as an ongoing legal arrangement for managing property. The person who creates the trust establishes its terms, a trustee manages the trust property, and beneficiaries receive the benefits according to those terms.
What Is Probate?
Probate is the court-supervised legal process used to administer a deceased person’s probate estate.
In Florida, probate generally involves identifying and gathering the decedent’s probate assets, addressing valid debts and expenses, and distributing the remaining assets to the appropriate beneficiaries.
Probate does not necessarily involve every asset a person owned. Some property may pass outside probate through a trust, beneficiary designation, joint ownership, or another legal mechanism.
Florida has different probate procedures depending on the circumstances of the estate, including formal administration and summary administration.
Will vs. Trust: What Is the Difference?
A will and a trust can both be part of an estate plan, but they work differently.
The most basic distinction is that a will generally operates after death, while a properly created and funded trust can operate during a person’s lifetime as well as after death.
Other differences may also matter when deciding how an estate plan should be structured.
Probate
Assets that are distributed through a will generally pass through probate. Assets properly held in a trust may generally be distributed by the trustee without going through the probate process for those assets.
This distinction is one reason some people use trusts as part of a broader plan to simplify the transfer of assets after death.
Privacy
Probate is a court process, while the administration of a private trust generally does not operate in exactly the same public court process.
For people who place a high value on privacy, this can be an important consideration when discussing a trust with an estate planning attorney.
Incapacity Planning
A will does not provide a mechanism for managing a person’s property while that person is alive but unable to manage it because of incapacity.
A properly structured trust can provide instructions for who will manage trust property if the person who created the trust becomes unable to do so.
Other estate planning documents, including powers of attorney and advance directives, may also be important for incapacity planning.
A trust can provide instructions for how and when trust assets should be distributed to children, grandchildren, or other beneficiaries. For example, the trust may establish that assets should be managed for a beneficiary rather than distributed to that person all at once.
Cost and Administration
A trust can involve greater upfront planning and administration than a basic will. Particularly because assets generally need to be properly transferred to and managed through the trust.
That does not mean a trust is always more expensive overall. The appropriate comparison depends on the person’s circumstances. For example the type of trust involved, the assets being managed, and the complexity of the estate plan.
Management of Assets
A will provides instructions for property at death, while a trust involves the ongoing management of property placed into the trust.
This distinction is important. Simply creating a trust does not automatically place every asset a person owns into that trust. Proper funding and coordination with the rest of the estate plan are essential.
How Do Wills, Trusts, and Probate Work in Florida?
Florida law governs the creation and administration of estates for people whose estates are subject to Florida jurisdiction. Florida also uses the term personal representative for the person appointed to administer a probate estate.
The Florida probate process can take different forms depending on the circumstances of the estate. For example, formal administration may be used for more complex estates, while summary administration may be available when the estate meets certain requirements.
Florida residents may also use trusts and other estate planning tools to determine how property will be managed and transferred. Whether a particular strategy is appropriate depends on the person’s assets, family circumstances, and estate planning goals.
For someone in Coral Springs, Fort Lauderdale, or elsewhere in Broward County, an estate plan should therefore be evaluated under the laws and procedures that apply in Florida rather than relying solely on general estate planning information from another state.
Can You Have Both a Will and a Trust?
Yes.
A trust and a will are not necessarily competing alternatives. Many estate plans use both.
For example, a person may establish a revocable living trust to hold and manage certain assets while also maintaining a will that addresses matters the trust does not cover, including the nomination of a guardian for minor children.
The way these documents work together depends on the individual’s circumstances and the structure of the estate plan.
Which Is Better: A Will or a Trust?
There is no single answer that applies to every family.
For some people, a will may address their primary estate planning needs. Others may benefit from a trust because they want a plan for managing assets during incapacity, controlling how beneficiaries receive property, or keeping certain assets outside the probate process.
The answer can depend on factors such as:
The type and value of your assets
Whether you own real estate
Whether you have minor children
Your family circumstances
Whether you want a plan for possible incapacity
How you want beneficiaries to receive their inheritance
Whether avoiding probate is an important goal
The complexity of your estate
An estate planning attorney can review these factors and explain which documents may be appropriate for your circumstances.
Frequently Asked Questions About Wills, Trusts, and Probate in Florida
Does a Will Avoid Probate in Florida?
Generally, no. Assets that pass under a will are typically subject to the Florida probate process unless another legal arrangement causes those assets to pass outside probate.
Does a Trust Avoid Probate in Florida?
A properly created and funded trust can generally allow assets held by the trust to pass to beneficiaries without going through probate. However, creating a trust alone does not automatically place all of a person’s assets into the trust.
Do I Need Both a Will and a Trust in Florida?
Not necessarily. Some people may have estate planning needs that can be addressed primarily through a will, while others may benefit from a trust and additional estate planning documents. The appropriate combination depends on the person’s circumstances and goals.
Estate Planning in Coral Springs and South Florida
Wills, trusts, and probate are closely related, but they solve different legal problems. Understanding the terminology is a useful first step, but creating an effective estate plan requires looking at how the different documents and assets work together.