Understanding The Estate Planning Process

Estate planning in Florida can cost a few hundred dollars for a basic will or several thousand for a plan built around a living trust. The price depends on your family circumstances and the legal work involved. Someone who wants to leave a home to their children may need a different plan from a parent in a blended family who wants to provide for a spouse while protecting their children’s inheritance.

Here is what you can generally expect to pay:

  • Basic will: $350 to $1,350.
  • Will based estate plan: $500 to $1,800.
  • Revocable living trust based plan: $1,700 to $4,500.
  • More complex estate planning: $3,350 to $8,950 or more.

These are indicative budgeting estimates, not a verified average of attorney fees in Coral Springs or Broward County. Your actual cost will depend on the services included in your attorney’s quote.

Below, we explain what affects these fees, which additional expenses may arise, and when a more comprehensive estate plan may be worth considering.


How much does an estate plan cost in Florida?

Published Florida estate planning fee guides provide a useful starting point for budgeting. The following ranges are preliminary benchmarks rather than a representative survey of attorneys in Coral Springs or Broward County.

Type of servicePreliminary price range
Basic will based estate plan$500 to $1,500
Trust based estate plan$2,000 to $5,000
Specialized or complex estate planning$5,000 to $15,000 or more

The scope of the package matters as much as the advertised price. One quote may cover only a will, while another includes documents addressing financial decisions during incapacity. A trust package may include a pour over will but exclude the deed needed to transfer a house into the trust.

These ranges should not be mistaken for a measured local average. Florida has no single statewide price list for private estate planning services, and published fee schedules do not always describe equivalent packages.

When comparing attorneys, request a written breakdown of the services included. Ask whether document revisions are covered and whether additional work will be billed separately. That gives you a more useful comparison than an advertised starting price.


What are you paying for when you hire an estate planning attorney?

An estate plan is meant to work under specific circumstances. The attorney must understand your wishes and identify the legal rules that may affect them.

A will directs the distribution of property that passes through your probate estate. A durable power of attorney addresses authority over financial matters during your lifetime. A health care surrogate designation allows you to appoint someone to make health care decisions under the conditions set out in the document.

A revocable living trust serves a different purpose. It can hold assets during your lifetime and establish how those assets will be managed or distributed later. The trust only controls property that has been properly transferred into it or otherwise made subject to its terms.


Florida law sets formal requirements for these documents. Under Florida Statutes § 732.502, a will must be signed and witnessed according to specific rules. Under Florida Statutes § 709.2105, a power of attorney must be signed by the principal, witnessed by two people, and acknowledged before a notary or through another legally permitted procedure. A designation of health care surrogate has its own requirements under Florida Statutes § 765.202.

These requirements are one reason a document’s length tells you very little about the work involved. A short will can raise difficult questions about ownership or inheritance. A longer document may be straightforward if the family’s circumstances are uncomplicated.

The Florida Bar puts it bluntly in its consumer guide, Do You Have a Will?: “There is no such thing as a ‘simple will.’” Its point is that even a modest estate can involve legal questions that are not obvious from a blank form.


How much does a will cost compared with a living trust?

A basic will based plan generally costs less to prepare than a trust based plan. A trust requires an agreement governing the trust property, and the attorney may need to coordinate ownership records with the document.


The following comparison shows why the two prices are not interchangeable.

ConsiderationWill based planTrust based plan
Initial draftingGenerally lower costGenerally higher cost
ProbateProbate may be required for assets in the estateProperly transferred trust assets can avoid probate
Property transfersMay not require a trust deedMay require deeds or ownership changes
Administration after deathPersonal representative handles the probate estateSuccessor trustee administers trust assets
Best fitMay suit people with straightforward wishesMay suit people whose property or family circumstances justify a trust

A will does not avoid probate simply because it clearly states who should inherit. Probate is the court supervised process used to administer assets that do not pass automatically to a successor.

A trust can avoid probate for assets transferred into it, but the trust itself still requires administration. The Florida Bar explains both the benefits and the limitations in its consumer guide, The Revocable Trust in Florida.

The decision should follow the person’s needs. Someone with a modest estate may be well served by a will based plan. A homeowner with property in multiple states may have stronger reasons to consider a trust.


The cost people forget: funding the trust

Preparing a trust agreement does not automatically transfer your assets into it. That work is known as funding the trust, and it can involve changing account ownership or preparing a deed for real estate.

The Florida Bar specifically warns that assets must be formally transferred to a revocable trust to receive the intended probate avoidance benefits. Its trust guide explains that property left outside the trust may still require probate. The family can then face both probate administration and trust administration.

This is a common source of unexpected expense. A person may pay for a trust believing the house will pass through it, only to discover that the deed was never changed.


A Florida court case shows what can go wrong

In Vaughan v. Boerckel, decided in 2007, Florida’s Fourth District Court of Appeal addressed real property that had not been transferred into a trust by the appropriate deeds. The court affirmed the judgment because the property did not become part of the trust through the will’s pour over provision.

The case involved a family dispute over the intended distribution of property. The failure to complete the transfers meant that the trust did not control the real estate as the family had expected.

This is a documented example of why implementation matters. It is not evidence that every unfunded trust will lead to litigation, nor does it establish a typical financial loss. It does show that paying for a trust document cannot replace the legal steps required to fund it.

Before accepting a trust quote, ask whether the attorney will prepare the necessary deed for your Coral Springs home. Confirm whether recording charges are included. If you own real estate outside Florida, ask whether that property needs separate planning under another state’s law.


What hidden costs can appear after you sign?

The initial fee is easier to understand when the attorney identifies the work that may follow.

Deed preparation and recording. A trust that should own your home may require a new deed. Recording charges are separate from the legal drafting fee unless the engagement says otherwise.

Document revisions. A change in your wishes may require an amendment or a new document. Ask how the attorney charges for updates.

Tax and financial advice. Some estates need advice from an accountant or financial adviser. These professionals charge separately from the estate planning attorney.

Trust administration. After the trust maker dies, the successor trustee may need help identifying assets and resolving claims before distributing property.

Probate for assets left outside the plan. A trust may not prevent probate if an asset remains in the owner’s individual name and no other transfer method applies.

Disputes among family members. Ambiguous instructions or competing claims can lead to litigation. The cost varies widely, so a reliable article should not attach an invented average to this risk.

These expenses will not apply to every plan. A good quote should make clear which charges are included and which remain the client’s responsibility.


What does probate cost in Broward County?

Probate expenses depend on the procedure and the property involved. The Broward County Clerk of Courts fee schedule currently lists these charges:

Filing or procedureCourt filing fee
Formal administration$401
Opening an estate without letters of administration or an order of summary administration$232
Summary administration for an estate valued below $1,000$236
Summary administration for an estate valued at $1,000 or more$346

These are court filing fees, not the total cost of probate. Attorney fees and other expenses may be additional.

Florida also has statutory schedules for compensation paid to the attorney and the personal representative handling an estate. These are especially useful for understanding potential costs, but they must be described accurately: the statutory amounts are presumed reasonable under the applicable rules, not mandatory charges that every estate must pay.


A worked example: a $500,000 probate estate

Under Florida Statutes § 733.6171, the presumed reasonable fee for ordinary attorney services in formal administration is calculated using the compensable value of the probate estate.

For an estate with a compensable value of $500,000, the calculation is:

CalculationAmount
First $100,000 under the statutory schedule$3,000
Remaining $400,000 at 3%$12,000
Illustrative attorney fee$15,000

The $3,000 base consists of the statutory amounts for the first $40,000 and the next two $30,000 portions. The remaining $400,000 falls within the 3% rate applicable to the portion above $100,000 and up to $1 million.

The personal representative’s compensation is calculated separately under Florida Statutes § 733.617. Under that schedule, the presumed reasonable compensation for ordinary services on a $500,000 compensable estate is also $15,000.

The combined illustration is therefore $30,000 before filing fees and other expenses. This is not a prediction of what a particular family will pay. The parties can agree to a different fee arrangement under the applicable rules, and the actual compensable estate value may be lower than the deceased person’s total net worth.

That last point matters. Property that passes outside probate may not be included in the compensable probate value. A life insurance policy with a valid beneficiary designation, for example, may pass directly to the beneficiary rather than through the probate estate.

The calculation illustrates why families sometimes compare the upfront cost of estate planning with the potential cost of future administration. It does not prove that a trust is always cheaper. Trust administration also requires work, and professional services may still be needed.


Does avoiding probate always save money?

No. Avoiding probate can reduce certain expenses and delays, but it does not eliminate the work involved in settling an estate.

The Florida Bar’s revocable trust guide explains that a successor trustee may need to identify and value assets, address creditors, pay expenses, and distribute the remaining property. The trustee may be entitled to compensation, and the family may need legal or accounting assistance.

A trust may provide a clear advantage when someone owns real estate in multiple states. Without a trust or another suitable arrangement, the property could require probate proceedings in each state where it is located.

For a person with a modest estate and uncomplicated wishes, a will based plan may be more appropriate. The right comparison depends on the assets involved and the work each arrangement is likely to require.


The creditor protection misconception

A revocable living trust is not a universal way to shield assets from creditors. Under Florida Statutes § 736.0505, property in a revocable trust is generally available to the settlor’s creditors during the settlor’s lifetime to the extent that it would have been available if owned directly.

The Florida Bar Journal article Designing Trust Systems for Florida Residents discusses situations in which transferring property into a trust may affect protections that would otherwise apply to the asset.

That is a significant distinction. Probate avoidance and creditor protection are separate goals. Someone who needs advice about creditor exposure should explain that concern before deciding how assets should be titled.


Why Florida homestead rules can affect the price of a plan

Florida’s homestead rules can complicate how a home is distributed after death. Under Florida Statutes § 732.4015, homestead property generally cannot be devised when the owner is survived by a spouse or minor child, subject to the statutory exception allowing a devise to the spouse when there are no minor children.

This can matter to a homeowner who wants a surviving spouse to remain in the family home while preserving an eventual inheritance for children from an earlier relationship. The arrangement needs to be considered under Florida law rather than treated as a routine gift.

The consequences can be especially important in blended families. The owner may have one intention, the spouse may have different expectations, and the children may understand the plan differently. Clear legal advice cannot guarantee that no disagreement will arise, but it can identify restrictions before the documents are signed.

The attorney may need to examine the property title and the family’s circumstances before recommending a structure. That work can affect the fee, and it is worth asking about early in the consultation.


What happens if someone dies without a will?

When someone dies without a valid will, Florida’s intestacy laws determine who inherits probate property. The outcome may differ from what the person would have chosen.

The Florida Bar explains the basic rules in Do You Have a Will?. A surviving spouse does not automatically inherit everything in every family situation. The result can depend on whether the deceased person had descendants and whether those descendants are also descendants of the surviving spouse.

A will also allows a parent to nominate a guardian for minor children. That nomination is subject to the court’s role and applicable law, but leaving the decision unaddressed can create additional uncertainty for the family.

A person does not need substantial wealth for these questions to matter. A home, a modest savings account, or responsibility for a child may be enough to justify making basic arrangements.


What the statistics tell us about estate planning delays

National surveys suggest that many Americans postpone estate planning even when they have reasons to make arrangements.

Caring.com’s 2025 Wills and Estate Planning Study reported that only 24% of respondents had a will. The survey also found that 13% reported having a living trust and 4% reported other estate planning documents. These categories may overlap, so the percentages should not be added together as though they describe separate groups.

Among respondents without a will, 43% said they had not gotten around to making one. The survey was conducted with YouGov and included more than 2,500 American adults.


The 2024 Caring.com survey found that 40% of respondents without a will believed they did not have enough assets to leave anyone. That figure was up from 33% in 2022. The 2024 survey included more than 2,400 American adults.

These are national findings, not estimates of estate planning behavior in Florida. They do, however, illustrate two common reasons people delay: they put planning off, or they assume their property is too modest to justify the effort.

That assumption can overlook the practical purpose of estate planning. A person may need someone to manage financial affairs during incapacity. A parent may want to nominate a guardian. A homeowner may want to understand how title affects the eventual transfer of the property.

None of these situations automatically calls for an expensive trust. The point is to understand which decisions need to be made before circumstances make them urgent.


Four examples of how estate planning costs can unfold

The following examples are hypothetical. They illustrate possible outcomes rather than predicting what a particular family will spend.


The online will that does not prevent probate

A homeowner prepares a will using an inexpensive online form. Years later, the homeowner dies with the house still titled individually. The will identifies the intended beneficiaries, but the family still needs to administer the probate estate.

The original document may have been valid and useful. It simply did not avoid probate. The family’s total cost includes the earlier document fee and the later administration expenses.


The trust that was never funded

A couple pays an attorney to establish a revocable living trust. They sign the agreement but never complete the deed transfer for their home. After one spouse dies, the family discovers that the property was not transferred into the trust.

The decision to create a trust was not necessarily wrong. The implementation was unfinished, and the family may now need probate in addition to trust administration.

The Vaughan v. Boerckel decision demonstrates that this type of problem can have serious legal consequences. It does not establish a typical financial loss, but it gives readers a concrete reason to ask about funding before signing an engagement agreement.


The blended family and the homestead

A homeowner wants a spouse to remain in the family home after death while eventually leaving the property to children from a previous relationship. The homeowner assumes a standard will will accomplish the goal.

Florida’s homestead restrictions may affect whether that distribution is permitted. The plan needs to account for the family’s legal rights before the documents are executed.

The potential cost is not limited to a drafting fee. A dispute over the home can create substantial additional work, although the actual expense depends on the circumstances.


The missing incapacity documents

A person becomes unable to manage financial affairs after a medical event. The family discovers that the documents they have do not provide the authority needed for a particular decision.

Depending on the circumstances, the family may need legal assistance or a court proceeding to obtain authority. A durable power of attorney and appropriate health care documents can address certain issues in advance, provided they are valid and suitable for the situation.

This is why estate planning should consider incapacity as well as death. The appropriate documents depend on the person’s needs and Florida’s requirements.


What about Medicaid recovery and long term care?

Estate planning is sometimes confused with Medicaid planning. They overlap in some circumstances, but they are not interchangeable.

Florida’s Agency for Health Care Administration explains its recovery responsibilities through its Medicaid Third Party Liability program. Federal rules require states to pursue recovery for certain benefits paid to qualifying recipients aged 55 or older, subject to statutory protections and exceptions.

The details matter. Medicaid estate recovery does not mean every estate will face the same claim, and a revocable trust is not a guaranteed way to avoid recovery. Eligibility rules, the type of benefit received, the assets involved, and applicable exceptions all affect the analysis.

Someone concerned about future long term care costs should raise that issue during the initial consultation. The attorney may need to consider different planning objectives before recommending a trust or another arrangement.


How to compare estate planning attorney fees

A written quote should describe the services the attorney will perform. Before accepting an offer, ask the following questions.

Documents and preparation

  • Which documents are included in the fee?
  • Does the package include a consultation and review of my circumstances?
  • Are revisions before signing included?
  • If I establish a trust, does the package include a pour over will?

Implementation

  • Will the attorney prepare a deed if my home needs to be transferred into the trust?
  • Are recording charges separate?
  • Will the attorney explain which accounts or other assets should be transferred or retitled?

Future expenses

  • How are amendments charged?
  • What circumstances could trigger additional fees?
  • Is follow up assistance included after the documents are signed?

The answers matter more than the number of pages in the package. A clearly scoped flat fee can make budgeting easier, but it is only useful if you know what the attorney is agreeing to do.


When should you review an estate plan?

A change in circumstances can make an existing plan unsuitable. Marriage or divorce may affect your intended beneficiaries. A new child may change your wishes about guardianship or inheritance. Buying property can introduce new ownership questions.

Moving to Florida is another reason to have an existing plan reviewed. A document prepared in another state may remain valid, but Florida law can affect how certain provisions operate. The Florida Bar’s consumer guidance on wills explains why the formal requirements and intended effect of a will matter.

A review does not necessarily mean replacing every document. The attorney may conclude that the current plan remains appropriate or recommend a limited amendment.

Ask whether the original engagement includes any period of follow up. Some attorneys charge separately for later updates, so it is worth understanding that arrangement before signing.


Frequently asked questions about estate planning costs in Florida

How much does a will cost in Florida?

  • Published Florida fee guides provide preliminary benchmarks of roughly $500 to $1,500 for a basic will based estate plan. The actual price depends on what the package includes and whether the person’s circumstances require additional legal work.

How much does a living trust cost in Florida?

  • A trust based estate plan may cost around $2,000 to $5,000 under the preliminary benchmarks discussed here. More specialized planning can cost more. Deed preparation and other implementation expenses may be separate.

Is a trust always cheaper than probate?

  • No. A properly funded trust can avoid probate for the assets it owns, but trust administration may still involve professional fees. Whether a trust saves money overall depends on the assets and the work required to settle the estate.

Can a living trust protect assets from creditors?

  • A revocable living trust generally does not protect the settlor’s assets from the settlor’s own creditors during the settlor’s lifetime. Florida law provides different rules for other arrangements, so creditor protection requires specific legal advice.

Does Florida require an attorney to prepare a will?

  • Florida law does not generally require an attorney to prepare a will. The document must still meet the state’s execution requirements. Legal advice can be particularly important when the family or property situation raises questions that a form cannot resolve.

What happens if I die without a will in Florida?

  • Florida’s intestacy laws determine who inherits property that passes through the probate estate. The outcome depends on the family circumstances and may differ from the deceased person’s wishes.

Are estate planning attorney fees tax deductible?

  • Personal legal expenses for estate planning are generally not deductible as personal expenses on a federal income tax return. Business related circumstances may be different, so consult a qualified tax professional about your situation.

Do I need to update my estate plan after moving to Florida?

  • A review is sensible after a move because Florida law may affect the operation of existing documents. The attorney can determine whether the plan remains suitable or whether specific changes are needed.

Estate planning in Coral Springs and Broward County

For residents of Coral Springs and the wider Broward County area, the first step is to identify what the plan needs to accomplish. The right documents depend on the property involved and the people who may need to manage your affairs or inherit from you.

MyPersonalAttorneys can help you explore estate planning options under Florida law. Ask for a clear explanation of the proposed work and the fees involved before committing to a plan.

A useful plan should fit your circumstances and be implemented correctly. The initial quote is only one part of understanding its cost
How to Put an LLC in a Trust in Florida (Without Disrupting Business Operations)


An Assignment of Membership Interest document transferring Florida LLC ownership into a revocable living trust.

Quick Answer:

Putting a Florida LLC into a revocable living trust is done by executing a formal Assignment of Membership Interest. This transfers your legal ownership equity from you as an individual to you as the trustee. It does not disrupt daily operations, trigger new federal income taxes, or force you to change your tax classification. Instead, it bypasses Broward County probate court, secures immediate business continuity if you face medical incapacity, and keeps your company running without court interference.


Let us paint a familiar picture. You worked tirelessly to build your Florida limited liability company. You handled the state filings, set up bank accounts, landed clients, and dealt with supply chain headaches.

Then, during a quiet moment over coffee, a terrifying thought creeps into your head: What actually happens to my business if I get hit by a distracted driver on I 95 tomorrow afternoon?

If your LLC membership units remain in your personal name, your business stops abruptly. Bank accounts freeze, contracts stall, and payroll grinds to a sudden halt while your family waits for a Broward County probate judge to appoint a personal representative.

Putting your LLC in a trust solves this problem. Let us walk through how Florida business owners transfer their companies into a living trust smoothly, legally, and without unnecessary headaches.


Why Florida Business Owners Assign LLC Interests to a Revocable Trust

Many business owners falsely assume that a standard Last Will and Testament protects their company. A will is essentially a formal letter to a probate judge asking them to distribute your assets after you pass away. It does not avoid probate, and it provides zero protection if you become medically incapacitated.


1. Bypassing Broward County Probate Court

When you own an LLC in your individual name, your ownership interest is personal property that must pass through probate administration upon death. Probate is slow, public, and expensive. By transferring your membership units to a trust, your trust becomes the legal owner of the business. Upon your death, your designated successor trustee steps in instantly according to your written terms, completely bypassing the court system.


2. Seamless Management Continuity During Medical Incapacity

What happens if you face a sudden health crisis or medical emergency that leaves you unable to manage your business for six months?

A personal power of attorney can work, but financial institutions routinely scrutinize or outright reject old powers of attorney for business accounts. When your LLC is owned by a trust, your successor trustee can step in immediately to approve payroll, sign client contracts, and keep operational doors open without court oversight or administrative delays.


4 Steps to Transfer Your Florida LLC Membership Into a Trust

Moving a company into a living trust sounds complex, but the execution follows four defined steps under Florida law.

                 ┌────────────────────────────────────────┐
                 │ Step 1: Review Operating Agreement     │
                 └───────────────────┬────────────────────┘
                                     │
                 ┌───────────────────▼────────────────────┐
                 │ Step 2: Execute Assignment of Interest │
                 └───────────────────┬────────────────────┘
                                     │
                 ┌───────────────────▼────────────────────┐
                 │ Step 3: Formalize Member Resolutions   │
                 └───────────────────┬────────────────────┘
                                     │
                 ┌───────────────────▼────────────────────┐
                 │ Step 4: Verify Sunbiz & Bank Records   │
                 └────────────────────────────────────────┘

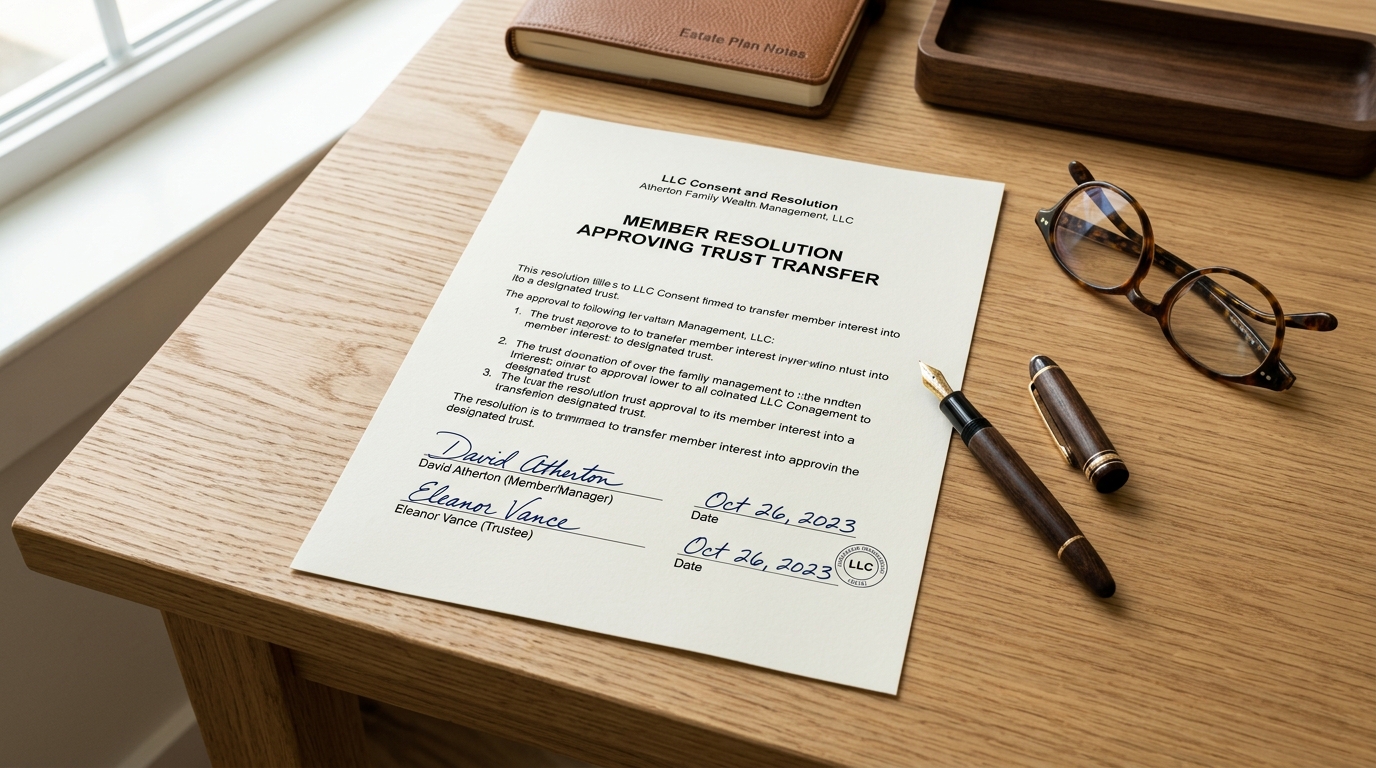
Member resolution and corporate consent document approving the transfer of LLC units to a living trust in Florida.

Step 1: Review Your Existing Florida LLC Operating Agreement

Before signing any transfer documents, open your company operating agreement. If you are the sole owner of a single member LLC, transferring ownership is straightforward.

If your business has multiple owners, your operating agreement likely contains transfer restrictions, rights of first refusal, or specific consent requirements. You must follow these internal rules so your transfer remains valid and compliant.


Step 2: Execute an Assignment of Membership Interest

This is the core legal transfer document. You do not deed your company over like real estate; instead, you execute an Assignment of LLC Membership Interest.

This document formally states that you, as an individual, assign your equity percentage and voting rights to yourself as the trustee of your living trust.


Step 3: Formalize Member Resolutions & Update Internal Schedules

Once the assignment is signed, document the transfer within your corporate records:

  • Draft a brief member resolution approving the assignment.
  • Update your LLC membership ledger to reflect your trust as the record owner.
  • Attach the assignment to Schedule A of your revocable trust agreement, listing your LLC equity as a funded trust asset.

Step 4: Verify Sunbiz Filings & Bank Account Signatory Rights

A common point of confusion for Florida business owners is whether Sunbiz (the Florida Division of Corporations) needs an immediate update.

Sunbiz tracks the managers or authorized persons who run the company, not necessarily every equity owner. If you remain the manager of your manager managed LLC, your Sunbiz listing stays the same.

However, you should bring your trust documents and signed assignment to your bank so your business accounts accurately recognize your trustee authority.


Common Pitfalls When Moving Florida Businesses Into a Trust

Will Putting My LLC in a Trust Change My Taxes?

For the vast majority of business owners, no. A standard revocable living trust is a disregarded grantor trust for federal tax purposes. Your single member LLC continues to report income on Schedule C of your personal Form 1040. You do not need a new Employer Identification Number (EIN) for your LLC simply because your trust now holds the membership units.


What Happens If My LLC Has Multiple Owners?

In multi member LLCs, co owners often panic when you mention putting your share into a trust. They worry your family members will show up on Monday morning trying to make operational decisions.

Clear up this confusion early. Transferring your economic rights to a trust protects your family financially while your operating agreement ensures that voting control or management decisions remain with qualified surviving partners or designated trustees.

The modern Broward County Judicial Complex in Fort Lauderdale Florida representing local probate jurisdiction.

Frequently Asked Questions About Florida LLCs and Living Trusts

How do I put an LLC in a trust in Florida?

  • You transfer ownership by executing an Assignment of Membership Interest from yourself as an individual to yourself as trustee, updating your internal corporate records, and listing the LLC units on your trust asset schedule.

Do I need to notify Sunbiz when I put my LLC in a trust?

  • Not necessarily. Sunbiz tracks managers and authorized officers, not underlying equity owners. If your managerial role remains unchanged, you generally do not need to update Sunbiz until your standard annual report filing.

Does transferring an LLC to a trust protect it from personal creditors?

  • A revocable living trust provides asset organization, probate avoidance, and operational continuity, but it does not shield personal assets from personal creditors during your lifetime. Irrevocable trust structures or specific charging order protection rules under Florida LLC law are required for advanced asset protection.

Can a trust hold an S Corp tax election LLC in Florida?

  • Yes. Federal tax law permits standard revocable grantor trusts to hold shares or membership units in S Corporations without invalidating your tax election.

Can I name my trust as the manager of my LLC?

  • While a trust can serve as the member (owner) of an LLC, individuals or corporate entities typically serve as managers to keep daily signing authority straightforward for contracts and banking.

Secure Your Business Continuity with a Coral Springs Estate Planning Attorney

Building a successful business takes years of dedication. Protecting it from administrative freezes, court delays, and probate confusion takes proper legal planning.

The estate planning and business attorneys at Reinfeld & Cabrera, P.A. help South Florida entrepreneurs structure their living trusts, assign business equity, and safeguard company continuity.

Schedule a Confidential Business Consultation

Protect your business and give your family total peace of mind. Speak directly with an attorney today to review your business assets and trust options:

  • Direct Telephone: (954) 866 4878 | Toll Free: (954) 866 HURT
  • Coral Springs Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Website: mypersonalattorneys.com
  • Local Coverage: Coral Springs, Fort Lauderdale, Parkland, Tamarac, Margate, and surrounding South Florida communities.

What Happens When a Beneficiary Dies Before the Estate Is Distributed?

Inheritance documents awaiting estate distribution after a beneficiary dies

The answer depends on when the beneficiary died, the language of the will, the beneficiary’s relationship to the person who died, and whether the beneficiary had already acquired a legal interest in the inheritance.

This situation can become complicated during Florida probate. A beneficiary may die while the estate is still being administered, leaving the personal representative and the surviving beneficiaries with an important question: Who is now entitled to receive that beneficiary’s share?

The answer is not always the beneficiary’s children, and the inheritance does not automatically return to the estate of the person who originally died.


What Happens When a Beneficiary Dies During Probate?

The first question is when the beneficiary died in relation to the person whose estate is being administered.

There is an important legal difference between a beneficiary who dies before the decedent and one who survives the decedent but dies before receiving an inheritance.

Those situations can produce different results under Florida law.

If the beneficiary survived the decedent, the beneficiary may have acquired an interest in the estate even though the probate case had not yet been completed. If that happens, the beneficiary’s own estate may become involved in receiving and administering that interest.

By contrast, if the beneficiary died before the decedent, Florida’s anti-lapse rules may determine whether the gift passes to certain descendants or otherwise fails under the terms of the will.


What If a Beneficiary Dies Before Receiving an Inheritance?

A common misconception is that an inheritance does not belong to a beneficiary until the personal representative actually writes the check or transfers the property.

That is not necessarily how probate works.

When a beneficiary survives the person who created the will, the legal treatment of that beneficiary’s interest can be different from the situation in which the beneficiary predeceases the decedent. The fact that distribution has not yet occurred does not by itself answer who ultimately receives the property.

The personal representative may therefore need to determine whether the deceased beneficiary’s interest must be distributed to the beneficiary’s estate.

This is one reason the question “what happens if a beneficiary dies before probate is complete?” cannot be answered with a single rule.


What If the Beneficiary Survived the Decedent?

This is one of the most important distinctions.

Suppose Maria leaves $100,000 to her son David in her will. Maria dies, and her probate estate is opened. David is alive when Maria dies, but he dies several months later while the probate case is still pending.

The fact that David died before receiving the $100,000 does not necessarily mean the gift disappears.

Depending on the circumstances and the terms of Maria’s will, David’s interest may become part of his own estate. His personal representative may then have to address that inheritance as part of David’s estate administration.

That can introduce a second probate or estate administration process.

The personal representative of Maria’s estate may therefore need to coordinate with the representative of David’s estate before the inheritance can be distributed.


What If the Beneficiary Died Before the Person Who Made the Will?

The situation can be different when a beneficiary dies before the testator.

For example, imagine that Maria’s will leaves her estate to her son David, but David dies before Maria. Maria later dies without changing her will.

Florida’s anti-lapse statute can sometimes preserve a gift to a deceased beneficiary’s descendants rather than allowing the gift to lapse. Florida Statutes section 732.603 applies to certain devisees who are relatives of the testator and who leave descendants who survive the testator. The statute also contains exceptions and conditions that can affect whether the rule applies.

This means that a beneficiary’s children do not automatically inherit every time a named beneficiary dies first.

The relationship between the deceased beneficiary and the testator matters. So does the language of the will.


How Does Florida’s Anti-Lapse Law Work?

Florida’s anti-lapse statute is designed to address certain situations in which a person named to receive property under a will dies before the testator.

Under section 732.603, a devise to certain relatives of the testator does not necessarily lapse merely because the named beneficiary dies before the testator. When the statutory requirements are satisfied, the deceased beneficiary’s descendants may take the property in the manner provided by the statute.

But anti-lapse rules should not be treated as a universal substitute-beneficiary provision.

The statute has specific requirements concerning the relationship between the testator and beneficiary, the beneficiary’s descendants, and survival. The will itself can also contain language that affects the outcome.

For that reason, determining whether Florida’s anti-lapse law applies requires examining the actual estate planning documents and the family relationships involved.


Does the Inheritance Go to the Beneficiary’s Children?

Not automatically.

Whether a deceased beneficiary’s children receive the inheritance depends on the circumstances.

If the beneficiary died before the testator, Florida’s anti-lapse statute may allow certain descendants to receive the gift.

If the beneficiary survived the testator and then died during probate, the analysis can be different. The beneficiary’s interest may instead become part of the beneficiary’s own estate, depending on the nature of the property interest and the governing documents.

The distinction is critical.

Simply knowing that “the beneficiary died” is not enough to determine what happens next.


Family members reviewing inheritance documents after a beneficiary’s death

What Happens to the Deceased Beneficiary’s Estate?

When a beneficiary survives the original decedent but dies before receiving the inheritance, the beneficiary’s own estate may become relevant.

The inheritance may need to be administered alongside the beneficiary’s other assets. The beneficiary’s will, if there is one, may affect who ultimately receives the property. If there is no valid will, the beneficiary’s estate may instead be distributed under the applicable intestacy rules.

This can create a situation in which one estate is effectively waiting for another estate to be administered.

For example, the personal representative of the first estate may need documentation establishing who has authority to act for the deceased beneficiary’s estate before completing distribution.


What If the Will Names a Backup Beneficiary?

Some wills specifically address what happens if a beneficiary dies.

A will might provide that if a named beneficiary does not survive the testator, the property goes to another person or group of people. Other wills may contain language creating a substitute gift or otherwise addressing descendants.

These provisions can change the analysis significantly.

This is why the will should be reviewed before relying on a general rule about a beneficiary who dies before receiving an inheritance.

A specific provision in the will may provide a different result from what would happen under the default statutory rules.


What Does the Personal Representative Need to Do?

The personal representative is responsible for administering the estate according to the will and Florida law.

When a beneficiary dies during administration, the personal representative may need to determine:

  • When the beneficiary died
  • Whether the beneficiary survived the decedent
  • Whether the will contains a substitute beneficiary provision
  • Whether Florida’s anti-lapse statute applies
  • Whether the beneficiary had already acquired an interest in the estate
  • Whether the beneficiary left a will
  • Who has authority to represent the beneficiary’s estate
  • Whether additional court filings are necessary
  • Whether the distribution should be delayed until the issue is resolved

The personal representative should not simply assume that the deceased beneficiary’s share goes to the beneficiary’s children or surviving relatives.

The correct result depends on the facts and governing documents.


Can a Beneficiary’s Death Delay Probate?

Yes.

A beneficiary’s death can complicate or delay an estate administration, particularly when the deceased beneficiary’s estate must become involved.

The personal representative may need additional documentation, court orders, or information about the beneficiary’s heirs or estate. If family members disagree about who should receive the deceased beneficiary’s share, the issue can become contested.

This is one reason a probate case can remain open even after the major assets and beneficiaries initially appear to have been identified.


What If Family Members Disagree About the Inheritance?

Disputes can arise when different family members interpret a will differently or disagree about whether an anti-lapse provision applies.

For example, one relative might argue that the deceased beneficiary’s children should receive the inheritance, while another argues that the property should pass under a different provision of the will.

The personal representative may need to seek legal guidance or court involvement rather than making the distribution based on an informal family agreement.

A disputed inheritance can also become more complicated when the deceased beneficiary had creditors, a separate probate estate, or competing heirs.


What Happens When a Beneficiary Dies Before the Estate Is Distributed in Florida?

There is no single answer for every Florida probate case.

If the beneficiary died before the decedent, Florida’s anti-lapse statute may apply in certain circumstances.

If the beneficiary survived the decedent but died before receiving the inheritance, the beneficiary’s interest may instead become part of the beneficiary’s own estate.

The will, the timing of the deaths, the relationship between the people involved, and the nature of the property all matter.

That is why a personal representative should determine the legal status of the beneficiary’s interest before distributing the estate.


Frequently Asked Questions

What happens if a beneficiary dies before probate is complete?

  • It depends on whether the beneficiary survived the person whose estate is being administered. If the beneficiary survived the decedent and later died during probate, the beneficiary’s interest may need to be handled through the beneficiary’s own estate. If the beneficiary died first, Florida’s anti-lapse rules may apply in certain circumstances.

Are heirs responsible for a deceased beneficiary’s inheritance?

  • Not necessarily. An inheritance may become part of the deceased beneficiary’s estate, and the people ultimately entitled to receive it can depend on the beneficiary’s will or Florida intestacy law.

Does a deceased beneficiary’s estate receive the inheritance?

  • When a beneficiary survives the original decedent but dies before distribution, the beneficiary’s estate may have a claim to the beneficiary’s share. The specific result depends on the nature of the interest, the will, and the circumstances of the estate.

Does Florida’s anti-lapse statute apply whenever a beneficiary dies?

  • No. Florida’s anti-lapse statute contains specific requirements and applies to certain circumstances involving beneficiaries who die before the testator. The statute should be reviewed together with the will and the family relationships involved.

Do the beneficiary’s children automatically inherit?

  • No. The beneficiary’s children do not automatically inherit simply because their parent died. They may receive property under Florida’s anti-lapse statute in qualifying circumstances, or they may inherit through their parent’s estate under different circumstances.

Can a beneficiary’s death create another probate case?

  • It can. If a beneficiary survives the original decedent and later dies while entitled to receive property, the beneficiary’s estate may need to administer that interest.

What should a personal representative do when a beneficiary dies?

  • The personal representative should establish when the beneficiary died. He needs to review the will, determine whether the beneficiary survived the decedent, identify any applicable substitute-beneficiary or anti-lapse provisions. He then needs to determine who has legal authority to receive or administer the beneficiary’s interest.

How the Florida Home Foreclosure Process Works: A Step by Step Guide for Broward County Homeowners

Florida home in a Coral Springs residential neighborhood, Broward County.

Missing mortgage payments is frightening enough. Then a letter arrives from the lender. Soon, a document from an attorney may land in your mailbox, turning a financial problem into a legal one.

If you own a home in Coral Springs or elsewhere in Broward County, you probably want to know one thing first: how much time do I have before I lose my house?

The honest answer is that it depends on where you are in the process. Florida generally requires lenders to go through the courts before foreclosing on a home. That gives you an opportunity to respond. It does not mean you can afford to ignore the paperwork while hoping the problem goes away.

And yes, the paperwork matters. A lot.

A foreclosure does not happen the moment you miss a payment. The lender must follow a legal process before the property can be sold. You may have options along the way, even if a lawsuit has already begun. What you needs is understanding where you stand before the clock runs out.


What does foreclosure actually mean in Florida?

Foreclosure is the legal process a lender uses to enforce its mortgage lien against a property. When a borrower defaults, the lender can ask a court to authorize the sale of the home to satisfy the debt.

Florida uses a judicial foreclosure system. In plain English, the lender generally has to take you to court. It cannot simply change the locks because you fell behind on your payments.

The main rules appear in Chapter 702 of the Florida Statutes. The exact procedure depends on the loan documents and the facts of your case.

Here is the important distinction: missing a payment is not the same as losing your home. Even a foreclosure lawsuit does not mean the property has already been sold.

That said, the situation gets harder to control as the case progresses. Early on, you may have time to discuss payment arrangements. Later, you could be dealing with court deadlines and a scheduled sale date. Those are very different conversations.


Step 1: You fall behind on the mortgage

Financial trouble rarely waits for a convenient moment. Perhaps your income dropped unexpectedly. Maybe an expense you did not see coming swallowed the money set aside for the mortgage. Whatever happened, the payment is now late, and the lender has noticed.

Your loan becomes delinquent when you miss a required payment. Depending on your mortgage terms, late fees may follow. The servicer will usually begin contacting you about the overdue amount.

This is the point where many homeowners start avoiding the phone. Understandable? Absolutely. Helpful? Not particularly.

Contact your mortgage servicer when you realize you may struggle to keep up with payments. Ask what assistance might be available. Get the answer in writing if possible, especially when the conversation involves a payment arrangement.

You may qualify for a repayment plan or a loan modification. Some borrowers can also request temporary forbearance, depending on their circumstances.

The Consumer Financial Protection Bureau explains the options available when you cannot pay your mortgage.

Federal rules generally restrict the first foreclosure filing until a borrower is more than 120 days delinquent, subject to exceptions. That period is not a free pass to put everything off until next month. Use the time to find out what you can do.


Step 2: The lender may send a notice of default

At some point, you may receive a formal notice stating that the loan is in default. The notice may demand payment of the overdue amount by a particular date.

Your mortgage agreement matters here. It may require the lender to give you an opportunity to cure the default before demanding the entire remaining balance. That demand is known as acceleration.

Read the notice instead of tossing it onto the kitchen counter with the other unpleasant mail. Check the amount claimed. Look at the deadline. If the figures do not match your records, ask the servicer to explain the difference.

Maybe a payment was not credited correctly. Perhaps the amount includes fees you do not understand. You need answers before deciding what to do.

A default notice is not a foreclosure judgment. Still, it is a good time to speak with an attorney. If the lender has failed to follow a requirement in your mortgage, that could matter later. The details need to be checked against the actual documents.


Homeowner reviewing a mortgage default notice at home in Florida.

Step 3: The lender takes you to court

If the default remains unresolved, the lender may file a foreclosure complaint. This starts a lawsuit seeking to enforce the mortgage.

The complaint identifies the property and explains why the lender believes it has the right to foreclose. Florida Statute 702.015 sets requirements for residential foreclosure complaints, including allegations about the lender’s right to enforce the note.

You will generally receive a summons along with the complaint. This is the moment to stop treating the situation like an ordinary billing dispute. You are now involved in a court case.

For homeowners in Broward County, the Broward County Clerk of Courts case search can help you locate public case information. But an online search will not explain what you should file or when you must file it.


What should you do when the lawsuit arrives?

Start by checking when you were served. The deadline for responding generally runs from the date of service, although the circumstances of a particular case can affect the calculation.

Under Florida Rule of Civil Procedure 1.140, a defendant generally has 20 days after service of the summons and complaint to respond. Do not rely on that number without checking your actual papers.

Contact a foreclosure attorney promptly. The attorney can review the complaint and explain what needs to happen next.

Please do not put the documents in a drawer because you feel overwhelmed. The court will not know that you needed a few weeks to get your head around everything. Deadlines keep running unless the applicable rules or a court order provide otherwise.


Step 4: You respond to the foreclosure complaint

Your response is where you formally address the lender’s allegations. Some statements may be correct. Others may need to be disputed.

An attorney can examine whether the lender has established its right to enforce the loan. The payment records may also deserve a closer look if the claimed balance seems wrong.

There may be other defenses. For example, the lender might have failed to meet a requirement in the mortgage agreement. Whether that argument helps depends on the evidence and the applicable law.

Here is why ignoring the complaint can be so costly. If you fail to respond, the lender may seek a default. That can make it much harder to contest the case later.

Already missed the deadline? Do not assume there is nothing left to do. Get legal advice immediately. Your options will depend on what has happened in the case, so an attorney needs to examine the record.


Step 5: You may still be able to reach an agreement

A foreclosure lawsuit does not automatically end negotiations. The lender may still consider a solution that addresses the default. Approval is not guaranteed, and some options may be unsuitable for your financial situation.

A loan modification changes the terms of the mortgage. It may reduce the payment or extend the repayment period. You need to check whether the revised terms are genuinely affordable.

A repayment plan spreads overdue amounts across future payments. That can help if your financial difficulty was temporary. It may be unrealistic if you are already struggling to cover the regular mortgage.

A short sale is another possibility. Under an approved arrangement, the property is sold for less than the outstanding mortgage balance. Before agreeing, make sure you understand what happens to the remaining debt.

There is also a deed in lieu of foreclosure. This involves transferring the property to the lender under an agreement rather than proceeding to a foreclosure sale.

These arrangements are not interchangeable. Each has financial and legal consequences. Never assume that handing over the keys will automatically erase the debt.

If you apply for mortgage assistance, keep records of what you submit. Respond to requests for additional documents. Missing paperwork can delay the review or complicate your application.

The CFPB’s guide to avoiding foreclosure explains how to work with your mortgage servicer. A HUD approved housing counselor may also be able to help at little or no cost.

One final warning: be suspicious of anyone who guarantees they can save your home. A company demanding a large upfront fee in exchange for a promised foreclosure rescue deserves particular scrutiny. Before signing anything that transfers your property, get independent legal advice.


Florida attorney reviewing home foreclosure documents with a homeowner.

Step 6: The court decides how the case proceeds

If no agreement is reached, the lawsuit continues. The court may consider motions before deciding whether the lender is entitled to foreclose.

The lender must establish its legal right to enforce the loan. You have an opportunity to challenge the claim when a valid defense exists. Depending on the case, the dispute may be resolved through motions or proceed to trial.

Some Florida cases may use an expedited procedure under Florida Statute 702.10. This process has specific requirements. If you receive an order to show cause, pay close attention to its instructions because the response period may be short.

Not every foreclosure case ends in a courtroom trial. A judge may be able to decide the matter based on the filings and evidence. That does not make the process unimportant. It means the documents and deadlines can carry enormous weight.

This is also where a lawyer’s work may become especially important. A detail that looks insignificant to someone unfamiliar with foreclosure law may affect the case. You want to know about that detail before the judge rules, not afterward.


Step 7: The court may issue a final judgment

If the lender wins, the court may enter a final judgment of foreclosure. The judgment establishes the amount owed under the court’s findings and authorizes the sale of the property under the applicable procedure.

At this point, you are dealing with a formal court ruling rather than a demand from the lender. The judgment will contain information that matters to the next stage of the case.

Read it carefully with your attorney. Pay attention to the amount the court has determined is due. The scheduled sale date matters too.

A final judgment does not mean the property has already been sold. But the time available to prevent the sale may now be limited.

If you are still negotiating with the lender, get clear confirmation of any agreement that affects the case. Do not assume a phone conversation has postponed the sale. Make sure the necessary arrangements are actually in place.


Step 8: The property goes to foreclosure sale

If the case reaches this stage, the property is scheduled for sale through the court authorized process. In Broward County, the Clerk of Courts website provides official information about court services.

The sale date deserves your full attention. If you hope to resolve the debt before the property is sold, you need to know exactly how much time remains.

There may be legal grounds to challenge a sale or request relief in certain circumstances. Such relief is not automatic. The facts matter, and timing can be decisive.

Florida law provides a right of redemption, but the deadline is easy to misunderstand. Under Florida Statute 45.0315, a homeowner may generally redeem the property by paying the amount required under the judgment. The deadline is the later of the time specified in the judgment or the filing of the certificate of sale.

In practical terms, do not assume that the scheduled auction is your only deadline. The judgment may set a specific cutoff, and the certificate of sale affects the calculation. Once a foreclosure sale is approaching, ask an attorney to confirm the exact deadline in your case. This is not a situation where guessing a date is worth the risk.


Step 9: What happens after the foreclosure sale?

After the sale, the clerk generally issues a certificate of sale. The process may then lead to a certificate of title, transferring ownership to the successful purchaser after the applicable period and subject to any timely objections.

The former owner may eventually have to leave the property. The timing depends on the legal proceedings and any applicable orders. Do not assume that you must leave the moment the sale occurs, but take any court order seriously.

There is another issue that can follow you beyond the property itself: the remaining debt.

If the foreclosure sale does not cover the amount owed, the lender may ask the court for a deficiency judgment. Under Florida Statute 702.06, the court has discretion over whether to grant one.

For an owner occupied home, the law also limits the amount of a deficiency judgment. The calculation is based on the judgment amount, or the outstanding debt in a short sale, minus the property’s fair market value on the date of sale. A homestead tax exemption can create a rebuttable presumption that the property qualifies as owner occupied.

So, the unpaid balance on your mortgage does not automatically become the amount of a deficiency judgment. The court must apply the relevant legal rules. Whether the lender pursues a deficiency is another question entirely.

Before signing a settlement or surrender agreement, ask what happens to any remaining debt. That answer may matter long after you have moved out.


Courthouse representing the judicial foreclosure process in Florida.

What happens if the homeowner has died?

A foreclosure can become more complicated when the borrower dies before the case is resolved. The mortgage does not disappear with the homeowner.

The next steps depend on how the property was titled. A surviving family member may have an interest in the home without being personally responsible for the mortgage debt. Those are separate questions that need to be examined.

If the property belongs to a probate estate, the personal representative may need to address the home as part of estate administration. Florida probate law governs the estate’s authority and responsibilities, while the mortgage lien remains a separate concern.

This can be especially difficult for a family already dealing with a death. Relatives may assume that the house can simply be sold or transferred to keep it out of foreclosure. That may not be possible without first resolving who has legal authority to act.

A lawyer familiar with Florida probate and real estate matters can help clarify the situation. If the family hopes to keep the property, getting that advice early is particularly important.


What if you own a business too?

A business owner facing foreclosure may have another financial problem hiding in the background. Perhaps the business has lost income, leaving less money available for the mortgage. In some cases, a personal guarantee on a business loan can add another layer of financial exposure.

These circumstances do not change the basic foreclosure procedure. They may affect the decisions you make about the home, however.

Before agreeing to sell the property or use other assets to settle a debt, have the relevant obligations reviewed. When a business loan and a home mortgage affect the same household finances, advice from a business attorney may need to be coordinated with foreclosure counsel.

The point is not to turn a mortgage problem into a bigger legal project than necessary. It is to avoid making a rushed decision about the house without understanding the obligations attached to it.


Why getting legal advice early can matter

Many homeowners wait until the lawsuit arrives before calling an attorney. Some hope the problem will be temporary. Others feel embarrassed about falling behind. A few simply do not know where to start.

There is no need to feel ashamed about asking for help. Financial trouble can happen to people who have worked hard for years. The lender is still entitled to enforce a valid mortgage, but you are entitled to understand the process and consider your legal options.

Early advice can help you understand the loan documents before deadlines become urgent. It may also reveal problems with the lender’s figures or the notices it sent.

Once the lawsuit begins, an attorney can help you respond properly. If a settlement is possible, the terms need to be reviewed before you commit.

No lawyer can promise that you will keep your home. Anyone who guarantees that outcome is promising something beyond their control. Good legal advice means knowing where you stand and deciding what to do with that information.

For homeowners in Coral Springs and throughout Broward County, the earlier you get a clear picture of your situation, the more useful that advice may be.


Frequently asked questions about Florida home foreclosure

How long does foreclosure take in Florida?

  • There is no fixed timeline for every case. The court’s schedule and the circumstances of the dispute can affect how long the process lasts. A contested case may take considerably longer than one in which the borrower does not respond.

Can a lender foreclose without going to court in Florida?

  • Residential mortgage foreclosure generally requires a judicial proceeding. The lender must obtain the necessary court relief before the property can be sold through foreclosure.

Can I stop foreclosure after the lawsuit has been filed?

  • Possibly. A lender may agree to a resolution through loss mitigation. A valid legal defense may also affect the outcome. The available options depend on the stage of the case and the facts.

Do I have to leave my home as soon as the lender files a lawsuit?

  • No. Filing the complaint does not itself transfer ownership. The case must proceed through the applicable legal process, and you should follow any court orders that apply to your situation.

Can the lender still seek money after the foreclosure sale?

  • Yes, in some circumstances. If the sale proceeds fall short of the debt, the lender may seek a deficiency judgment. The court has discretion over whether to grant one. For an owner occupied home, Florida law limits the amount using the property’s fair market value on the date of sale. The precise calculation depends on the circumstances.

What should I do if I receive foreclosure papers in Broward County?

  • Read the documents immediately and identify the response deadline. Contact a foreclosure attorney as soon as possible. You can use the Broward County Clerk’s case search to find public case information, but the search tool cannot tell you how to defend the lawsuit.

inherited-home-mortgage-foreclosure-florida.

Talk to an attorney about your situation

A foreclosure notice can make it feel as though the outcome has already been decided. It has not. The legal process still has to run its course, and your options depend on the facts.

Reinfeld & Cabrera, P.A. serves clients in Coral Springs and across Broward County. If you are facing foreclosure, the firm can help you understand the legal process and assess what may be possible in your circumstances.

Contact the firm to discuss your situation. Getting a clear answer about where you stand is a sensible first step.

What Happens to Your Estate Plan After You Move to Florida?

Estate planning documents being moved into a new Coral Springs home

You moved to Florida. Your will is still in a drawer in New Jersey, your power of attorney names your brother in Pennsylvania, and your new house is in Coral Springs.

Do you need to start your estate plan over?

Usually, that is not the right way to think about it.

Florida recognizes certain wills executed in another state if they were valid where they were signed. The same is true for certain powers of attorney executed elsewhere. Trusts can also remain valid after a move, depending on how and where the trust was created and what its terms provide.

The more useful question is different:

Does the estate plan you created before moving to Florida still work the way you intended?

That matters because your documents may have been written around a different home, different state laws, different property, different family circumstances, and different people serving as fiduciaries.

For someone who has recently settled in Coral Springs, Broward County, or elsewhere in South Florida, the move itself may be the least important part of the review. What matters is what changed along with it.


Your old will may still be valid

Moving from another state does not automatically mean that your will has to be rewritten.

Florida law provides that a will executed by a nonresident can be valid in Florida if it was valid under the law of the state or country where it was executed, subject to the statute’s exceptions.

That answers one question.

It does not answer the more important one.

Imagine that you signed your will fifteen years ago while living in New Jersey. At the time, you owned a house there, your children were young, your sister lived nearby, and you expected your estate to be handled there.

Now you live in Coral Springs. You sold the New Jersey house. You own a Florida home. One child lives in Georgia and another lives in California. Your sister has retired and no longer wants to serve as your personal representative.

The old will may still be a valid document.

It may also be a poor description of the life you have now.

Those are two different issues.


The Florida house can change the analysis

One of the biggest reasons a Florida move deserves an estate planning review is the home itself.

Florida’s homestead rules are unusually important in estate planning. The Florida Constitution restricts the ability of a homeowner to devise homestead property when the owner is survived by a spouse or minor child. Florida law contains corresponding restrictions on the devise of homestead.

That can create a problem for someone who arrives in Florida with an estate plan designed around the rules of another state.

Consider a simple example.

A person moves to Coral Springs, buys a home, and updates a will saying that the house should pass to a particular child. The person is married and has a minor child.

The sentence in the will may look perfectly clear.

That does not necessarily mean the person can dispose of the Florida homestead in that manner.

Florida’s homestead rules can control what happens to the property regardless of what the old estate plan appears to say.

This is one reason an estate plan should be reviewed after a move rather than simply filed away because the documents themselves remain technically valid.


What if your power of attorney was signed somewhere else?

The same question comes up with powers of attorney.

Florida law provides that an out-of-state power of attorney can be valid in Florida when it complied with the law of the state where it was executed.

So an older power of attorney is not automatically worthless because you crossed the Florida border.

But there is a practical issue that is easy to overlook.

The person you appointed may no longer be the person you want handling your affairs.

Your power of attorney might name a sibling who lives 1,200 miles away. Your adult child might now be the person who actually helps you with financial matters. Or the person you originally chose may have become unavailable, died, or simply no longer be the right choice.

There is also a difference between an instrument being legally valid and a particular bank, title company, or other institution being willing to accept it without additional questions.

That distinction matters when the power of attorney may be used for Florida real estate or other significant transactions. Florida’s statute specifically addresses the acceptance of certain out-of-state powers of attorney and permits a third party to request a legal opinion in some circumstances.

A move to Florida is therefore a good reason to find the original document, identify the current agent and successor agents, and determine whether the document still gives them the authority you intended.


You already have a trust. Does Florida change it?

Trusts require a little more care because there is no single answer that applies to every trust.

Florida law recognizes certain trusts created under the law of another jurisdiction. A trust that was not created by a will can generally be validly created if its creation complied with the law of the jurisdiction where the trust instrument was executed or where the settlor was domiciled when the trust was created.

But the question of which state’s law governs the trust can be separate from the question of whether the trust was validly created.

Florida law looks first to the governing-law provisions in the trust when they are valid and supported by a sufficient connection to the designated jurisdiction. If the trust does not contain a controlling designation, other rules determine the applicable law.

The trust’s principal place of administration can matter too. Florida law addresses how that location is determined and allows certain trusts to change their principal place of administration when the statutory requirements are satisfied.

In practical terms, someone who moves to Florida should not assume either of these things:

“My old trust is invalid now.”

or

“Nothing about my trust needs to be examined.”

The actual trust document matters.

So does the property inside it, the trustee, the beneficiaries, the governing-law clause, and where the trust is now being administered.


Florida homestead and estate planning considerations for a Broward County home

The bigger problem may be the people named in your documents

Sometimes the move to Florida exposes a problem that has nothing to do with state law.

Look at the names in the documents.

Who is your personal representative?

Who is the successor personal representative?

Where is your trustee?

Who takes over if your first choice cannot serve?

Which one has your financial power of attorney?

Who receives your property?

These choices can become outdated surprisingly quickly.

A will written when your children were teenagers may still contain their correct names but give responsibility to a relative who is now elderly. A trust created before a second marriage may still refer to a former family structure. A beneficiary designation on a retirement account may tell a completely different story from the will sitting in your safe.

That last point is particularly important because an estate plan is not contained in one document.

Your will may control some property. A trust may control other property. Beneficiary designations can control retirement accounts, life insurance, and other assets. Joint ownership can affect what happens to property after death.

Moving states is therefore a useful moment to compare the documents against the actual ownership of your assets.


What if you still own property in the state you left?

Florida may be your new home without being the only place where you own property.

You might have kept a rental property in New York, a vacation home in North Carolina, land in Georgia, or a family property that has been in your name for decades.

That creates a different question.

Where is the property, and how is it owned?

A Florida estate plan may need to account for property located elsewhere. Depending on the property and how it is titled, administration in another jurisdiction may still be necessary after death.

This is one reason a new Florida resident should bring the actual asset picture into the estate planning review. Looking only at the will can miss the problem.

A person can have a perfectly coherent will and still have an estate that is difficult to administer because the ownership of the assets does not match the plan.


What should you actually review after moving to Florida?

You do not necessarily need to replace every document.

Start with the documents and facts that changed.

  • Your will: Check the beneficiaries, personal representative, backup choices, and the way your property is described.
  • Your Florida home: Determine whether the property is your homestead and whether Florida’s homestead restrictions affect the plan.
  • Your trust: Check its governing law, trustee, beneficiaries, assets, and principal place of administration.
  • Your power of attorney: Confirm that the agent and successor agents are still the people you want making financial decisions.
  • Your beneficiary designations: Compare retirement accounts, insurance policies, and other accounts with the plan in your will and trust.
  • Your family: Marriage, divorce, new children, deaths, and changes in relationships can matter just as much as the change of address.
  • Your other property: Identify real estate and significant assets that remain outside Florida.

The goal is not to produce a new stack of documents simply because you have a new address.

The goal is to make sure the documents, ownership of your property, and your current circumstances are telling the same story.


Homeowner reviewing an out of state estate plan after moving to Florida

A Florida move is a good time to ask a different question

People often ask, “Is my old will still valid in Florida?”

That is a reasonable starting point.

It is not where the review should end.

Florida law gives substantial recognition to properly executed estate planning documents from other jurisdictions. But validity is only one piece of the problem. A document can survive a move perfectly well while becoming less useful because the people, property, or circumstances behind it have changed.

For a new Florida resident, the most important question is usually whether the existing plan still matches the life that exists now.

That is particularly worth examining when you have purchased a Florida homestead, married or divorced, had children, changed fiduciaries, acquired substantial property, or retained real estate in another state.

For families in Coral Springs and Broward County, an estate planning review can also identify Florida-specific issues before they become probate problems.


Frequently Asked Questions

Does moving to Florida invalidate an out-of-state will?

  • Not necessarily. Florida law recognizes certain wills executed by nonresidents when the will was valid under the law of the state or country where it was executed.

Do I need a new will after moving to Florida?

  • Not automatically. Whether a new will is appropriate depends on the existing document, your family circumstances, your property, and Florida-specific issues such as homestead.

Can Florida recognize a power of attorney from another state?

  • Florida law provides for recognition of certain powers of attorney executed in another state when they complied with the law of the state where they were executed.

Does my trust remain valid if I move to Florida?

  • It may. Florida recognizes certain trusts created under the law of another jurisdiction. The trust’s governing-law provisions, creation, administration, and assets can all matter.

Does buying a Florida home affect my estate plan?

  • It can, especially if the property qualifies as your Florida homestead. Florida’s Constitution and statutes place restrictions on the devise of homestead in certain family situations.

What should I do with my estate plan after moving to Florida?

  • Have the existing documents reviewed against your current circumstances. Pay particular attention to your Florida home, beneficiaries, fiduciaries, beneficiary designations, trusts, and property that remains in another state.

How to Protect Cryptocurrency and Digital Assets in Your Florida Estate Plan


Direct Answer:

Under the Florida Fiduciary Access to Digital Assets Act (Fla. Stat. Chapter 740), standard Last Will and Testament provisions do not grant your personal representative or executor legal authority to access, manage, or transfer online brokerage accounts, cryptocurrencies, or digital wallets. Without specific fiduciary powers and explicit digital consent language in your estate documents, online custodians will legally lock your family out of digital wealth forever.

Most people meticulously plan for physical assets like homes in Coral Springs, bank accounts, and personal vehicles. However, they completely overlook the massive portfolio of digital wealth they accumulate over a lifetime.

From online brokerage accounts and digital business portals to cryptocurrency wallets, NFTs, and high value cloud storage, modern wealth is increasingly digital. Under federal privacy laws and strict technology agreements, if you pass away or become incapacitated without explicit digital asset provisions in your estate plan, your loved ones face an impenetrable digital wall.


The Legal Barrier: Federal Privacy vs. Florida Probate Authority

When a family member passes away, executors assume they have the inherent legal right to log into computers, unlock smartphones, and access online financial portals. In reality, doing so can violate federal laws such as the Stored Communications Act (SCA), and technology companies routinely freeze accounts when presented with standard death certificates unless specific legal authorization is established.

The Limits of Standard Wills

A traditional Last Will and Testament distributes physical property, but it rarely grants the specific fiduciary legal authority required by tech platforms like Apple, Google, Coinbase, or Fidelity to turn over control of digital accounts. Without targeted language authorized by state statute, tech providers will legally refuse to cooperate with your personal representative.


The Florida Fiduciary Access to Digital Assets Act

To resolve these conflicts, Florida enacted Chapter 740 of the Florida Statutes, formally known as the Florida Fiduciary Access to Digital Assets Act. This legal framework establishes how digital executors and trustees can interact with online custodians, but it relies heavily on how you draft your legal documents while you are alive.


1. The Order of Priority for Digital Access

Under Fla. Stat. § 740.04, online custodians look for instructions in a specific hierarchical order:

  • First Priority: An online tool provided by the tech platform itself (such as a Google Inactive Account Manager or Apple Legacy Contact).
  • Second Priority: Explicit directions written inside a governing legal instrument such as a Revocable Living Trust, a Last Will and Testament, or a Durable Power of Attorney.
  • Third Priority: The standard terms of service agreements of the digital platform if no estate planning instructions exist (which frequently result in permanent account closure).

2. The Danger of Leaving Crypto Keys Unmanaged

Cryptocurrencies like Bitcoin and Ethereum operate entirely on decentralized blockchains secured by private cryptographic keys and seed phrases. If an investor passes away without leaving structured instructions and secure access protocols for their personal representative, that digital currency is locked in the blockchain forever with zero customer support numbers to call and no court order that can reset a password.


How to Properly Structure Digital Asset Protection

Integrating digital wealth and online accounts into a comprehensive Broward County estate plan requires specific legal drafting:

1. Digital Fiduciary Powers in Powers of Attorney

To prevent financial chaos during a medical emergency or mental incapacity, your Durable Power of Attorney (Fla. Stat. § 709.2104) must explicitly grant your designated agent the statutory authority to access, control, and modify your digital accounts, online banking portals, and electronic communications.

2. Trust and Will Custody Provisions

Your estate planning documents should explicitly name a digital executor or trustee empowered to handle digital assets, paired with comprehensive language waiving traditional liability so your fiduciary can lawfully navigate encrypted files and digital currency exchanges.

3. Secure Asset Inventory and Access Protocols

While sensitive passwords and private seed phrases should never be written directly into public legal documents like a Last Will and Testament (which becomes a public court record during probate), your plan should incorporate a secure, confidential memorandum or encrypted digital vault instruction sheet maintained alongside your estate portfolio.


Frequently Asked Questions

Can my executor legally access my email or online accounts with just a Will in Florida?

  • Usually no. Under federal privacy protections and the Florida Fiduciary Access to Digital Assets Act, tech custodians require specific statutory authorization or court orders explicitly granting digital access rights to your personal representative.

Should I write my cryptocurrency seed phrases in my Living Trust?

  • No. Trusts become accessible public records during formal trust administration or probate. Private keys and cryptocurrency seed phrases should be stored securely using encrypted offline hardware or specialized digital asset management tools referenced confidentially by your estate plan.

How does Florida law treat digital currency during probate?

  • Cryptocurrency and digital tokens are legally classified as intangible personal property under Florida law. They must be inventoried, appraised, and distributed through probate or trust administration just like traditional stocks or bank accounts, provided the executor can access the wallet.

Safeguard Your Digital Legacy in Coral Springs

As personal wealth shifts online, ensuring your digital assets and cryptocurrency holdings are legally protected is critical to preventing family disputes and permanent financial loss. The legal team at Reinfeld & Cabrera, P.A. helps clients across Broward County secure both their traditional and digital estates.


Schedule a Free Confidential Consultation

Ensure your digital portfolio remains fully protected under Florida law:

  • Direct Phone: (954) 866-4878 | (954) 334-1520
  • Coral Springs Main Office: 9625 W Sample Rd, Coral Springs, FL 33065
  • Fort Lauderdale Office: 2933 W Cypress Creek Rd, Suite 201, Ft Lauderdale, FL 33309
  • Website: mypersonalattorneys.com