When someone dies, their family may need to go through probate before certain assets can be transferred to the people entitled to receive them. Probate is a court supervised process used to identify and gather probate assets, address valid debts and creditor claims, and distribute the remaining property according to the will or Florida law.
For families in Coral Springs, Broward County, and throughout South Florida, the process can raise practical questions quickly. Which assets have to go through probate? Who handles the estate? How are creditors paid? How long does the process take? And does every estate requi3re the same type of probate administration?
The answers depend on the assets involved, the existence and terms of a will, the value of the estate, creditor issues, and other circumstances.
What Is Probate in Florida?
Probate is a legal process for administering a deceased person’s probate estate. Florida courts describe probate as a court supervised process for identifying and gathering assets, paying debts, and distributing assets to beneficiaries. Probate generally applies only to probate assets, rather than everything the deceased person owned.
A probate asset may include a bank or investment account held solely in the deceased person’s name, or certain real property owned individually by the deceased. Assets with a valid mechanism for passing automatically to another person may not need to be administered through probate.
This distinction matters because a person’s total property does not necessarily equal the property that must be handled through a probate proceeding.
What Are the Steps in the Florida Probate Process?
Although every estate is different, a probate administration commonly involves several stages.
1. The probate case is opened
The proceeding is generally filed with the clerk of the circuit court in the appropriate Florida county. Venue is ordinarily based on the deceased person’s domicile at the time of death.
The documents required at the beginning of the case depend on the circumstances, including whether the deceased person left a will and which type of administration is appropriate.
2. The will is submitted to the court, if there is one
If the deceased left a will, it must be presented to the probate court and admitted according to Florida law.
A will does not, by itself, transfer every asset immediately to the people named in it. Probate may still be necessary to establish the authority to administer probate assets and complete the estate administration.
If there is no valid will governing the property, Florida’s intestacy laws determine who is entitled to inherit.
3. A personal representative is appointed
Florida generally uses the term personal representative for the person appointed to administer a probate estate.
The personal representative’s responsibilities can include identifying estate assets, dealing with creditors, protecting estate property, paying authorized expenses and obligations, and eventually distributing assets to the appropriate beneficiaries or heirs.
The personal representative is a fiduciary. Florida law requires that person to administer and distribute the estate consistently with the will and the law and to act in the best interests of the estate and interested persons.
The person nominated in a will may have priority for appointment, although the court must still apply Florida’s statutory requirements concerning who may serve.
4. The estate’s assets are identified and gathered
The personal representative must determine what property belongs to the probate estate and take the steps necessary to administer those assets.
This can involve locating financial accounts, real property, personal property, business interests, or other assets. It can also require determining whether particular assets pass outside probate because of joint ownership, beneficiary designations, trusts, or other arrangements.
This is one reason a probate case cannot always be understood simply by looking at the deceased person’s will.
5. Creditors are given an opportunity to file claims
An estate may have outstanding debts when someone dies. Florida law provides procedures for notifying creditors and establishing deadlines for claims against the estate.
A creditor’s claim generally must be filed within the applicable statutory period. Under Florida Statutes section 733.702, many claims must be filed no later than the later of three months after the first publication of the notice to creditors or 30 days after service of the notice on a creditor who is required to receive it. Untimely claims can be barred, subject to limited statutory exceptions.
The personal representative may also have to evaluate and respond to claims filed against the estate. A disputed claim can create additional proceedings and delay the administration.
6. Valid expenses and obligations are paid
Not every debt or expense is treated identically.
Florida law establishes an order of priority for paying expenses and obligations of an estate. Administration expenses, certain funeral expenses, specified taxes and debts, certain medical expenses, family allowances, and other obligations fall into statutory classes.
This means that simply finding a debt does not necessarily answer the question of whether, when, or how it will be paid.
7. Remaining assets are distributed
After the estate’s obligations have been addressed and the requirements for distribution have been satisfied, the remaining probate assets can be distributed to the beneficiaries named in the will or to the heirs entitled to receive property under Florida’s intestacy laws.
The personal representative must follow the governing legal documents and Florida law rather than simply distributing property according to informal family agreements.
8. The estate is closed
The final stage involves completing the administration and taking the steps required to close the probate estate.
The timing varies considerably. A straightforward estate with few assets and no disputes can be very different from an estate involving contested claims, difficult-to-value property, creditor disputes, litigation, or disagreements among beneficiaries.
Does Every Florida Estate Go Through the Same Probate Process?
No.
Florida recognizes formal administration and summary administration, along with limited circumstances in which certain personal property can be transferred without a formal administration.
Formal Administration
Formal administration is the more extensive probate procedure. It can involve the appointment of a personal representative, administration of estate assets, creditor procedures, payment of obligations, and distribution of the remaining property.
It is generally used when the circumstances of the estate require a full administration.
Summary Administration
Summary administration is a shorter procedure available when the statutory requirements are met.
Under current Florida law, summary administration may be available when the value of the estate subject to administration, after accounting for property exempt from creditor claims, does not exceed $150,000, or when the deceased person has been dead for more than two years.
The court can enter an order directing distribution of the estate’s assets, but summary administration still involves legal requirements concerning beneficiaries, assets, and creditors.
A smaller estate is therefore not automatically the same thing as an estate that requires no probate.
How Long Does Probate Take in Florida?
There is no single timeline that applies to every Florida probate case.
The length of an estate administration can depend on:
The type of probate administration
The number and nature of the estate’s assets
Whether real estate must be transferred or sold
Whether creditors file claims
Whether a claim is disputed
Whether beneficiaries disagree
Whether litigation becomes necessary
Whether assets are difficult to locate or value
Whether tax or other financial issues require additional work
Creditor procedures can also create important timing requirements. For example, Florida law establishes specific periods for filing and objecting to creditor claims and provides rules governing when certain claims may be paid.
For that reason, estimates based solely on the size of an estate can be misleading.
What Happens If Family Members Disagree During Probate?
Probate does not automatically prevent disputes between beneficiaries, heirs, creditors, or the personal representative.
Disagreements can involve the validity or interpretation of a will, the identification or valuation of assets, creditor claims, the conduct of the personal representative, or the proposed distribution of estate property.
Some issues can be resolved without extended litigation. Others require court intervention.
The personal representative has fiduciary duties during administration, and Florida law provides procedures for addressing problems involving the administration of an estate.
Does Having a Will Avoid Probate in Florida?
Not necessarily.
A will tells the court how the deceased person wants certain property distributed, but having a will does not automatically eliminate the need for probate.
Whether an asset passes through probate depends on how that asset is owned and whether another legal mechanism controls its transfer at death.
This is why estate planning and probate are related but distinct subjects. A person can have a carefully prepared will and still have a probate estate requiring court administration.
When Should You Speak With a Probate Attorney?
Professional advice can be particularly important when an estate includes significant assets, real property, creditor issues, business interests, disputed claims, beneficiary disagreements, or questions about the personal representative’s conduct.
The right approach also depends on whether the estate qualifies for summary administration or requires formal administration.
For families in Coral Springs, Broward County, and South Florida, understanding the type of estate involved is often the first step toward understanding what the probate process will actually require.
Frequently Asked Questions About the Florida Probate Process
What is the first step in probate in Florida?
The first step depends on the circumstances of the estate, but probate generally begins with filing the appropriate documents with the circuit court in the proper county. If there is a will, it is submitted to the court as part of the probate process.
How long does probate take in Florida?
There is no fixed timeline for every estate. The length depends on the type of administration, the assets involved, creditor issues, disputes, and other circumstances.
What is the difference between formal and summary probate in Florida?
Formal administration is the more extensive probate procedure. Summary administration is a shorter procedure available when statutory requirements are satisfied, including the current $150,000 estate value threshold or the alternative two year period after death.
Does every asset have to go through probate?
No. Probate generally applies to probate assets. Certain jointly owned assets, beneficiary designated accounts, and other property may pass outside probate depending on how they are structured.
What does a personal representative do?
A personal representative administers the estate. Duties can include gathering assets, dealing with creditor claims, paying authorized expenses and obligations, and distributing property according to the will and Florida law. The personal representative also has fiduciary duties to the estate and interested persons.
Can probate become a lawsuit?
Yes. Probate is a court proceeding, and disputes concerning wills, assets, creditor claims, beneficiaries, or estate administration can require litigation or other contested proceedings.
Can a Florida estate avoid formal probate?
Sometimes. Florida law provides summary administration for qualifying estates and limited procedures for disposing of certain personal property without administration. Whether one of these alternatives applies depends on the specific facts of the estate.
Probate Guidance for Families in Coral Springs and Broward County
Probate is not one identical process for every Florida family. The appropriate procedure depends on the person’s assets, debts, estate planning documents, beneficiaries, and other circumstances.
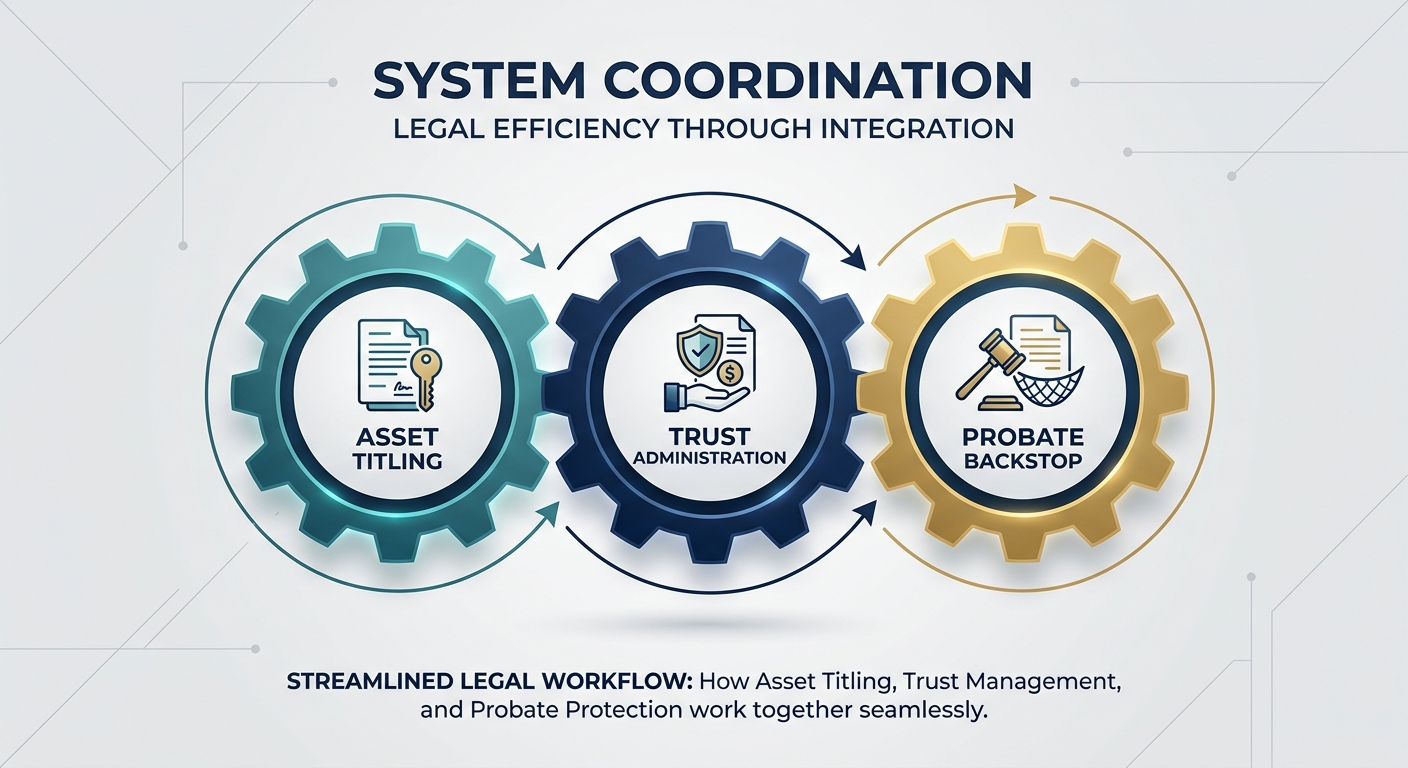
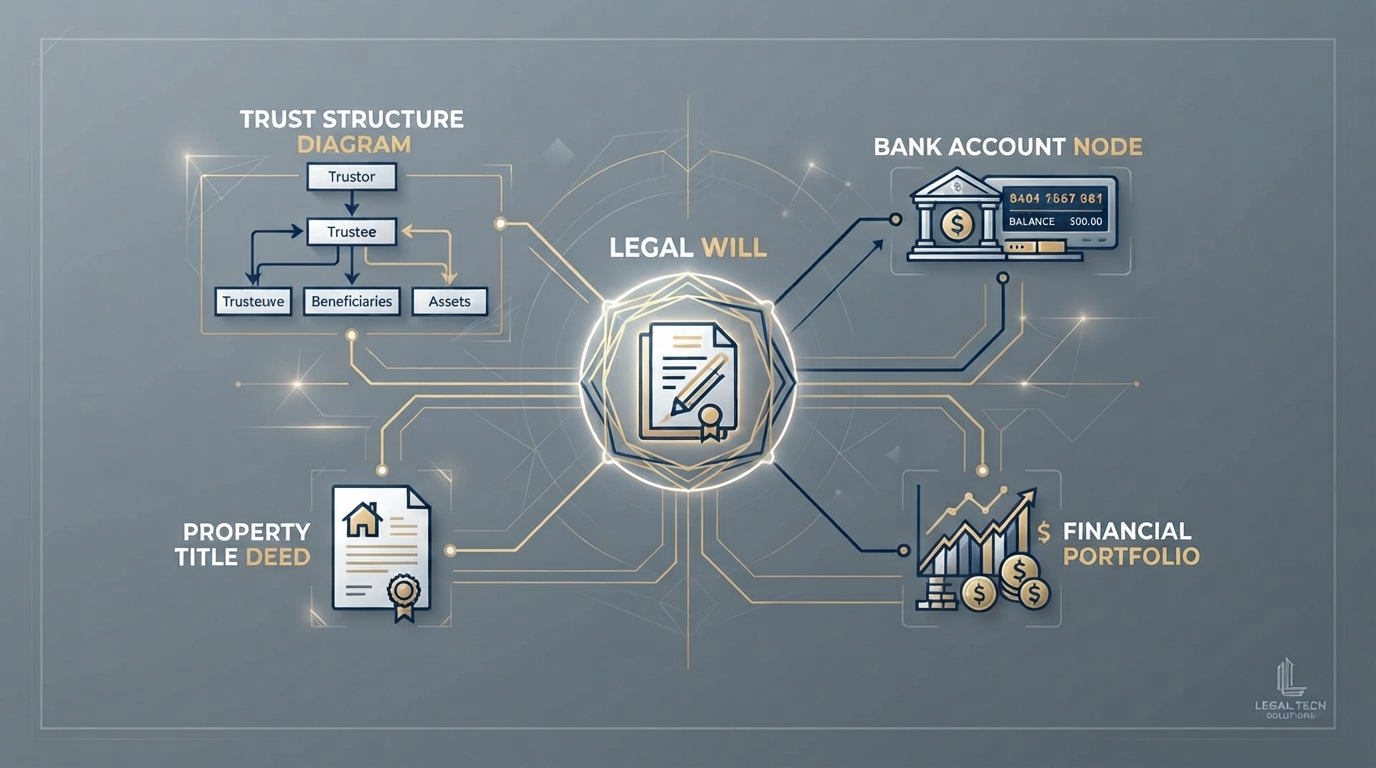
An estate plan under Florida law is not a single isolated document, but an interlocking system of distinct legal instruments.
To function effectively, it coordinates asset titling (how property is owned), contractual beneficiary designations (such as life insurance and retirement accounts that bypass probate), revocable living trusts (for private asset management), and a Last Will and Testament (which acts as an administrative backstop for stray assets and nominates guardians for minor children under the 17th Judicial Circuit probate framework).
Direct Transfer InstrumentsBeneficiary designations and trusts that bypass probate to route funds directly to intended recipients.
The Backstop AdministrationWills and probate courts acting as the administrative safety net for any leftover or stray assets.
A common misconception among clients entering an attorney’s office is that estate planning is merely a shopping exercise. People assume they need to choose between buying a will or setting up a trust. As if these documents were competing consumer products on a shelf.
In practice, a durable estate plan functions less like a single document and more like an interlocking machine. Each piece: whether it is a deed, a beneficiary designation, a trust agreement, or a last will and testament – answers a different legal question about your property, your care, and your family’s future security under Florida law.
Asset Ownership Sets the Foundation
Every legal instrument relies entirely on the underlying registration of your property.
The name on a title holds more legal authority over where property goes than almost any standard clause you can write down. Consider how differently law treats various holdings. A commercial storefront in Coral Springs tied to a corporate entity, a family home structured with survivorship rights, or an ordinary checking account carrying no payable on death instructions. Each follows its own strict statutory track.
Property registration and testamentary instruments point in opposite directions. The title or contractual beneficiary designation almost always supersedes your written documents. For instance, naming a child in a will has no legal effect on a bank account where a different individual is listed as the sole payable on death recipient. A thorough planning process evaluates these existing ownership titles first. Therefore ensuring that deeds, corporate shares, and financial accounts are adjusted or harmonized before any wills or trusts are finalized.
Different Assets Can Follow Different Paths
When an individual passes away, their property does not automatically flow down one universal river. Different asset classes utilize entirely distinct legal conduits:
Contractual Transfers: Life insurance policies, retirement accounts, and payable on death bank accounts bypass both wills and trusts entirely. Thus transferring directly to named beneficiaries by operation of contract law.
Trust Administration: Assets properly titled in the name of a revocable living trust flow privately through trustee administration without judicial interference.
Probate Administration: Assets left solely in an individual name with no beneficiary designation must be processed through the probate court system.
Understanding that these pathways operate simultaneously is the key to grasping how an estate plan actually functions.
The Operational Reality of Financial Accounts and Institutional Payables
A common blind spot in estate planning is assuming that legal documents command absolute authority over every dollar an individual owns. In practice, financial institutions, such as major banks operating in Coral Springs and regional credit unions, don’t act like this. They do not look to your will or trust first when an account holder passes away.
Instead, financial operations are strictly governed by internal institutional protocols and direct account contracts. When a bank representative reviews an account after a death certificate is presented, they execute whatever binding agreement is physically attached to that specific account file. If a bank ledger lists an individual payable on death designation, or if a brokerage account registers a transfer on death instruction, institutional compliance departments are legally bound to disburse those funds directly to the named individual, bypassing any instructions found in a trust agreement or a court supervised will.
An integrated estate plan accounts for this operational friction by auditing every institutional account agreement during the drafting phase. Therefore ensuring that corporate paperwork matches your overarching legal strategy before a financial institution ever faces a disbursement decision.
Where the Will Fits Into the Plan
Rather than acting as the absolute ruler of your entire estate, a Last Will and Testament serves a specific structural purpose within the broader system.
Within an integrated plan, a will functions primarily as a legal backstop. It catches stray assets that were never retitled into a trust. Names guardians for minor children. It also nominates the personal representative to manage the probate administration process if court intervention becomes necessary.
Where a Trust Fits Into the Plan
A revocable living trust operates as an alternative operating system for asset management and distribution.
When properly funded during your lifetime, the trust holds legal title to your major property holdings. Instead of directing asset distribution through public probate filings, the trust instrument coordinates private management rules. It establishes exact conditions for beneficiaries, and governs how assets are handled if you experience temporary or permanent incapacity.
If certain assets remain outside your trust or lack beneficiary designations, the probate court becomes the mandatory administrative mechanism required to clear title and transfer ownership. The goal of comprehensive planning is not always to eliminate every possibility of court involvement, but to ensure that probate handles only what is necessary while private mechanisms handle the bulk of your wealth.
What Happens When the Pieces Do Not Match?
The most critical test of an estate plan occurs when its individual instruments conflict with one another.
Consider a scenario where an individual executes a trust directing that their financial account be divided equally among three children, but the underlying bank account form lists only one child as a payable on death beneficiary. Under Florida law, the contractual beneficiary designation on the account typically overrides the instructions in the trust or will.
When beneficiary designations, trust agreements, and asset titles point in opposing directions, family disputes and unintended disinheritances frequently follow. Coordination prevents these friction points.
Through durable powers of attorney and healthcare surrogate designations, your plan designates trusted individuals to manage financial transactions, sign documents, and make medical decisions if you are unable to speak for yourself. These instruments integrate seamlessly with your property management framework, ensuring continuity whether you are navigating daily life or managing a medical crisis in Broward County.
Frequently Asked Questions
Does having a revocable living trust mean my estate will completely avoid probate in Florida?
Not automatically. A trust only avoids probate for assets that were properly titled in the name of the trust during your lifetime. Any remaining individually owned assets left outside the trust at the time of death will still require a probate administration unless alternative transfer mechanisms apply.
Can a beneficiary designation override the instructions written in my last will and testament?
Yes. Contractual arrangements such as life insurance policies, retirement accounts, and payable on death bank accounts operate independently of a will. The financial institution distributes funds directly to the named beneficiary on file, regardless of what your will states.
Why is asset titling just as important as drafting a will or trust?
Asset titling dictates the legal pathway property travels upon death or incapacity. If your legal documents specify one distribution plan but your deeds or account titles are registered under a conflicting ownership structure, the ownership title or beneficiary form frequently overrides your written documents.
How does local court jurisdiction in Broward County affect the administration of an estate plan?
When an estate plan requires judicial oversight, such as formal or summary administration through the 17th Judicial Circuit Court in Broward County, local procedural rules govern how property titles are cleared and distributed.
An integrated estate plan accounts for these local court requirements ahead of time, minimizing administrative delays for real estate located in Coral Springs, Parkland, or Fort Lauderdale by ensuring property deeds and trust funding are properly structured before probate ever becomes necessary.
What happens if instructions in a revocable living trust contradict a financial account beneficiary form?
If a revocable living trust states that all liquid accounts should be divided equally among beneficiaries, but an individual retirement account or bank account lists a single person as a payable on death recipient, the financial institution is legally bound to honor the beneficiary form.
A comprehensive estate audit resolves these discrepancies proactively to prevent unintended disinheritances.
Coordinate Your Estate Plan in Broward County
The goal of estate planning is not to accumulate the largest stack of legal documents. It is to ensure that your ownership titles, beneficiary forms, trusts, and wills work together as a unified system to protect your family and assets.
Estate planning is the process of deciding how your property, financial affairs, and health care decisions should be handled during your lifetime, during periods of incapacity, and after your death.
For families in Coral Springs and throughout Broward County, an estate plan may include a will, revocable trust, durable power of attorney, health care surrogate designation, living will, preneed guardian designation, or other documents depending on the person’s circumstances.
There is no single set of documents that every person needs. The important question is whether the plan addresses the situations that could actually affect you and your family.
What Does an Estate Plan Actually Do?
A basic estate plan addresses two different periods of life.
During your lifetime, it can establish who may manage financial matters or make health care decisions if you become unable to make those decisions yourself.
After your death, it can determine who receives your property, who administers your estate, who manages assets held in trust, and how certain property should be transferred.
Those functions are handled by different documents. A will, for example, does not give someone authority to manage your finances while you are alive. A health care surrogate designation does not determine who inherits your house. A durable power of attorney does not replace a will.
Understanding those distinctions is one of the foundations of effective estate planning.
1. Last Will and Testament
A last will and testament allows you to state how certain property should be distributed after your death and nominate a personal representative to administer your estate.
A will can also address other matters, including the nomination of a guardian for minor children.
But there is an important misconception to avoid:
Having a will does not automatically avoid probate.
A will generally becomes effective through the probate process when it governs probate assets. Property may instead pass outside probate through mechanisms such as joint ownership, beneficiary designations, or a properly funded trust.
Recent Florida litigation illustrates how specific the probate process can become. In Property Solutions Powerhouse, LLC v. Nelson, decided by Florida’s Second District Court of Appeal in 2025, the court addressed a dispute involving a lost will, probate, notice to interested persons, and Florida homestead. The court ultimately upheld the administration and concluded that the decedent, who had no surviving spouse or children, could devise her homestead to the named beneficiary.
The case is a useful reminder that having a will does not mean every question about an estate is automatically settled. The validity of the will, the identity of interested persons, the nature of the property, and Florida’s homestead rules can all matter.
2. Revocable Living Trust
A revocable living trust allows a person to place assets into a trust during life and establish instructions for how those assets should be managed during incapacity and distributed after death.
The person creating the trust can generally retain control while capable and can name a successor trustee to take over management if necessary.
A revocable trust can also help keep properly funded trust assets outside ordinary probate administration. But the trust has to be properly funded. Simply signing a trust agreement does not automatically transfer every asset into it.
The trust is therefore only one part of an estate plan. Its effectiveness depends on how the document is structured, which assets are transferred to it, and how the rest of the estate plan is coordinated.
For a more detailed explanation, see What Is a Revocable Living Trust in Florida?
3. Durable Power of Attorney
A durable power of attorney allows you to authorize another person, called an agent, to act on your behalf within the authority granted by the document.
In Florida, a power of attorney is durable when it contains language showing that the authority continues despite the principal’s subsequent incapacity. Florida law also establishes specific execution requirements, including signing by the principal and two subscribing witnesses and acknowledgment before a notary in the circumstances specified by statute.
The scope of an agent’s authority depends on the powers granted in the document and Florida law.
This is why simply assuming that a spouse or adult child can handle everything for you can create problems. Ownership of a bank account or property does not automatically give another person authority to act on your behalf concerning assets or legal matters that belong to you individually.
A properly prepared power of attorney can be particularly important when someone becomes incapacitated and needs another person to handle financial or legal matters without waiting for a guardianship proceeding.
4. Health Care Surrogate Designation
A health care surrogate designation allows you to name someone to make health care decisions for you if you become unable to make those decisions yourself.
Florida law provides that a designated surrogate may have authority to make health care decisions during the principal’s incapacity, subject to the principal’s instructions and any limitations placed on the surrogate’s authority.
The designation is different from a living will.
A health care surrogate designation identifies who may make health care decisions.
A living will communicates your wishes concerning life prolonging procedures in specified medical circumstances.
Those documents can work together.
Florida law also provides a mechanism for judicial review when an interested person believes, among other things, that a surrogate’s decision conflicts with the patient’s known wishes, that the advance directive is ambiguous, or that the surrogate has abused their authority.
5. Living Will
A Florida living will allows a competent adult to state preferences concerning life prolonging procedures if the person later has a terminal condition, end stage condition, or is in a persistent vegetative state.
Florida law establishes specific execution requirements and provides that a properly executed living will creates a rebuttable presumption of clear and convincing evidence of the person’s wishes.
A living will therefore serves a different purpose from a health care surrogate designation.
The surrogate is the person who may make health care decisions within the authority granted.
The living will communicates your own instructions about life prolonging treatment in the circumstances covered by the document.
6. Preneed Guardian Designation
Florida law also allows a competent adult to name a preferred guardian in advance.
A preneed guardian designation is a written declaration naming the person the individual wants to serve as guardian if a court later determines that the individual is incapacitated. Florida law requires the declaration to be signed in the presence of at least two witnesses. If an incapacity proceeding is later filed, the declaration creates a rebuttable presumption that the designated person should serve, although the court is not required to appoint someone who is unqualified.
The distinction is important: a preneed guardian designation does not eliminate the possibility of a guardianship proceeding. Instead, it allows the individual to express a preference before incapacity occurs.
When Estate Planning Documents Have to Work Together
Estate planning documents are most useful when they form a coordinated plan rather than a collection of unrelated forms.
For example:
A will can address probate assets and nominate a personal representative.
A revocable trust can govern assets properly transferred to the trust.
A durable power of attorney can authorize an agent to handle financial and legal matters during incapacity.
A health care surrogate designation can identify someone to make health care decisions.
A living will can communicate wishes concerning life prolonging procedures.
A preneed guardian designation can identify a preferred guardian if a guardianship proceeding becomes necessary.
The documents can also interact with beneficiary designations, jointly owned property, retirement accounts, insurance policies, business interests, and real estate.
That is why changing one document without reviewing the rest of the plan can create unintended results.
A Florida Case Shows Why Advance Planning Matters
A recent Florida appellate decision provides an unusually clear example of how these documents can operate together.
InFrank v. Frank, decided by Florida’s Fourth District Court of Appeal in 2026, a woman had executed a durable power of attorney, health care surrogate designation, trust, and will before a guardianship dispute arose. The documents named her daughter, Alicia, to manage her affairs and established her intentions concerning the family home and estate.
The trial court later appointed a different person despite those prior designations. The Fourth District Court of Appeal reversed because the lower court had failed to make the specific findings required to overcome the statutory presumption supporting the woman’s previously expressed choice. The appellate court emphasized that the record showed she had repeatedly confirmed her estate planning decisions before the guardianship dispute.
The case does not mean that a person’s chosen agent or guardian can never be replaced. It demonstrates something more practical: advance planning can provide evidence of a person’s wishes before a family dispute reaches court.
An older Florida Fourth District case, Martinez v. The Guardianship of J. Alan Smith, similarly involved a person who had executed a health care surrogate designation, preneed guardian designation, and durable power of attorney before suffering a serious injury.
The appellate court reversed because the trial court had not made the required finding that the person’s chosen representative was contrary to the ward’s best interests.
What Happens If You Do Nothing?
If you die without a valid will, Florida’s intestacy laws determine who inherits property subject to those laws.
If you become incapacitated without appropriate planning, family members may have to rely on whatever legal mechanisms are available under the circumstances. A guardianship proceeding may become necessary for some decisions, although Florida law recognizes advance directives and other planning tools that can sometimes provide alternatives or affect the scope of a guardianship.
The important point is not that everyone needs every available document.
It is that leaving the decisions entirely to default legal rules may produce a result different from the one you would have chosen yourself.
Estate Planning After Marriage, Divorce, or Other Major Changes
An estate plan should not necessarily remain unchanged for decades.
A major life event may require a review of:
Your will
Revocable trust
Beneficiary designations
Durable power of attorney
Health care surrogate
Living will
Preneed guardian designation
Ownership of real estate
Retirement accounts
Life insurance
Business interests
Divorce is a particularly important example. Florida law contains rules affecting fiduciary appointments and certain estate planning documents after dissolution proceedings begin or a final judgment is entered. The Florida Bar has noted that durable powers of attorney and health care surrogate designations require particular attention during divorce planning.
A plan should also be reviewed when a beneficiary or fiduciary dies, a child reaches adulthood, substantial assets are acquired or sold, or the person’s family circumstances change.
“The best estate plan is one that makes the owner’s intentions clear before the family is forced to interpret them under pressure. A trust can provide that structure, but the document and the ownership of the assets need to work together.”
That principle applies beyond trusts. Estate planning works best when the documents, property ownership, beneficiary designations, and the person’s actual wishes are coordinated.
Common Estate Planning Questions
Do I need a will if I have a revocable living trust?
Often, yes. A will can serve purposes that a revocable trust does not, including addressing assets that were never transferred to the trust and nominating a personal representative or guardian where appropriate. The specific documents needed depend on the estate plan.
Does a will avoid probate in Florida?
No. A will generally directs the distribution of probate assets through the probate process. Some property may pass outside probate through trusts, beneficiary designations, joint ownership, or other mechanisms.
What is the difference between a living will and a health care surrogate?
A health care surrogate designation identifies someone who can make health care decisions within the authority granted when you cannot make them yourself. A living will communicates your wishes concerning life prolonging procedures in the circumstances covered by Florida law.
Does my spouse automatically have authority to manage everything if I become incapacitated?
Not necessarily. Marriage and joint ownership do not automatically give one spouse every legal authority that a properly executed power of attorney or health care designation can provide.
Can I choose who I want as my guardian?
Florida allows a competent adult to designate a preferred preneed guardian. The designation creates a rebuttable presumption in favor of the named person, but the court can decline to appoint someone who is unqualified or whose appointment is otherwise contrary to the applicable legal standard.
When should I review my estate plan?
Reviewing an estate plan after marriage, divorce, a death in the family, the birth or maturation of children, a major change in assets, a change in beneficiaries, or a significant change in your circumstances can help keep the plan consistent with your current wishes.
Estate Planning for Families in Coral Springs and Broward County
Estate planning is not limited to deciding who receives your property after death. For families in Coral Springs, Broward County, and surrounding South Florida communities, an effective plan can also address incapacity, health care decisions, financial management, real estate, beneficiary designations, trusts, and the administration of an estate.
The appropriate documents depend on the person’s family circumstances, property, financial affairs, and wishes.
A review of an existing plan can also be useful when the documents were prepared years ago or when major changes have occurred in the family or the assets involved.
When a married couple creates an estate plan, most of the attention naturally goes toward what happens after both spouses have died. But there is another moment that can be just as important: the death of the first spouse.
That event can change ownership of assets, activate provisions in a trust, affect beneficiary designations, create tax filing opportunities, and alter the plan the surviving spouse will eventually leave behind.
For families in Coral Springs and throughout Broward County, this is one reason an estate plan should be reviewed after a spouse dies. The documents may still be valid, but the circumstances they were designed to address have changed.
And that can make a surprisingly big difference under Florida law.
The First Death Is a Turning Point, Not the End of the Plan
An estate plan for a married couple is usually built around two different deaths.
The first death determines what happens to the deceased spouse’s property and what the surviving spouse receives or controls. The second death determines what ultimately passes to children, other beneficiaries, charities, or other intended recipients.
Those two events are connected.
For example, a couple may have arranged their assets so that the surviving spouse has financial security while certain property remains subject to a particular trust structure. Another couple may have arranged for most assets to pass directly to the surviving spouse.
Both plans can be legally sound. But they can produce very different results later.
The important question after the first death is therefore not simply, “Who inherited?”
It is:
“What did the first death activate, and what does the surviving spouse’s estate now look like?”
What Happens to the Assets After the First Spouse Dies?
The answer depends on how each asset was owned and how the estate plan directed it.
Some property may pass under a will. Some may pass according to a trust. Other assets may pass through beneficiary designations or forms of joint ownership.
This is why looking only at the will is rarely enough.
The surviving spouse and the estate’s attorney may need to review:
Real estate ownership
Bank and investment accounts
Retirement accounts
Life insurance
Business interests
Jointly owned property
Beneficiary designations
Trust assets
Debts and obligations
Prior gifts
Property that may be included in the deceased spouse’s taxable estate
The practical problem is that these pieces do not necessarily follow the same path.
A beneficiary designation can control an account without sending it through the will. A jointly owned asset can operate differently from separately owned property. A trust can contain instructions that become relevant immediately after death.
This is one reason the death of a spouse should trigger a full review of the estate plan in South Florida, rather than simply checking off the probate process and moving on.
The Estate Tax Question Begins With the First Death
Estate tax planning can become especially important when a married couple has substantial assets.
For deaths occurring in 2026, the federal basic exclusion amount is $15 million. (It is worth noting that Florida does not currently levy a state level estate tax). An estate generally must file Form 706 when the applicable federal filing threshold is exceeded. But there is another important reason to file: the executor can use Form 706 to elect portability of the deceased spouse’s unused exclusion for the surviving spouse.
That second point is easy to overlook.
Suppose one spouse dies with an estate substantially below the federal exclusion amount. It might appear that there is no reason to think about an estate tax return because no federal estate tax is due.
That conclusion can be premature.
A properly filed estate tax return can allow the surviving spouse to receive the deceased spouse’s deceased spousal unused exclusion amount, commonly called DSUE. The surviving spouse may then be able to use that amount against certain later taxable transfers during life or at death.
In other words, “No estate tax is due” and “there is nothing worth filing” are not necessarily the same thing.
What Is Portability?
Portability allows a deceased spouse’s unused federal estate tax exclusion to be transferred to the surviving spouse.
The surviving spouse does not receive the unused exclusion automatically. The deceased spouse’s estate must make the portability election through a properly prepared Form 706.
That deadline is one of the reasons the issue deserves attention soon after the first spouse dies.
The family may be dealing with grief, probate, property transfers, insurance claims, financial accounts, and a long list of practical problems. The tax filing may feel like something that can wait.
Sometimes it cannot.
Why the Surviving Spouse’s Future Estate Matters
Imagine a married couple with substantial assets.
The first spouse dies. Most of the property passes to the surviving spouse, who continues living in the family home, maintains the investment portfolio, and eventually receives additional assets.
Years later, the surviving spouse dies.
At that point, the estate is measured again.
The surviving spouse’s estate may look very different from the estate that existed at the first death. Investments may have appreciated. Real estate may have increased substantially in value. Retirement accounts may have changed. The surviving spouse may have received additional property or made significant gifts.
That means the planning opportunity at the first death can have consequences years later.
“The surviving spouse should not assume that the estate plan is finished simply because the first estate was administered. The first death can change the legal and financial circumstances that the original plan was built around.”
That review does not necessarily mean rewriting everything.
It means determining whether the structure still accomplishes what the couple originally intended.
Does a Trust Automatically Save Estate Taxes?
No.
This is an important distinction because older estate planning materials sometimes make trusts sound like tax saving machines.
A revocable living trust can be an important part of an estate plan, but simply placing assets in a revocable trust does not automatically eliminate federal estate tax.
The tax consequences depend on the actual structure, ownership, applicable exclusions, elections, deductions, beneficiary arrangements, and the circumstances surrounding the transfer.
The more useful question is therefore:
How does the trust operate after the first spouse dies, and what does that structure accomplish?
In some estate plans, trust provisions may help determine who controls property, who benefits from it, and how it is treated after the first death. In others, assets may pass directly to the surviving spouse.
The answer depends on the plan.
That is why copying a trust structure from another family is a particularly bad form of estate planning.
When the First Death Changes the Tax Strategy
A married couple may have several potential ways to structure property at the first death.
One approach may leave property directly to the surviving spouse. The federal marital deduction can generally allow qualifying property passing to a surviving U.S. citizen spouse to be deducted from the deceased spouse’s gross estate.
That can defer estate tax rather than necessarily eliminate it.
Other arrangements can involve trusts or other structures designed to address control, beneficiary protection, tax planning, or a combination of these concerns.
The appropriate structure depends on the family’s circumstances.
For example, a couple with a relatively straightforward estate may have different concerns from a couple who owns several properties, a closely held business, significant investments, or substantial assets expected to appreciate.
Alan Reinfeld explains the practical point this way:
“The first spouse’s death is often the moment when the surviving spouse’s estate plan needs to be reconsidered. The plan was created for two people. After one dies, it is a plan for one.”
That is especially important when the family’s wealth is likely to change substantially over time.
Case Study: When “Everything Went to My Spouse” Was Not the Whole Story
Consider a hypothetical couple living in Coral Springs, Michael and Laura.
They own their home, investment accounts, several retirement accounts, and other assets with a combined value of approximately $10 million.
Michael dies first.
The immediate result appears simple. Laura receives the property intended for her, the family home remains in her hands, and there is no federal estate tax bill because the estate is below the 2026 $15 million basic exclusion amount.
The family assumes the tax issue is finished.
But Laura’s attorney asks a different question:
Was portability elected?
Michael’s estate may have had unused federal exclusion available for Laura. If the executor makes the appropriate election, that unused amount may become available to Laura for later taxable transfers.
Now consider what happens over the next decade.
Laura’s investments appreciate. She sells one property and reinvests the proceeds. The family home increases substantially in value. She also receives additional assets.
By the time Laura dies, her estate is considerably larger than the estate Michael left behind.
The first death did not produce an immediate estate tax problem. But decisions made at that time could still affect the tax position of Laura’s eventual estate.
The lesson is not that every couple needs a complicated trust structure.
The lesson is that the first death can create decisions whose consequences will not become visible until years later.
What Should the Surviving Spouse Review?
After the first spouse dies, a surviving spouse should consider reviewing at least the following:
How each asset passed: Determine which assets passed through a will, trust, beneficiary designation, joint ownership, or another mechanism.
Whether an estate tax return should be filed: Even when no estate tax is immediately owed, filing may be important if the estate wants to elect portability.
Whether portability was elected: If the surviving spouse may benefit from the deceased spouse’s unused exclusion, confirm whether the election was made and whether the return was properly prepared.
The surviving spouse’s new asset picture: The surviving spouse may now own or control assets that were previously divided between two estates.
Future appreciation: An asset’s value today is not necessarily the value that will matter at the surviving spouse’s death.
Beneficiary designations: Retirement accounts, insurance policies, and other accounts should be reviewed to determine whether their beneficiary designations still reflect the family’s intentions.
Trust provisions: If a trust was involved, determine what happened to the trust at the first death and what rights and obligations now apply.
The surviving spouse’s own estate plan: The surviving spouse is now the person whose eventual estate plan will determine what happens to the remaining assets.
That last step is often overlooked.
The estate plan should evolve because the family has changed.
What If the Surviving Spouse Remarries?
Remarriage can introduce another layer of planning.
Federal portability rules contain a last deceased spouse limitation. Generally, a surviving spouse’s DSUE amount is tied to the spouse who was most recently deceased at the relevant time. The IRS rules also address how remarriage can affect the use of a previously received DSUE amount.
That means remarriage should prompt another estate planning review.
The same is true if the surviving spouse:
Has additional children
Changes beneficiaries
Acquires or sells major assets
Starts or sells a business
Makes significant gifts
Moves assets into different ownership structures
Experiences a major change in financial circumstances
Estate plans have a bad habit of becoming outdated quietly.
What If Nobody Thought About Portability?
There is a useful safety net, but it should not become the planning strategy.
For certain estates that were not otherwise required to file Form 706, IRS procedures provide a simplified method for making a late portability election. Under Revenue Procedure 2022-32, qualifying estates can generally use the procedure by filing a complete Form 706 on or before the fifth anniversary of the decedent’s death.
That does not mean families should wait.
Eligibility requirements matter, and estates that were already required to file a return can face different rules concerning the deadline.
The practical lesson is simple: if the first spouse died without a portability election being considered, ask about it rather than assuming the opportunity is gone.
The First Death Should Trigger a Review, Not a Filing Frenzy
Estate administration can involve a remarkable amount of paperwork.
That does not mean every surviving spouse needs to rebuild an entire estate plan immediately.
The better approach is to identify what changed first.
What assets moved? Have assets remained in trust? What tax elections are available? Do deadlines apply? What does the surviving spouse now own? What will eventually pass from the surviving spouse’s estate?
Once those questions are answered, the family can determine whether the existing plan still makes sense.
For families in Coral Springs, Broward County, and throughout South Florida, an attorney can help review the documents, asset ownership, tax filings, and beneficiary arrangements together rather than treating each document as an isolated problem.
Because the first spouse’s death may be the point where the estate plan changes from a two person plan into a one person plan.
And that is a pretty important change to leave sitting in a filing cabinet.
Frequently Asked Questions
Could a spouse automatically receive the deceased spouse’s unused estate tax exemption?
No. Portability generally requires the deceased spouse’s estate to make an election by filing Form 706. The surviving spouse may then be able to use the deceased spouse’s unused exclusion amount against certain later taxable transfers.
Does an estate tax return have to be filed if no estate tax is owed?
Not necessarily. For a 2026 death, the normal federal filing threshold is $15 million for a U.S. citizen or resident decedent, subject to applicable rules. However, Form 706 may also be filed to elect portability, even when the estate is below that threshold.
Does Florida have a state level estate tax when a spouse dies?
No. Florida does not currently impose a state estate tax or inheritance tax. Estate tax planning for families in Coral Springs and Broward County focuses entirely on federal estate tax rules, portability elections, and asset management structures.
How long does a family have to elect portability?
The normal federal deadline is nine months after death, with a possible six month extension. Certain estates that were not otherwise required to file may qualify for a simplified late election procedure within five years of the decedent’s death.
Does a living trust automatically reduce estate taxes?
No. A revocable living trust does not automatically eliminate federal estate tax. The tax consequences depend on how the assets, trust provisions, elections, deductions, and other parts of the estate plan interact.
Should the surviving spouse change the estate plan immediately?
Not necessarily. The first priority is understanding what changed after the death and identifying any deadlines or tax elections. Once the surviving spouse’s new financial and legal position is clear, the estate plan can be reviewed and changed where appropriate.
What happens to the surviving spouse’s estate when that spouse later dies?
The surviving spouse’s estate is evaluated based on the assets and applicable tax rules at that later death. The value of assets may have changed significantly since the first spouse died, which is one reason planning decisions made after the first death can have long term consequences.
Can a surviving spouse lose the benefit of a deceased spouse’s unused exclusion?
The rules are technical. Portability, later taxable transfers, and the identity of the surviving spouse’s last deceased spouse can all matter. Remarriage can also affect the use of a previously received DSUE amount.
Schedule a Consultation with Our Coral Springs Estate Planning Attorneys
If you are navigating the administration of an estate after the death of a spouse in Coral Springs, Broward County, or anywhere in South Florida, you do not have to sort through asset titles, tax elections, and trust provisions alone.
Preplanning your final arrangements is one of the most effective ways to lift an emotional and financial burden from your family. Documenting your wishes ensures that your funeral or cremation is handled according to your exact preferences. And without forcing grieving relatives to guess or overspend.
However, moving from preplanning (recording your wishes) to prepaying (funding those arrangements through a preneed contract) introduces complex financial and legal regulations.
For seniors and families in Coral Springs and throughout Broward County, navigating Florida’s preneed laws requires careful oversight. Without proper legal structuring, prepaying can expose your money to provider insolvency. It can also create inflexibility if you relocate, or unintended tax and Medicaid complications.
The Critical Legal Distinction: Preplanning vs. Preneed Contracts
Under Florida law, terminology matters significantly:
Preplanning (Preneed without funds): This is simply documenting your choices. Things as casket types, service locations, and disposition preferences—with a licensed funeral home, with zero money changing hands upfront.
Preneed Contract: This is a legally binding agreement where you pay for goods and services in advance.
Under Florida Statutes Chapter 497, preneed contracts are heavily regulated to protect consumers. But the specific funding mechanism dictates how secure your money actually is.
How Florida Law Protects (and Exposes) Your Prepaid Funds
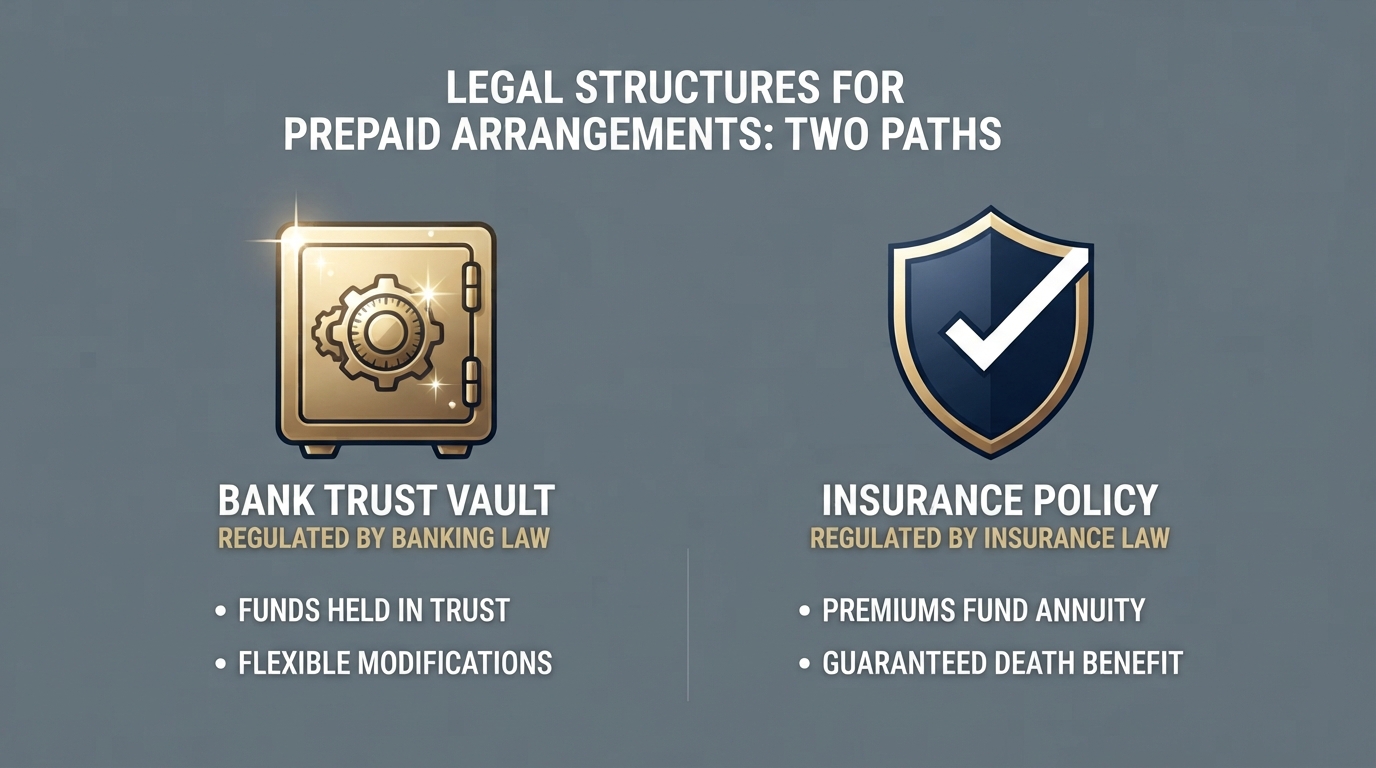
When you purchase a preneed contract from a licensed funeral home in Florida, the provider must handle your money using one of two primary statutory methods:
Under a trust arrangement, a portion of your payment (at least 70% of the service portion and specific percentages for merchandise) must be deposited into an independent trust. It should be managed by a financial institution, not kept in the funeral home’s operating account.
The Risk: Legally, trust-funded monies can leave the purchaser or their estate treated as an unsecured creditor. Especially if the funeral home faces financial distress or closes down.
2. Life-Insurance-Funded Preplans
An alternative approach involves funding the preneed agreement through a specialized final expense. Another option can be a whole life insurance policy where the funeral home is named as the beneficiary upon death.
Preneed Contracts and Medicaid Planning in South Florida
For many older adults in Broward County, preplanning intersects directly with Medicaid long-term care planning.
To qualify for Medicaid, applicants must meet strict asset limits (typically $2,000 for an individual). Florida law permits individuals to prepay funeral and burial expenses to reduce countable assets legally.
However, to count as an exempt asset for Medicaid purposes, a preneed funeral contract must be irrevocable.
The Trade-Off: Making a contract irrevocable means you permanently surrender the right to cash it out or change your mind for a refund.
The Legal Role: An experienced elder law attorney ensures that irrevocable burial trusts or preneed contracts are structured precisely to satisfy Department of Children and Families (DCF) guidelines without triggering unintended penalties.
Key Protections Every Consumer Must Demand
Before signing any preneed agreement or paying a funeral home in advance, protect your interests by verifying these statutory requirements:
Insist on the General Price List (GPL): Federal Trade Commission (FTC) rules and Florida law require providers to give you itemized price lists before you commit.
Review Portability Terms: If you move out of South Florida or wish to switch providers later, check whether your contract can be transferred cleanly without severe financial penalties.
Understand the Cancellation Window: Florida law provides a statutory right to cancel a preneed contract within 30 days of execution for a full refund. After that, cancellation terms depend strictly on whether the contract is revocable or irrevocable.
Get Price Guarantees in Writing: Ensure the contract specifies whether it is a “guaranteed” plan (meaning no additional out-of-pocket costs for your family at the time of death for the items listed) or a non-guaranteed plan that leaves families exposed to inflation gaps.
Frequently Asked Questions
Can I get my money back if I prepay my funeral in Florida?
If your preneed contract is revocable, you may cancel it, though refunds are subject to statutory formulas and trust rules under Chapter 497. If the contract was made irrevocable for Medicaid planning purposes, it cannot be canceled or refunded.
What happens if my prepaid funeral home goes out of business?
Florida maintains the Preneed Funeral Contract Consumer Protection Trust Fund to provide a safety net and claims process for consumers if a licensed preneed seller fails or closes. Working with an established, financially stable provider minimizes this risk.
Is there a limit to how much I can prepay for burial arrangements under Medicaid?
While Medicaid allows unlimited pre-funding through properly structured irrevocable preneed burial contracts, separate designated burial cash accounts are typically capped at $2,500. Every dollar must comply strictly with Florida Medicaid asset rules.
Can a preneed funeral plan be transferred to another funeral home?
It depends on the funding mechanism. Insurance-funded plans are often portable nationwide, whereas trust-funded contracts tied to a specific local funeral home can involve transfer hurdles or administrative fees.
Schedule a Consultation with Our Coral Springs Elder Law Attorneys
Integrating funeral preplanning into a comprehensive estate or Medicaid plan requires balancing emotional peace of mind with strict financial protection.
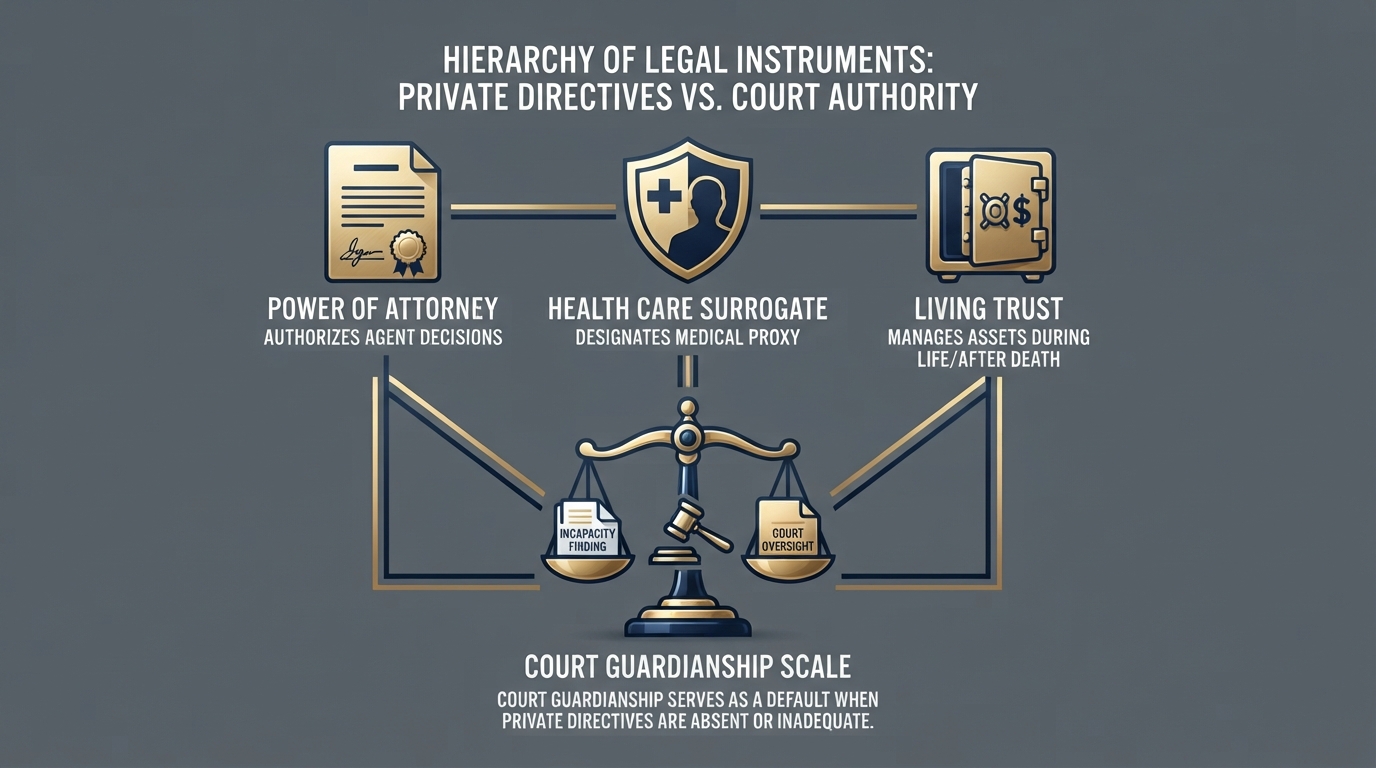
Under Florida Statutes Section 744.2005, a court is legally prohibited from appointing a guardian if any less restrictive alternative, such as a valid Durable Power of Attorney, Health Care Surrogate, or Living Trust, can adequately protect the individual. If a family petitions for guardianship without proving those alternatives failed or were impossible, the 17th Judicial Circuit can dismiss the case.
When an aging parent, spouse, or adult relative begins showing signs of cognitive decline, severe memory loss, or an inability to manage daily affairs, families frequently experience an immediate sense of panic. In Broward County, people often rush to court looking to file an emergency petition for guardianship to secure total legal control.
However, Florida guardianship law is built on a rigid legislative principle. Guardianship is an absolute measure of last resort, not a first response.
Understanding how courts evaluate these petitions ensures families pursue the right legal mechanism from the start, avoiding costly court dismissals.
The Statutory Mandate of Least Restrictive Alternatives
Before a Broward County probate judge will enter an order determining incapacity and appointing a guardian of the person or property, the petitioner carries the burden of proving by clear and convincing evidence that no lesser alternative is viable.
The Florida Legislature enacted these protections specifically to prevent unnecessary intrusions on personal liberty. Under Chapter 744, courts must actively explore whether the individual previously executed documents. They also see for established arrangements that render a court-supervised guardianship unnecessary.
These legally recognized alternatives include:
Durable Powers of Attorney (F.S. Chapter 709): A properly drafted and executed financial power of attorney allows a designated agent to handle banking. He can also manage real estate, and financial transactions without court intervention.
Designated Health Care Surrogates: Medical and end-of-life decisions can be governed by a designated surrogate under a health care proxy rather than a court-appointed guardian.
Revocable Living Trusts: Assets placed into a trust are managed seamlessly by a successor trustee upon the grantor’s incapacity. Therefore bypassing court oversight entirely.
Representative Payeeship: Administrative mechanisms through agencies like the Social Security Administration to manage specific benefit funds.
If an individual signed these instruments while they still possessed legal capacity, a court will generally reject a guardianship petition because a less restrictive legal structure is already functioning.
Why Existing Documents Fail: The Real-World Exception
Florida law strictly favors less restrictive alternatives. But real-world family dynamics in South Florida frequently create breakdowns that render those alternatives useless.
A primary reason guardianship petitions succeed – even when a power of attorney or trust exists – is that unresolvable family conflict or agent misconduct paralyzes the instrument. Common scenarios include:
Conflicting Agents: If a parent named co-agents who are actively fighting, locking accounts, or countermanding each other’s medical decisions, the power of attorney becomes gridlocked.
Financial Exploitation: When an agent abuses their fiduciary duty, drains accounts, or acts against the principal’s best interests, the court must intervene to suspend the power of attorney and appoint an independent guardian.
Total Lack of Prior Planning: If an individual suffered a sudden stroke or advanced dementia before executing any estate planning documents, no alternative exists, making a formal court guardianship the only viable path.
In these contentious cases, guardianship becomes legally necessary. And precisely because informal or delegated tools have broken down under the weight of dispute or abuse.
The Broward County Examining Committee Process
If a guardianship petition moves forward in the 17th Judicial Circuit, the court appoints an Examining Committee to evaluate the alleged incapacitated person. This committee typically consists of three professionals: a psychiatrist or physician, a psychologist or gerontologist, and a layperson or attorney.
The committee’s statutory role is rigorous:
Each member conducts an independent physical, mental, and functional evaluation and files a formal report with the court.
If a majority of the examining committee concludes that the individual is not incapacitated in the specific areas evaluated, Florida law mandates the immediate dismissal of the petition.
Families cannot override the medical and psychological findings simply out of frustration or disagreement over lifestyle choices.
Strategic Steps Before Filing in South Florida
Jumping straight to the courthouse without conducting a comprehensive legal audit is an expensive gamble. Before filing for guardianship in Broward County, experienced counsel evaluates:
The Vault Check: Determining whether an unexecuted or forgotten durable power of attorney, health care surrogate, or trust exists.
Capacity Timeline: Analyzing whether the individual had legal capacity when current documents were signed, or if those documents are legally vulnerable to undue influence challenges.
Alternative Remedies: Weighing whether an injunction, a trust accounting lawsuit, or a revocation of agency under F.S. 709 can resolve the dispute faster and with less financial drain than a full incapacity proceeding.
Frequently Asked Questions
What is the difference between a “limited” guardianship and a “plenary” guardianship in Florida?
Under Florida law, courts favor limited guardianships whenever an individual lacks capacity in certain specific areas (such as managing real estate or complex investments) but retains the ability to make sound decisions in others (such as medical choices or daily living). A plenary guardianship is a full, blanket appointment where the court removes all delegable rights of the individual.
Can a person contest a guardianship petition filed against them?
Yes. An alleged incapacitated person has an absolute right to be represented by independent legal counsel of their own choosing in Florida. If they cannot afford an attorney, the court will appoint court-appointed counsel to advocate for their rights throughout the proceedings.
What is a “Preneed Guardian” designation under Florida law?
A preneed guardian is a legal document where a competent adult names who they want to act as their guardian if they ever become incapacitated in the future. Florida courts are legally required to give great weight to this prior written preference, avoiding family battles over who should take charge.
How long does a guardianship proceeding take in the 17th Judicial Circuit?
Timelines vary based on court docket congestion, whether the petition is contested by family members, and the scheduling of the examining committee. Contested guardianship litigation can take several months or longer to resolve.
Schedule a Consultation with Our Coral Springs Elder Law Attorneys
Navigating incapacity, family disputes, and court oversight in Coral Springs, Broward County, or South Florida requires precise legal navigation.
Finding a divorce attorney is rarely something people put on their calendar because they have nothing better to do. Usually, something has happened. A marriage has reached a point where staying together no longer seems workable, a spouse has already filed, or a conversation about property, money, or children has suddenly become a legal question.
If you are looking for a divorce attorney in Coral Springs, online reviews can be a useful place to begin. They can tell you something about how previous clients experienced an attorney’s communication, responsiveness, and representation. A strong reputation matters. So does looking more closely at the attorney’s experience, familiarity with Broward County family courts, and experience with cases resembling your own.
The goal is not to find a lawyer who sounds impressive in an advertisement. It is to find someone whose experience makes sense for the situation that brought you to the search in the first place.
How Do I Choose a Divorce Attorney in Coral Springs?
Start with your circumstances.
A divorce involving a house, retirement accounts, a business, substantial income, or disputed parenting arrangements can raise very different questions from an uncontested dissolution in which both spouses have already agreed on the major issues.
Sometimes the central problem is financial. Others it is the children. Sometimes the spouses agree about almost everything except one issue that has become impossible to resolve. And sometimes the person searching for an attorney is not even sure yet what the other spouse intends to do.
Those differences matter when choosing counsel
An attorney who regularly handles cases involving substantial marital assets may approach your situation differently from someone whose practice consists primarily of straightforward uncontested divorces. Experience with parenting disputes, alimony, business interests, or complex property division can matter for the same reason.
Florida law also imposes specific requirements on dissolution proceedings. At least one spouse, for example, must have resided in Florida for six months before the petition is filed.
That part is relatively straightforward. The questions that follow can be considerably more complicated.
“Choosing a divorce attorney is about more than finding someone who handles family law. You want someone who understands the particular problems your case may present and can explain your options clearly before important decisions are made.”
If your divorce is being handled in Broward County, your attorney will be working within the Seventeenth Judicial Circuit of Florida. Its Family Division handles dissolution of marriage along with matters involving parenting, support, alimony, paternity, and other family law proceedings.
There is a practical difference between knowing that a court exists and regularly practicing within its system.
An attorney familiar with Broward County family law will encounter the local procedures, filing requirements, mediation process, scheduling issues, and courtroom practices that shape how cases move forward. That experience does not guarantee a particular result, but it can make a meaningful difference in how a case is prepared and managed.
The Seventeenth Judicial Circuit also provides family mediation services in appropriate cases. Divorce does not always have to end with a trial, and knowing when negotiation or mediation is productive can be just as important as knowing how to litigate when an agreement cannot be reached.
What Should I Ask a Divorce Attorney?
The first consultation is where the search becomes much more concrete.
You may already know the basic facts of your situation. You may also arrive with a much longer list of questions: What happens to the house? What about the children? Can my spouse take money from our accounts? How does alimony work? What happens if we cannot agree?
The Florida Bar recommends discussing an attorney’s experience, fees, communication practices, and the work the case is likely to require before hiring counsel.
That does not mean you need to arrive with a perfectly organized questionnaire.
Explain what has happened. Bring the information you have. Then see how the attorney approaches the problems in front of you.
Does the attorney identify issues you had not considered? Are complicated legal questions explained in language you can actually follow? Does the attorney tell you when something is uncertain rather than pretending every case has an easy answer?
It is also reasonable to ask who will handle the day-to-day work, how you will communicate with the firm, how billing works, and what additional costs you should expect.
A consultation should leave you with a better understanding of your situation than you had when you walked in.
How Much Does a Divorce Attorney Cost in Florida?
There is no universal price for a Florida divorce because there is no universal Florida divorce.
An uncontested matter may be handled for a fixed fee. A contested case involving extensive discovery, financial issues, parenting disputes, hearings, or trial preparation can require considerably more legal work and may involve hourly billing or another fee arrangement.
The Florida Bar notes that the total cost of a contested divorce can be difficult to predict in advance because the amount of work depends on how the case develops.
Florida also does not permit contingency fees for obtaining a divorce or for compensation based on alimony, support, or a property settlement.
The useful question, therefore, is not simply “How much does a divorce cost?”
Ask what the attorney’s fee covers, how the attorney bills, what expenses are separate, and what circumstances could cause the cost of the case to change.
A clear conversation about fees at the beginning is much better than discovering halfway through a case that you and your attorney had very different ideas about what the original estimate meant.
Should You Consider Online Reviews When Choosing a Divorce Attorney?
Yes.
Online reviews cannot tell you everything about a lawyer, but they can provide valuable insight into the experience of people who have actually worked with the firm.
Pay attention to recurring themes. Do clients describe the attorney as responsive? Have they mentioned clear explanations? Do they describe the firm as attentive during a difficult process? A consistent pattern across many reviews can tell you something that a professional biography cannot.
At the same time, reviews are most useful when considered alongside the attorney’s qualifications and experience.
A person who went through an uncontested divorce may have had a very different legal experience from someone involved in a contested dispute over property, parenting, or support. The point is not to discount either experience. It is to understand what the reviews are telling you.
Credentials deserve attention as well.
Florida offers board certification in Marital and Family Law. Among other requirements, certification requires at least five years of law practice, substantial involvement in marital and family law, and experience handling at least 25 contested marital and family law cases, including at least seven trials.
Board certification is one credential. Experience, reputation, communication, and the way an attorney actually handles a client’s case matter too.
What Should You Look for in a Divorce Attorney?
By the time you have narrowed your choices, the comparison becomes fairly straightforward:
What to consider
What to find out
Experience
Has the attorney handled cases resembling yours?
Reputation
What do previous clients consistently say about the firm?
Local practice
Does the attorney regularly work in Broward County?
Communication
Will you understand what is happening as the case develops?
Fees
Is the billing arrangement clear from the beginning?
Approach
Can the attorney negotiate when appropriate and litigate when necessary?
Credentials
Can the attorney’s qualifications be independently verified?
You may find several attorneys who look good on paper. That is a good problem to have.
At that point, the decision often comes down to a combination of experience, reputation, communication, and your own sense of whether you trust the attorney to handle what lies ahead.
When Should You Hire a Divorce Attorney?
People sometimes wait because they are hoping the situation will settle down.
Sometimes it does.
Other times, important decisions are being made during that period about money, property, living arrangements, or children. An informal agreement between spouses can also become much more consequential once one of the parties decides to file.
If you are seriously considering divorce, have been served with papers, are negotiating an agreement, or have been asked to sign something involving your marriage or property, obtaining legal advice before taking the next step can be valuable.
It can also help before the situation becomes openly adversarial.
And hiring a divorce attorney does not mean that your case is destined for a courtroom. Negotiation and mediation can resolve many disputes. Litigation remains important when the parties cannot reach a fair or workable agreement.
The important thing is having counsel who understands the difference.
“A divorce can change much more than a marital status. It can affect property, taxes, estate plans, and the way assets are ultimately passed to a family. The right legal advice should take that larger picture into account.”
Stuart Reinfeld, Reinfeld & Cabrera P.A. Draft quote for attorney approval.
Divorce Attorneys in Coral Springs and Broward County
Perhaps you have already started searching for a divorce attorney and found yourself with a long list of names.
At some point, the search needs to become more personal.
Who has handled cases like yours? Does he have a reputation you can verify? Who practices regularly in the court where your case will be heard? Who takes the time to explain the situation rather than rushing through the consultation?
And perhaps most importantly, who do you feel comfortable trusting with information about your marriage, finances, children, and future?
Reinfeld & Cabrera P.A. represents clients in Coral Springs and throughout Broward County in divorce and other family law matters. The firm brings local experience to cases involving the issues that can make divorce legally and personally complicated.
If you are considering divorce or already facing a family law dispute, contact Reinfeld & Cabrera to discuss your circumstances and the legal options available to you.
Frequently Asked Questions
How do I choose a divorce attorney in Coral Springs?
Look at experience, reputation, local practice, communication, fees, and the attorney’s experience with cases similar to yours. A consultation is often the best way to determine whether the attorney is a good fit for your circumstances.
Does my divorce attorney need to practice in Broward County?
There is no general requirement that your attorney maintain an office in Broward County. However, familiarity with the Seventeenth Judicial Circuit and its Family Division can be useful when your case is being handled there.
How much does a divorce attorney cost in Florida?
The cost depends on the circumstances of the divorce and the attorney’s fee arrangement. Uncontested matters may involve a fixed fee, while contested cases can require substantially more legal work. Discuss fees and anticipated costs before hiring an attorney.
Should I hire a divorce attorney before filing?
It can be useful to obtain legal advice before filing, particularly when property, children, support, business interests, or other significant issues are involved. Early advice can help you understand your legal position before important decisions are made.
Are online reviews useful when choosing a divorce attorney?
Yes. Reviews can provide useful information about previous clients’ experiences with a firm. They are most helpful when considered alongside the attorney’s experience, qualifications, local practice, and the specific circumstances of your case.
Talk With a Coral Springs Divorce Attorney
A divorce attorney is going to become involved in some of the most personal and consequential decisions you have made in years. The choice deserves more thought than picking the first name that appears in a search result.
Look at the firm’s reputation. Look at its experience. Read what former clients have to say. Then sit down with the attorney and see how they approach the problems you are actually facing.
Most people think of an estate plan as a set of documents: a will, perhaps a trust, powers of attorney, and other papers kept somewhere safe.
But there is another part of estate planning that matters just as much: how each asset is actually owned and what happens to it when you die.
A bank account can pass directly to a named beneficiary. A retirement account can do the same. Property owned with rights of survivorship may pass to the surviving owner. Assets properly transferred to a revocable trust can pass through the trust rather than through probate.
Other property may still become part of the probate estate.
So avoiding probate is not usually about finding one document or legal trick that makes the entire estate disappear from court supervision. It is about deciding, asset by asset, how ownership should change when you die.
Probate Is Not One Destination for Everything You Own
Imagine someone dies owning a house, a checking account, a retirement account, an investment account, and a life insurance policy.
It would be easy to think of all of these as “the estate” and assume they follow the same process.
They do not.
The legal mechanism attached to each asset can determine what happens next.
Asset or arrangement
Possible transfer mechanism
May avoid probate?
Main consideration
Life insurance with beneficiary
Beneficiary designation
Yes
Keep the designation current
Retirement account
Beneficiary designation
Yes
The account designation matters
Bank account with POD designation
Pay on death designation
Yes
Florida law governs the transfer
Securities registered in beneficiary form
Transfer on death registration
Yes
Registration must comply with applicable requirements
Joint property with survivorship
Survivorship rights
Yes
The form of ownership matters
Properly funded revocable trust
Trust administration
Yes
Assets must actually be transferred to the trust
Solely owned property without another mechanism
Probate administration
Generally no
Probate may be required
Florida homestead
Special rules
Depends
Family and ownership circumstances matter
Florida law specifically provides for pay on death accounts and allows qualifying securities registered in beneficiary form to pass to surviving beneficiaries rather than becoming part of the deceased owner’s estate.
That is why estate planning is better understood as a system of ownership and transfer than simply a collection of documents.
Start With the Asset, Not the Will
A will is important, but it does not necessarily control every asset you own.
If a retirement account names a beneficiary, that designation can determine who receives it. A valid pay on death designation can cause funds in a qualifying account to pass directly to the surviving beneficiary. Securities registered in beneficiary form can likewise pass according to that registration.
The more useful question is therefore:
Does the way this asset is titled or designated actually match the estate plan?
A will can say one thing while an outdated beneficiary designation says another.
Marriage, divorce, the birth of children, the death of a beneficiary, remarriage, or a major change in financial circumstances can all be reasons to review these arrangements.
Beneficiary Designations: Simple, but Worth Reviewing
Beneficiary designations are among the most straightforward ways to arrange for certain assets to pass outside probate.
Florida’s pay on death statute covers deposit accounts including checking accounts, savings accounts, certificates of deposit, and similar accounts. When the relevant account owner dies, the funds generally pass according to the valid designation.
Florida also has a separate statutory system for securities registered in beneficiary form. Under §711.507, ownership passes to beneficiaries who survive the owner or owners, subject to the statutory requirements.
Similar arrangements are common with:
Life insurance
Retirement accounts
Annuities
Certain investment accounts
Pay on death bank accounts
The important word is designation.
An estate plan may have been carefully prepared years ago, but the financial institution generally follows the designation governing the account or policy.
That makes beneficiary review an important part of estate planning.
A Revocable Trust Can Avoid Probate, but It Has to Be Funded
A revocable living trust is one of the best-known probate avoidance tools.
During the owner’s lifetime, assets are transferred to the trust and managed by the trustee. After death, the successor trustee can administer trust property without requiring a probate appointment for those particular assets.
But signing the trust is only part of the process.
The Florida Bar puts it plainly: “The ‘funding’ of a revocable trust is critical to successfully avoid probate.”
A trust document does not automatically place every asset you own into the trust.
If assets remain titled solely in the deceased person’s name, those assets may still require probate. The Florida Bar notes that an incompletely funded trust can result in both probate administration for assets outside the trust and trust administration for assets held by the trust.
The documents and the ownership records therefore need to agree.
Joint Ownership Can Avoid Probate. It Can Also Change Your Rights Now.
Joint ownership with survivorship rights can allow property to pass automatically to the surviving owner.
That can be useful. It is also more consequential than simply naming someone as a beneficiary.
Adding another person as a joint owner can give that person legal rights during your lifetime. Depending on the asset and ownership arrangement, joint ownership can also create complications involving creditors, taxes, estate expenses, simultaneous deaths, or unequal treatment among heirs.
The Florida Bar warns that joint ownership can sometimes “cause more problems than it solves.”
The point is not that joint ownership is inherently problematic. It is that avoiding probate should not be the only consideration when deciding who should own an asset.
“People often think avoiding probate requires something complicated. In many cases, it starts with a few simple decisions about how your property is owned and who should receive it. A little planning can make things much easier for the people you leave behind.”
Florida Homestead Is Different
A Florida home deserves special attention because homestead does not always follow the same rules as an ordinary investment account.
Florida law establishes specific rules governing the descent of homestead. When a decedent is survived by a spouse and descendants, for example, §732.401 provides for a life estate in the surviving spouse with a vested remainder in the descendants, while also giving the spouse an option to elect an undivided one-half interest instead. That election generally must be made within six months and is irrevocable.
The statute also expressly excludes certain property owned as tenancy by the entireties or joint tenancy with rights of survivorship from its operation.
Florida also has separate rules governing lifetime transfers of homestead, including transfers involving trusts.
In other words, the family home should not simply be treated as another asset on a generic probate avoidance checklist.
Giving Property Away Is Not the Same as Avoiding Probate
The simplest version of this strategy is also the most misleading: give property away before you die and it cannot enter your probate estate.
Technically, transferring ownership during life can accomplish that.
But it also means giving up ownership during life.
That can affect control over the property, creditors, taxes, family relationships, eligibility for certain benefits, and what happens if the recipient later dies, divorces, becomes incapacitated, or experiences financial problems.
Sometimes a lifetime gift makes sense. Sometimes another estate planning mechanism accomplishes the intended result without transferring ownership immediately.
“Avoids probate” is therefore not enough reason, by itself, to give something away.
The Real Problem: When the Plan and the Assets Disagree
Consider an estate with:
A house titled individually
A retirement account naming a former spouse
A bank account with a current beneficiary
An investment account owned jointly with one child
A revocable trust that was signed but never funded
A will dividing the estate equally among three children
The documents may all look reasonable in isolation.
Together, they could produce a very different result.
The former spouse may still receive the retirement account. The joint account may pass to one child. The bank account may pass to another beneficiary. The unfunded trust may not control the assets its creator expected it to control. The house may require a separate analysis because of Florida’s homestead rules.
The will may ultimately govern only the property that remains subject to probate.
This is why estate planning is not simply a question of:
“Do I have a will?”
It is also:
“Do my assets actually pass the way I think they will?”
A Practical Probate Avoidance Review
A useful review begins with the assets themselves.
For each significant asset, ask:
Who owns it now?
How is it titled?
Does it have a beneficiary designation?
Does it have survivorship rights?
Is it owned by a trust?
What happens if the named beneficiary dies first?
Does the arrangement conflict with the will or trust?
Are there special Florida rules governing the asset?
That review can reveal that an estate plan needs only a few updates.
It can also reveal several different transfer mechanisms working against one another.
Avoiding Probate Does Not Mean Avoiding Every Legal Process
Probate is not inherently a failure of estate planning. It is a legal mechanism for administering property that falls within the probate estate.
Avoiding probate can reduce court involvement for particular assets, and trust planning can sometimes prevent additional probate proceedings in another state when someone owns property outside Florida.
But a trust does not make administration disappear.
A successor trustee still has responsibilities involving assets, debts, beneficiaries, and distribution. The Florida Bar notes that many of the practical tasks performed by a personal representative must also be performed by a trustee administering a revocable trust.
The goal, then, is not simply less paperwork.
It is a transfer plan that matches the person’s wishes, family circumstances, assets, and Florida law.
Probate Avoidance in Coral Springs and Broward County
For families in Coral Springs and Broward County, probate planning ultimately comes down to the relationship between Florida law and the way the family’s assets are actually owned.
A homeowner may have very different planning considerations from someone whose estate consists primarily of retirement and investment accounts. A married couple may face different issues from an unmarried person. Someone with children from a previous relationship may need to coordinate beneficiary designations and ownership structures particularly carefully.
There is no single “avoid probate” document that produces the same result for every Florida estate.
The better question is which legal mechanism should govern each significant asset and whether those mechanisms work together.
When an Estate Planning Attorney Can Help
If you are planning your estate in Coral Springs, Broward County, or elsewhere in South Florida, an estate planning attorney can review more than whether you have a will.
The review can include how assets are titled, whether beneficiary designations match your wishes, whether a revocable trust is appropriate and properly funded, and whether Florida’s homestead rules affect the plan.
The objective is not to avoid probate at all costs.
It is to understand which assets will pass through probate, which can pass outside it, and whether the overall plan produces the result you actually intend.
Reinfeld & Cabrera P.A. assists clients with estate planning, trusts, probate, and related matters in Coral Springs, Broward County, and throughout South Florida.
If you are reviewing an existing estate plan or creating one for the first time, contact Reinfeld & Cabrera P.A. to discuss how your assets are owned and how Florida law may affect their transfer after death.
Questions People Often Ask
Can I avoid probate completely in Florida?
Some estates can be structured so that significant assets pass outside probate. Whether that is appropriate depends on the assets, ownership structures, beneficiary designations, family circumstances, and Florida law.
Does having a will avoid probate?
No. A will generally directs the distribution of property that remains subject to probate. It does not, by itself, remove those assets from the probate process.
Does a revocable trust avoid probate in Florida?
It can, but the relevant assets must be properly transferred to the trust or otherwise coordinated with it. An unfunded trust may leave assets subject to probate.
Can a beneficiary designation avoid probate?
A valid beneficiary designation can allow certain assets to pass outside probate. Florida law specifically recognizes pay on death accounts and beneficiary registrations for qualifying securities.
Can I put my Florida home in a trust to avoid probate?
Florida homestead is subject to special constitutional and statutory rules. A trust may be appropriate in some circumstances, but homestead should not be treated like an ordinary investment asset.
Is avoiding probate always the best option?
Not necessarily. Probate serves legitimate purposes, including administration of assets that fall within the probate estate. The appropriate estate plan depends on the circumstances rather than on avoiding court involvement as an end in itself.
There is something different about dealing with a family business. The people answering the phone may know the people making the decisions. The person whose name is on the door may still be around when you have a question six months later. And when something goes wrong, there usually isn’t an impressive chain of departments available to explain why nobody knows who is responsible.
A family owned law firm can have some of those same characteristics.
That does not make family ownership a substitute for legal experience. If you need an attorney in Coral Springs, you still want someone who knows the relevant area of Florida law. You need someone who understands your particular problem, and can explain what your options actually are. The fact that a law firm is owned by a family does not magically accomplish any of those things.
What it can change is the relationship you have with the firm.
What Does Family Owned and Operated Actually Mean?
In a family owned and operated business, the people behind the company have a personal connection to what happens there. Their reputation is attached to the business. Their relationships with clients can continue for years. And the people who own the firm may also be involved in the day to day work.
For a law firm, that can be valuable. Legal matters are rarely as simple as handing someone a document, collecting a fee, and saying goodbye. A client may have questions later, another legal issue may come up. Perhaps a matter that seemed straightforward at the beginning may take an unexpected turn. Knowing who to call can make a real difference.
This is one reason some people prefer working with family owned businesses. They want to know who they are dealing with. People want to have a sense that the relationship matters to the people on the other side of the desk.
A Relationship That Can Continue Over Time
For clients in Coral Springs and throughout Broward County, that kind of relationship can be useful. Especially when legal needs extend over ongoing estate planning and business succession strategies with a local family in Broward County.me. Estate planning, probate, real estate transactions, business matters, and other legal issues can bring people back to the same law firm at different stages of their lives. Having attorneys who already understand the background can save everyone from starting the story from page one.
There is also a practical advantage to knowing how a firm is structured. Before hiring any attorney in Coral Springs, it is reasonable to ask who will actually handle your matter. You want to see how directly you can communicate with the attorney. There needs to be consistency – and whether the same people will remain involved as the case or transaction develops.
Those questions matter regardless of whether a firm is family owned. But they can be especially relevant when a firm’s owners are also actively involved in its work.
Managing Local Legal Matters Across Broward County
For families and business owners living in Coral Springs, Parkland, Fort Lauderdale, and surrounding South Florida communities, legal challenges rarely exist in a vacuum. An estate planning decision can directly impact a commercial real estate holding, and a family business succession plan can intersect directly with probate or guardianship administration.
Working with an established local firm means your legal team understands the specific procedural tendencies of the 17th Judicial Circuit Court and regional municipal codes. Rather than treating your matter as a routine transaction processed by an anonymous case manager in a distant corporate hub, a boutique local practice evaluates how your legal choices affect your daily life, your business balance sheet, and your long term family security in Broward County.
Family Businesses Understand Some Familiar Problems
Family ownership can also matter to people who run their own businesses. A family owned business often understands that legal decisions can affect relationships as well as balance sheets. Ownership, contracts, real estate, succession planning, and disputes can sometimes overlap with personal concerns.
For business owners in Coral Springs and the surrounding Broward County community, having a law firm that understands that overlap can be useful.
Family Owned Does Not Mean Every Firm Works the Same Way
None of this means that every family owned law firm operates in exactly the same way. Some are small. Many have several attorneys and staff. Some owners are heavily involved in client matters, while others have a more traditional management role. The label itself tells you only part of the story.
The better question is what the firm’s family ownership actually means for you as a client.
You can look at the firm’s practice areas and experience, but you can also ask how the attorneys work, who you will deal with, how communication is handled, and whether the firm is built around relationships that continue after one legal matter is finished.
You Know Who You Are Calling
One of the less glamorous advantages of a family owned law firm is also one of the easiest to appreciate: knowing who you are dealing with.
When a legal issue comes up, clients generally do not want to spend half their morning explaining the same situation to a new person. They want to reach someone who knows the matter, understands the history, and can tell them what happens next.
A family owned and operated firm can be well suited to that kind of continuity. The attorneys who own the business may remain closely involved with clients and their legal matters over time. For someone dealing with an estate, a property transaction, a business concern, or another ongoing legal issue, having a familiar point of contact can make the process considerably easier to navigate.
It also gives clients an opportunity to develop a relationship with the attorneys they rely on. You may initially contact a lawyer about one issue and return years later with another. By then, you are no longer starting with a blank page. The attorney may already understand your circumstances, your priorities, and the history behind the new question.
Direct Attorney Accountability Versus Corporate Law Factories
The modern legal landscape is increasingly dominated by large institutional law firms featuring multi tiered phone trees, layers of paralegals, and shifting case managers. When clients call with urgent questions about a probate timeline or a real estate closing, they are often forced to re-explain their entire situation to a stranger.
A family owned law firm operates on a completely different model of accountability:
Direct Communication Lines: You speak directly with the attorneys whose names are on the door and who actively manage your legal filings.
Institutional Memory: Because the firm builds multi generational relationships with local families, your historical legal context is preserved for future needs.
Aligned Interests: The firm’s local reputation in Northwest Broward County depends entirely on transparent communication, reliable case preparation, and dedicated client advocacy.
Talk With Our Attorneys
If you are considering a family owned law firm in Coral Springs, the easiest way to see whether the relationship feels right is to have a conversation.
Yes, creditors can sometimes take money from a trust in Florida, but their rights depend on who owes the debt and how the trust is structured. Florida law generally allows creditors to reach assets in a revocable trust during the creator’s lifetime. A valid spendthrift provision in an irrevocable trust can protect a beneficiary’s undistributed interest from many ordinary creditors, although statutory exceptions apply.
When can creditors reach trust assets in Florida?
Revocable trusts: Creditors can generally pursue assets in a revocable trust when the person who created it owes the debt.
Spendthrift trusts: A valid spendthrift provision can protect a beneficiary’s undistributed interest from many ordinary creditors.
Distributed inheritances: Once the trustee pays the beneficiary, the funds may become subject to ordinary collection procedures.
Exceptions: Certain support claims and other legally recognized circumstances can permit creditors to reach otherwise protected interests.
Fraudulent transfers: Florida law allows qualifying transfers intended to hinder, delay, or defraud creditors to be challenged.
These rules are governed primarily by Part V of Florida’s Trust Code, including the provisions addressing spendthrift trusts and claims against revocable trust assets. The sections below explain how each rule works and what it means for beneficiaries and trustees in Coral Springs and Broward County.
Key points for Florida residents:
A creditor generally has broader access to assets in a revocable trust while its creator is alive.
A valid spendthrift provision can restrict a beneficiary’s creditors from reaching an undistributed trust interest.
Certain claims, including qualifying support obligations, may fall within statutory exceptions.
Money distributed to a beneficiary may lose some or all of its protection under trust law.
Transfers designed to hinder existing creditors can be challenged under Florida’s voidable transfer laws.
These rules matter when someone is planning an inheritance, administering a deceased relative’s estate, or responding to a creditor claim in Coral Springs or elsewhere in Broward County.
1. Can Creditors Reach Assets in a Florida Trust?
The first step is identifying whose debt is involved. Florida law does not treat the trust creator and the beneficiary as interchangeable.
When the person who created the trust owes the debt
A revocable living trust generally does not protect its assets from the creator’s creditors during the creator’s lifetime. Under Florida Statute § 736.0505, property in a revocable trust remains available to satisfy the claims of the settlor’s creditors.
A settlor is the person who creates and funds a trust. If that person can revoke the trust and recover its assets, the trust ordinarily does not place those assets beyond the reach of legitimate creditor claims.
Example: A Coral Springs homeowner transfers investment accounts into a revocable living trust. The homeowner later defaults on a substantial personal loan. The transfer alone does not prevent the lender from pursuing trust assets that remain subject to the homeowner’s control.
The analysis can change after the creator dies or when a trust is genuinely irrevocable. Even then, the specific statutory rules and the circumstances surrounding the transfer must be examined.
When a beneficiary owes the debt
The rules can be considerably more protective when the debtor is a beneficiary of an irrevocable trust created by someone else.
Under Florida Statute § 736.0502, a valid spendthrift provision can prevent a beneficiary from voluntarily transferring the protected interest. It can also prevent most creditors from attaching that interest before the trustee distributes the money.
Example: A father establishes an irrevocable trust for his adult daughter. The trust contains an enforceable spendthrift provision. The daughter later falls behind on credit card payments. A card issuer generally cannot seize her undistributed beneficial interest merely because she owes money.
That does not mean the trust is immune from every claim. Florida law recognizes exceptions, and a creditor may have other remedies depending on the facts.
2. What Is a Spendthrift Trust in Florida?
A spendthrift trust contains language restricting a beneficiary’s ability to transfer the beneficiary’s interest. The restriction also limits the ability of creditors to reach that interest before the trustee distributes it.
Florida Statute § 736.0502 establishes the requirements for an enforceable spendthrift provision. The provision must restrain both voluntary and involuntary transfers of the beneficiary’s interest.
This distinction matters. A clause that merely expresses the creator’s hope that a beneficiary will manage money responsibly does not necessarily establish the statutory protection.
How spendthrift protection works
Suppose a trust holds $400,000 for a beneficiary who has accumulated substantial unsecured debt. The trustee must follow the trust’s terms when deciding whether and when to distribute funds.
If the trust contains an enforceable spendthrift provision, the beneficiary generally cannot assign the protected interest to a creditor. The creditor ordinarily cannot attach that undistributed interest either, subject to the exceptions established by law.
The trustee must still administer the trust according to its terms and applicable fiduciary duties. Spendthrift language does not give a trustee unlimited discretion to disregard the beneficiary’s rights.
Does every irrevocable trust provide creditor protection?
No. Irrevocability alone does not guarantee that trust assets are protected from every creditor.
The trust’s language matters. So does the identity of the debtor. A trust created by a third party for a beneficiary presents a different legal situation from a trust a debtor creates for personal benefit.
A transfer into an irrevocable trust can also be challenged if it violates Florida’s voidable transfer laws. The relevant provisions appear in Florida Statutes Chapter 726.
The source of the money matters as well. A court will examine the actual arrangement rather than rely exclusively on the label attached to the trust.
3. Revocable Trusts vs. Irrevocable Trusts
The difference between revocable and irrevocable trusts is central to creditor protection.
Feature
Revocable trust
Irrevocable trust
Can the creator generally revoke it?
Yes, subject to the instrument and law
Generally not unilaterally, although some arrangements permit modification
Creditor access to the creator’s assets
Generally available during the creator’s lifetime
Depends on the creator’s retained rights and applicable law
Protection for a beneficiary
Depends on the arrangement and stage of administration
A valid spendthrift provision can protect an undistributed interest from many creditors
Can every creditor claim be blocked?
No
No
Can the transfer be challenged?
Depending on the circumstances
Yes, including under voidable transfer laws
Revocable Living Trusts
Revocable living trusts are popular for good reason. They let people decide how their property will be handled after death without necessarily putting their families through probate. They can also make things easier if the person who created the trust becomes unable to manage their own affairs.
But there’s an important limitation when creditors are involved. Under Florida Statute § 736.0505, assets in a revocable trust are generally available to the creator’s creditors during their lifetime. The creator can still revoke the trust and take the property back, so the transfer does little to separate those assets from their personal financial obligations.
This is where people can get caught out. A revocable trust may be perfectly suitable for managing an estate, yet do very little to protect the creator’s property from a creditor pursuing an unpaid debt. Those are two different goals, and a trust designed for one should not be mistaken for a solution to the other.
Irrevocable Trusts
Irrevocable trusts work differently because the person who creates one generally gives up the ability to take the assets back whenever they want. Depending on the trust’s terms, the property may be managed for beneficiaries who cannot demand an immediate distribution. That separation can make it harder for certain creditors to reach the assets.
Of course, the details matter. A trust does not become immune to creditors simply because its creator calls it irrevocable. The rights retained by the creator can affect the protection available, and Florida law allows creditors to challenge certain transfers.
Consider someone who moves valuable property into an irrevocable trust after learning that a lawsuit may be coming. Under Florida’s Uniform Voidable Transactions Act, Chapter 726, a creditor may challenge the transfer if the legal requirements are satisfied. A court can look at the circumstances and determine whether the arrangement was used to put assets beyond a creditor’s reach.
For anyone planning an estate, the distinction matters. An irrevocable trust may provide stronger creditor protection, but that protection comes with restrictions on what the creator can do with the property later. It is worth understanding those restrictions before transferring assets that may be difficult or impossible to recover.
4. Which Creditors Can Reach a Beneficiary’s Trust Interest?
Florida law provides meaningful protection for many trust beneficiaries, but it does not make every trust interest unreachable.
Ordinary unsecured creditors
Credit card companies and personal loan lenders generally cannot attach a beneficiary’s interest before distribution when an enforceable spendthrift provision applies.
That protection is not a blanket defense against every legal action. A creditor may still investigate whether an exception applies or whether the trust arrangement can be challenged.
Child support and spousal support
Florida Statute § 736.0503 establishes exceptions to spendthrift protection for certain claims. These include qualifying claims for support or maintenance of a beneficiary’s child, spouse, or former spouse.
The statute also addresses certain services that protect the beneficiary’s interest in the trust.
The precise claim and the statutory requirements matter. A creditor cannot assume that every family law judgment automatically overrides a spendthrift provision.
Government claims
Government claims require separate analysis. The availability of trust assets depends on the governing statute, the type of obligation, and the beneficiary’s rights under the trust.
For example, a claim involving taxes should not be analyzed as though it were an ordinary credit card debt. Federal collection rules may also be relevant.
Judgments and lawsuits
A creditor with a judgment does not automatically gain unrestricted access to every trust asset. The judgment establishes a legal claim, but collection still depends on the property involved and the law governing that property.
A court may need to determine whether the debtor has a present right to receive money or only a protected interest in future distributions.
5. What Happens When the Trustee Distributes the Money?
Distribution can change the analysis significantly.
Spendthrift protection generally applies to the beneficiary’s interest before the trustee transfers the money. Once funds reach the beneficiary, the creditor may be able to pursue them under ordinary collection law.
The outcome depends on where the money goes and whether another legal protection applies.
Money deposited into a personal bank account
Suppose a trustee distributes $50,000 to a beneficiary with outstanding credit card debt. The beneficiary deposits the money into a personal checking account.
The beneficiary should not assume that the original trust provision continues to protect the funds indefinitely. A judgment creditor may be able to pursue money in the account through lawful collection procedures.
Florida law provides exemptions for certain property and income. Those exemptions must be evaluated independently from the trust’s spendthrift clause.
Money used to buy another asset
Converting a distribution into another asset does not automatically preserve trust protection.
The result depends on the asset purchased and any applicable exemption. For example, Florida’s homestead protections may be relevant to a qualifying primary residence, but those rules have specific requirements and exceptions.
A beneficiary should not assume that purchasing a home with trust money makes the funds untouchable. The source of the money, the property’s use, and the applicable legal requirements all matter.
Money retained by the trustee
When the trustee has not distributed the money, the beneficiary’s creditors may have fewer collection options. The creditor must account for the trust terms and any applicable statutory exceptions.
The trustee should not make an improper distribution simply because a beneficiary is facing collection pressure. The trustee must follow the instrument and applicable law.
6. Can a Trustee Refuse to Distribute Money Because of a Creditor?
The answer depends on the trust’s distribution terms and the trustee’s legal duties.
Some trusts require distributions when specified conditions are met. Others give the trustee discretion to decide when distributions are appropriate.
A trustee cannot automatically withhold a mandatory distribution merely because the beneficiary has creditors. The trust instrument and Florida law determine what the trustee must do.
Discretionary distributions
Under Florida Statute § 736.0504, a creditor generally cannot compel a distribution that remains within the trustee’s discretion, subject to statutory exceptions.
For example, a trust may authorize distributions for a beneficiary’s health or education. The trustee must exercise that discretion according to the trust’s terms and fiduciary obligations.
A creditor generally cannot force the trustee to exercise discretion in the creditor’s favor simply because the beneficiary owes money.
Mandatory distributions
A trust may require a trustee to distribute a fixed amount at a specified age or on a defined date.
When a distribution becomes due, the legal position can differ from a situation in which the trustee has discretion. Florida Statute § 736.0506 addresses creditor claims involving certain overdue mandatory distributions.
The timing and wording of the trust are important. A beneficiary should not assume that an enforceable right to a distribution receives the same treatment as a purely discretionary interest.
What trustees should avoid
A trustee should not invent new restrictions simply to prevent a beneficiary’s creditor from collecting. The trustee should also avoid making an unauthorized distribution based on informal pressure from a beneficiary or creditor.
When a demand arrives, the trustee should review the instrument and determine whether the claimant has a legally enforceable right to the funds.
7. Can Creditors Challenge a Transfer Into an Irrevocable Trust?
Yes. Florida law permits certain transfers to be challenged when the transfer meets the legal requirements for a voidable transaction.
Under Florida Statutes Chapter 726, a court may examine the circumstances surrounding a transfer to determine whether it was made with actual intent to hinder, delay, or defraud a creditor. The statute also addresses certain transfers made without reasonably equivalent value when the debtor meets specified financial conditions.
A transfer made before financial trouble
A person who creates an irrevocable trust as part of a legitimate estate plan before any creditor dispute arises may present a different case from someone who transfers assets after receiving a lawsuit or collection demand.
Timing is relevant, but timing alone does not decide the outcome. The court may examine the debtor’s financial condition and other evidence surrounding the transaction.
A transfer made after a lawsuit begins
Suppose a business owner faces a substantial judgment and then transfers most personal assets into a trust for a family member.
The creditor may investigate whether the transfer was designed to obstruct collection. If the evidence supports a claim under Chapter 726, the creditor may seek a remedy through the court.
The trust’s irrevocable status does not automatically defeat that challenge.
A debtor who transfers property while concealing assets or giving misleading information may create additional legal exposure. The precise consequences depend on the conduct and the applicable law.
Anyone considering a trust transfer during an existing creditor dispute should obtain legal advice before moving property. A transfer that appears protective at first can become the basis of further litigation.
8. Florida Court Decisions That Help Explain Creditor Access
Statutory language establishes the basic rules, while court decisions illustrate how those rules operate in actual disputes.
Miller v. Kresser: Practical control did not defeat spendthrift protection
In Miller v. Kresser, 34 So. 3d 172 (Fla. 4th DCA 2010), Gary Kresser obtained a judgment of approximately $1.02 million against James Miller and his construction company. Unable to collect, Kresser pursued assets held in an irrevocable trust established for James by his mother. The trust contained a spendthrift clause and named James’s brother, Jerry, as trustee.
Although Jerry held formal authority over distributions, the trial court found that James effectively controlled the trust’s investments and operations. It invalidated the spendthrift protection and allowed Kresser to pursue trust assets, including the trust’s interest in property in Islamorada.
The Fourth District Court of Appeal reversed. It found that Jerry retained the legal authority to decide whether to distribute trust property. James could influence decisions, but he could not compel distributions. His practical involvement therefore did not, by itself, make the undistributed assets available to his creditor.
Why it matters: A creditor cannot necessarily seize trust assets because a beneficiary appears to control their management. The trust’s terms and the beneficiary’s enforceable rights are central to determining whether assets remain protected.
Zlatkiss v. All America Team Concepts: A valid judgment does not guarantee access to trust funds
In Zlatkiss v. All America Team Concepts, LLC, 116 So. 3d 525 (Fla. 5th DCA 2013), Robert and Linda Zlatkiss lent $350,000 to a company whose principal, Louis Steinmetz, personally guaranteed the loan. Steinmetz had represented that he had approximately $6.85 million available through a trust. When the loan went unpaid, the Zlatkisses sought recovery and challenged the constitutionality of Florida’s spendthrift trust protections after the trustee refused to release funds to satisfy the debt.
The Fifth District Court of Appeal upheld the protections. It explained that the constitutional right to access the courts allows creditors to pursue legal claims, but does not guarantee collection from every asset belonging to a debtor. Florida’s recognition of valid spendthrift trusts also predated the statutes challenged in the case.
Why it matters: A creditor may obtain a judgment against a debtor without gaining access to the debtor’s trust interest. For lenders, the case underscores the importance of determining whether a borrower can actually access trust assets before relying on them as a source of repayment.
In re Brown: A debtor could not shield an income interest in a trust she created
In In re Brown, 303 F.3d 1261 (11th Cir. 2002), Jane McLean Brown used an inheritance of approximately $250,000 to establish an irrevocable charitable remainder unitrust. She retained the right to receive annual payments equal to 7% of the trust’s value, while the remaining assets were designated for charitable beneficiaries. The trust included a spendthrift clause.
When Brown filed for Chapter 7 bankruptcy, she argued that the clause protected her interest from creditors. The Eleventh Circuit rejected that argument. Because Brown had created the trust for her own benefit and retained a right to income, she could not use the spendthrift provision to shield that interest in bankruptcy. Her retained income rights were available to the bankruptcy estate, although the trust principal itself was not available to satisfy her personal debts.
Why it matters: An irrevocable trust does not automatically protect every interest held by the person who created it. Courts may distinguish between property transferred irrevocably to others and income rights the creator retained for personal benefit.
What these decisions mean for Florida creditors and beneficiaries
These cases illustrate different limits on creditor access to trust assets. Miller examines practical control over a discretionary trust. Zlatkiss addresses the limits of collecting a judgment from protected trust interests. In re Brown concerns a debtor who created a trust while retaining an income interest.
The outcome depends on the trust agreement, the debtor’s legal rights, and the applicable law. Bankruptcy can introduce additional rules, so a decision arising under federal bankruptcy law should not automatically be treated as controlling every Florida collection dispute.
9. Household Debt and the Risk to Inheritances
An inheritance can arrive at an awkward time: a beneficiary may be dealing with unpaid debts just as money or property passes into their hands. The scale of household debt in the United States helps explain why this issue matters.
According to the Federal Reserve Bank of New York’s February 2026 household debt report, Americans owed approximately $18.8 trillion in household debt at the end of 2025. That balance grew by roughly $191 billion in a single quarter. The report also found that 4.8% of outstanding household debt was in some stage of delinquency.
These figures show the scale of the debt burden facing American households. They do not tell us how many Florida beneficiaries face collection claims, or how often creditors successfully reach trust assets. They do, however, provide context for a practical concern: when someone with unpaid debts inherits money, the legal protection surrounding that inheritance can make a substantial difference.
What these numbers mean for trust beneficiaries
A debt does not automatically give a creditor the right to seize trust assets. Florida law distinguishes between assets held in a trust and property a debtor owns or has the legal right to receive. A properly drafted spendthrift provision may protect a beneficiary’s undistributed interest from many creditors, subject to statutory exceptions.
That protection can change when a trustee distributes the funds. Once the inheritance reaches the beneficiary, it may become available to creditors under ordinary collection rules, depending on the circumstances and any applicable exemptions.
The figures above establish the financial context, not the legal outcome. Whether a creditor can reach an inheritance ultimately depends on the trust’s terms, the beneficiary’s rights, and the protections Florida law provides.
10. Common Misconceptions About Trusts and Creditors in Florida
Misconception 1: An irrevocable trust is immune from every creditor
Reality: Irrevocability does not eliminate all creditor rights. The creator’s retained interests, statutory exceptions, and potential challenges to the original transfer can affect the outcome.
Misconception 2: A revocable living trust protects the creator’s assets from personal debts
Reality: Florida Statute § 736.0505 generally allows creditors to reach assets in a revocable trust during the settlor’s lifetime.
A revocable trust may serve important estate planning purposes, but it should not be treated as a substitute for a valid creditor protection strategy.
Misconception 3: A beneficiary’s inheritance is protected forever
Reality: Spendthrift protection generally concerns the beneficiary’s interest before distribution. After receiving money, the beneficiary may face ordinary collection proceedings unless another protection applies.
Misconception 4: A creditor with a judgment can seize anything connected to the debtor
Reality: A judgment does not eliminate statutory protections. The creditor must still identify property that can legally be reached.
Misconception 5: A trustee can always refuse payment to keep creditors away
Reality: The trustee must follow the trust instrument. A mandatory distribution cannot automatically be withheld because the beneficiary has debts.
Misconception 6: Moving money into a trust after a lawsuit begins solves the problem
Reality: A creditor may challenge a transfer under Florida’s voidable transfer laws. The transaction can create further legal disputes rather than resolve the original debt.
Misconception 7: Trust protection and Florida homestead protection are the same
Reality: They are separate legal concepts. Florida’s homestead protections are governed by distinct constitutional and statutory rules, and the requirements depend on the property and circumstances.
11. Florida Homestead, Exemptions, and Other Protections
Trust law is only one part of the creditor analysis. Other Florida laws may protect particular assets or income, but those protections should not be assumed to apply automatically to inherited money.
Florida Homestead: When a Home Gets Special Protection
Florida’s homestead exemption is one of the state’s strongest forms of asset protection. Under the Florida Constitution, qualifying primary residences receive substantial protection against forced sale by many creditors. That can make a significant difference when someone faces a judgment and owns a home.
The protection has specific requirements and exceptions. In Havoco of America, Ltd. v. Hill (2001), a creditor argued that a debtor had used funds to acquire a homestead with the intent to keep those assets beyond creditors’ reach. The Florida Supreme Court concluded that the homestead exemption still applied under the circumstances, even though the purchase was allegedly motivated by creditor avoidance. The court explained that the constitutional protection could not be denied on that basis alone when the transaction did not fall within an established exception.
That ruling is powerful, but it is not a blanket permission to move any asset into a home and declare it untouchable. The property must qualify as homestead, and the legal circumstances matter. Nor does the decision mean that money held in a trust automatically receives homestead protection. The rules governing trust assets and those governing a qualifying residence are distinct.
Wage Exemptions: Your Paycheck May Have Protection of Its Own
Florida law also protects certain earnings from creditors. Under Florida Statute § 222.11, qualifying head of family earnings receive specific protections, subject to the statute’s requirements and exceptions.
These rules matter when a creditor seeks to garnish wages. They do not automatically extend to every dollar that later enters the same bank account. A beneficiary who receives a trust distribution should not assume that the payment qualifies as protected earnings simply because it will be used to cover ordinary living expenses.
The source of the money and the legal requirements for the exemption both matter. When wages and other funds are mixed together, identifying the protected portion may become more complicated.
Bankruptcy: A Different Set of Rules Can Change the Outcome
When a debtor files for bankruptcy, the analysis moves beyond ordinary state court collection procedures. Federal bankruptcy law determines what enters the bankruptcy estate and provides mechanisms for challenging certain transfers made before filing.
A trust that limits a creditor’s access under Florida law does not necessarily produce the same result in bankruptcy. The outcome depends on the debtor’s interest in the trust and the applicable bankruptcy rules. Transfers made before filing may also face scrutiny under federal law.
This is particularly important when someone creates a trust, transfers property into it, or retains rights to receive payments before seeking bankruptcy protection. The word irrevocable does not settle the question. The actual arrangement and the timing of the transactions must be examined.
Debt Collection Rights: Creditors Have Rules to Follow Too
Trust disputes are not the only legal issue a beneficiary may face. Collection communications can raise separate questions about what a debt collector is allowed to say or do.
However, rules governing collection conduct do not determine whether a creditor can legally reach a particular trust interest. A collector may be restricted in how it pursues a debt while still having a valid claim against assets available under applicable law. Conversely, a creditor’s right to collect a debt does not give it unlimited authority to seize protected property.
The important distinction: Asset protection and debt collection conduct are separate questions. A beneficiary needs to understand both the legal status of the assets and the limits on the creditor’s collection methods.
12. Practical Procedures When a Creditor Targets Trust Assets
A creditor demand involving a trust should be handled carefully. The trustee and beneficiary may have different rights and obligations, so each should understand their own position before responding.
Step 1: Identify the debtor
Determine whether the debt belongs to the trust creator, the beneficiary, or another person.
This is the first legal distinction to establish. A creditor pursuing the settlor may have rights that would not apply to an ordinary creditor of a beneficiary.
Step 2: Obtain and review the trust instrument
Locate the complete trust document and any amendments. Identify whether the trust is revocable or irrevocable and whether it contains a spendthrift provision.
Review the distribution terms as well. The trustee’s authority may differ depending on whether distributions are mandatory or discretionary.
Step 3: Determine whether the money has been distributed
Establish whether the assets remain in the trust or have already been transferred to the beneficiary.
This distinction may determine which creditor remedies are available. Keep records of the distribution date and the destination of the funds.
Step 4: Identify the creditor’s legal claim
Review the demand letter, judgment, court order, or other documents identifying the debt.
Determine whether the claim involves ordinary consumer debt, a support obligation, a tax liability, or another category that may trigger different rules. Do not assume every creditor has the same collection rights.
Step 5: Preserve relevant records
Keep copies of the trust instrument, account statements, distribution records, creditor correspondence, and any relevant court filings.
Do not destroy or alter records in response to a collection demand. Accurate documentation can help establish the nature and timing of the trust arrangement.
Step 6: Avoid informal promises or unauthorized distributions
A beneficiary should not promise a creditor access to trust money without understanding the legal position. A trustee should not make a distribution that conflicts with the trust instrument or applicable law.
If the creditor has served formal legal papers, observe the stated deadlines. Ignoring a court order or legal notice can create additional problems.
Step 7: Obtain legal advice when the claim is disputed
A Florida estate planning or trust litigation attorney can review the instrument and determine whether the creditor has a valid route to the assets.
Legal advice is particularly important when the trust creator retained control, a distribution is overdue, or the creditor alleges a fraudulent transfer.
Operational checklist for trustees
Before responding to a creditor demand, a trustee should:
Confirm the identity of the debtor and the nature of the claim.
Review the trust instrument and relevant amendments.
Determine whether the interest is subject to a valid spendthrift provision.
Establish whether the requested funds remain in trust.
Check whether a statutory exception may apply.
Preserve relevant records and comply with valid legal process.
Obtain advice before taking action that could breach fiduciary duties.
This checklist is intended to organize the initial review. It does not replace a legal determination about the particular trust or claim.
13. Hypothetical Situations: What Happens When Creditors Come Knocking?
Trust protection can sound wonderfully reassuring until a creditor comes looking for money. The details matter, though, and a creditor’s determination to get paid does not automatically give them the right to raid a trust. Here is how the rules might play out in everyday situations.
Scenario A: Credit card debt and an inheritance still in trust
Daniel owes $35,000 on his credit cards. His mother leaves him an inheritance through an irrevocable trust with a valid spendthrift provision. The trustee has not released the money, and Daniel has no right to demand an immediate payout.
His credit card companies cannot simply call the trustee and request a transfer. Under Florida Statute § 736.0502, ordinary creditors generally cannot attach a beneficiary’s protected interest before distribution. Certain exceptions and successful legal challenges can change that result.
Daniel’s debts have not vanished, of course. His creditors can still pursue other assets available under collection law.
The takeaway: Knowing someone is due an inheritance does not mean a creditor can collect it on demand. An inheritance still held in a protected trust is a very different proposition from money sitting in Daniel’s checking account.
Scenario B: The inheritance has already hit the bank
Maria receives $80,000 from a spendthrift trust and deposits it into her personal account. Unfortunately, she also has an unpaid judgment against her.
Once the trustee distributes the funds, the spendthrift provision generally stops protecting the money from ordinary collection remedies. Maria’s creditor may pursue the account, subject to applicable exemptions.
Maria might wish the trust’s protection came with the money. Unfortunately, legal protections do not always travel as well as cash.
The takeaway: Before distribution, the money may be protected inside the trust. After distribution, Maria may have to deal with creditors under the ordinary collection rules.
Scenario C: The person who created the trust owes money
Robert transfers $400,000 in investments into a revocable living trust. He remains in control and can take the assets back whenever he revokes the trust. Later, he defaults on a personal loan, and the lender obtains a judgment.
Robert argues that the investments belong to the trust. Florida law has an inconvenient answer for that strategy. Under Florida Statute § 736.0505, assets in a revocable trust are generally available to the creator’s creditors during the creator’s lifetime.
In other words, Robert cannot usually put his money in a legal box, keep the key in his pocket, and expect creditors to forget the box exists.
The takeaway: A revocable trust can serve important estate planning purposes. Shielding the creator’s assets from their own creditors generally is not one of them.
Scenario D: A beneficiary falls behind on child support
Elena receives financial support through an irrevocable trust established by her grandparents. She falls behind on court ordered child support, and the other parent seeks to enforce the obligation against her trust interest.
This is not necessarily treated like an unpaid credit card bill. Florida Statute § 736.0503 recognizes exceptions to spendthrift protection for certain claims, including qualifying child support obligations. The available remedy depends on the legal requirements and the trust’s terms.
Elena cannot assume that the spendthrift provision ends the discussion. The other parent cannot assume they are entitled to the entire trust balance, either.
The takeaway: Spendthrift protection can be powerful without being absolute. Certain support obligations receive special treatment under Florida law.
Scenario E: The trust appears just as a lawsuit looms
Michael learns that a former business partner intends to sue him over an unpaid debt. He transfers an investment property into an irrevocable trust for a relative, hoping the creditor will no longer be able to reach it.
The timing is likely to attract attention. Under Florida’s Uniform Voidable Transactions Act, Chapter 726, a creditor may challenge a transfer that meets the statutory requirements for being voidable. A court may consider when the transfer occurred and whether Michael retained control over the property.
Putting the property in an irrevocable trust does not automatically settle the matter in Michael’s favor. If the transfer violates the law, the creditor may seek remedies against it.
The takeaway: An irrevocable trust is not a legal reset button. Transferring property when a creditor is already on the horizon can leave the debtor fighting over the original debt and the transfer itself.
The common thread
A trust can protect an inheritance from certain creditors, but the protection has boundaries. Money still held in a qualifying spendthrift trust may receive different treatment from funds already paid to a beneficiary. A revocable trust generally offers little protection against the creator’s own creditors.
The useful question is what rights the debtor actually has over the assets. That answer usually matters far more than what the trust is called.
14. Frequently Asked Questions About Trusts and Creditors in Florida
Can credit card companies take money from a trust in Florida?
Generally, a credit card company cannot attach a beneficiary’s undistributed interest in a trust with an enforceable spendthrift provision, subject to statutory exceptions. The result may be different if the debtor created a revocable trust or has already received the funds.
Could creditors take money from an irrevocable trust?
Sometimes. An irrevocable trust can protect certain interests, but the result depends on the identity of the debtor, the trust terms, statutory exceptions, and whether the transfer can be challenged.
Can creditors reach a revocable living trust?
Florida Statute § 736.0505 generally permits creditors to reach the assets of a revocable trust during the settlor’s lifetime. The trust’s estate planning benefits do not automatically create creditor protection.
Does a spendthrift clause prevent every creditor from collecting?
No. Florida law recognizes exceptions to spendthrift protection. Certain support claims may qualify, and other legal doctrines may affect the result.
Can a creditor take money after the trustee distributes it?
Potentially. After distribution, the funds may be subject to ordinary collection procedures. Other exemptions may apply depending on the asset and circumstances.
Could a trustee refuse a distribution because the beneficiary owes money?
Not automatically. The trustee must follow the trust instrument and applicable law. A mandatory distribution may be treated differently from a discretionary one.
Can I put my assets in a trust to avoid paying existing debts?
A transfer made to hinder, delay, or defraud creditors may be challenged under Florida’s voidable transfer laws. Anyone considering a transfer while facing a claim should obtain legal advice before acting.
Are trust assets protected during bankruptcy?
Not automatically. Federal bankruptcy law contains rules concerning trust interests and certain transfers. The outcome depends on the trust arrangement and the bankruptcy circumstances.
Does Florida homestead protection apply to money inherited from a trust?
Not automatically. Homestead protection concerns qualifying property under a separate legal framework. Money received from a trust does not become protected merely because the beneficiary intends to use it to buy a home.
Can a creditor force a trustee to make a discretionary distribution?
Generally, a creditor cannot compel a distribution that remains within the trustee’s discretion, subject to statutory exceptions. The terms of the trust and the applicable law determine the trustee’s obligations.
What should I do if a creditor sends a demand involving my inheritance?
Keep the correspondence and obtain the complete trust document. Determine whether the demand concerns an undistributed interest or money already paid to you. If formal court papers arrive, pay attention to the response deadline and obtain legal advice promptly.
Can a creditor challenge a trust created by a deceased parent?
A creditor may examine whether the trust or a transfer into it is subject to a valid legal challenge. The creditor’s rights depend on the trust structure, the relevant statutes, and the facts of the transaction.
15. Trust Creditor Questions in Coral Springs and Broward County
For families in Coral Springs and Broward County, trust creditor disputes can arise during estate administration or after an inheritance becomes available. The applicable Florida statutes remain central regardless of the beneficiary’s city of residence.
A local review may be useful when a trustee receives a creditor demand, when beneficiaries disagree about a proposed distribution, or when a creditor alleges that assets were transferred to frustrate collection.
The location of the trust assets and the parties may affect procedural questions, but geography alone does not determine whether a creditor can reach a beneficiary’s interest.
Final Thoughts
Florida law distinguishes between assets controlled by the person who created a trust and a beneficiary’s interest in a trust established by someone else. A valid spendthrift provision can protect an undistributed beneficiary interest from many ordinary creditors, but statutory exceptions and the terms of the trust matter.
Revocable trusts generally do not protect a living settlor’s assets from that person’s creditors. Distributions can also change the analysis, and transfers intended to obstruct legitimate claims may be challenged.